🌱 Welcome to Grow Your Money Smart • 100% Free Financial Tools

Smart Personal Finance Tools & Debt Payoff Strategies

Free interactive budgeting frameworks, emergency fund planning calculators, and empirical debt elimination blueprints designed to help you take control of your wealth and build lasting financial freedom.

📊 Free Debt Payoff Calculator 💰 50/30/20 Budget Calculator
✓ 100% Free & No Registration ✓ Mathematical & Empirical Models ✓ Zero Fluff, Actionable Blueprints

FDIC $250k Limits: How to Insure $1 Million+ Safely (2026)
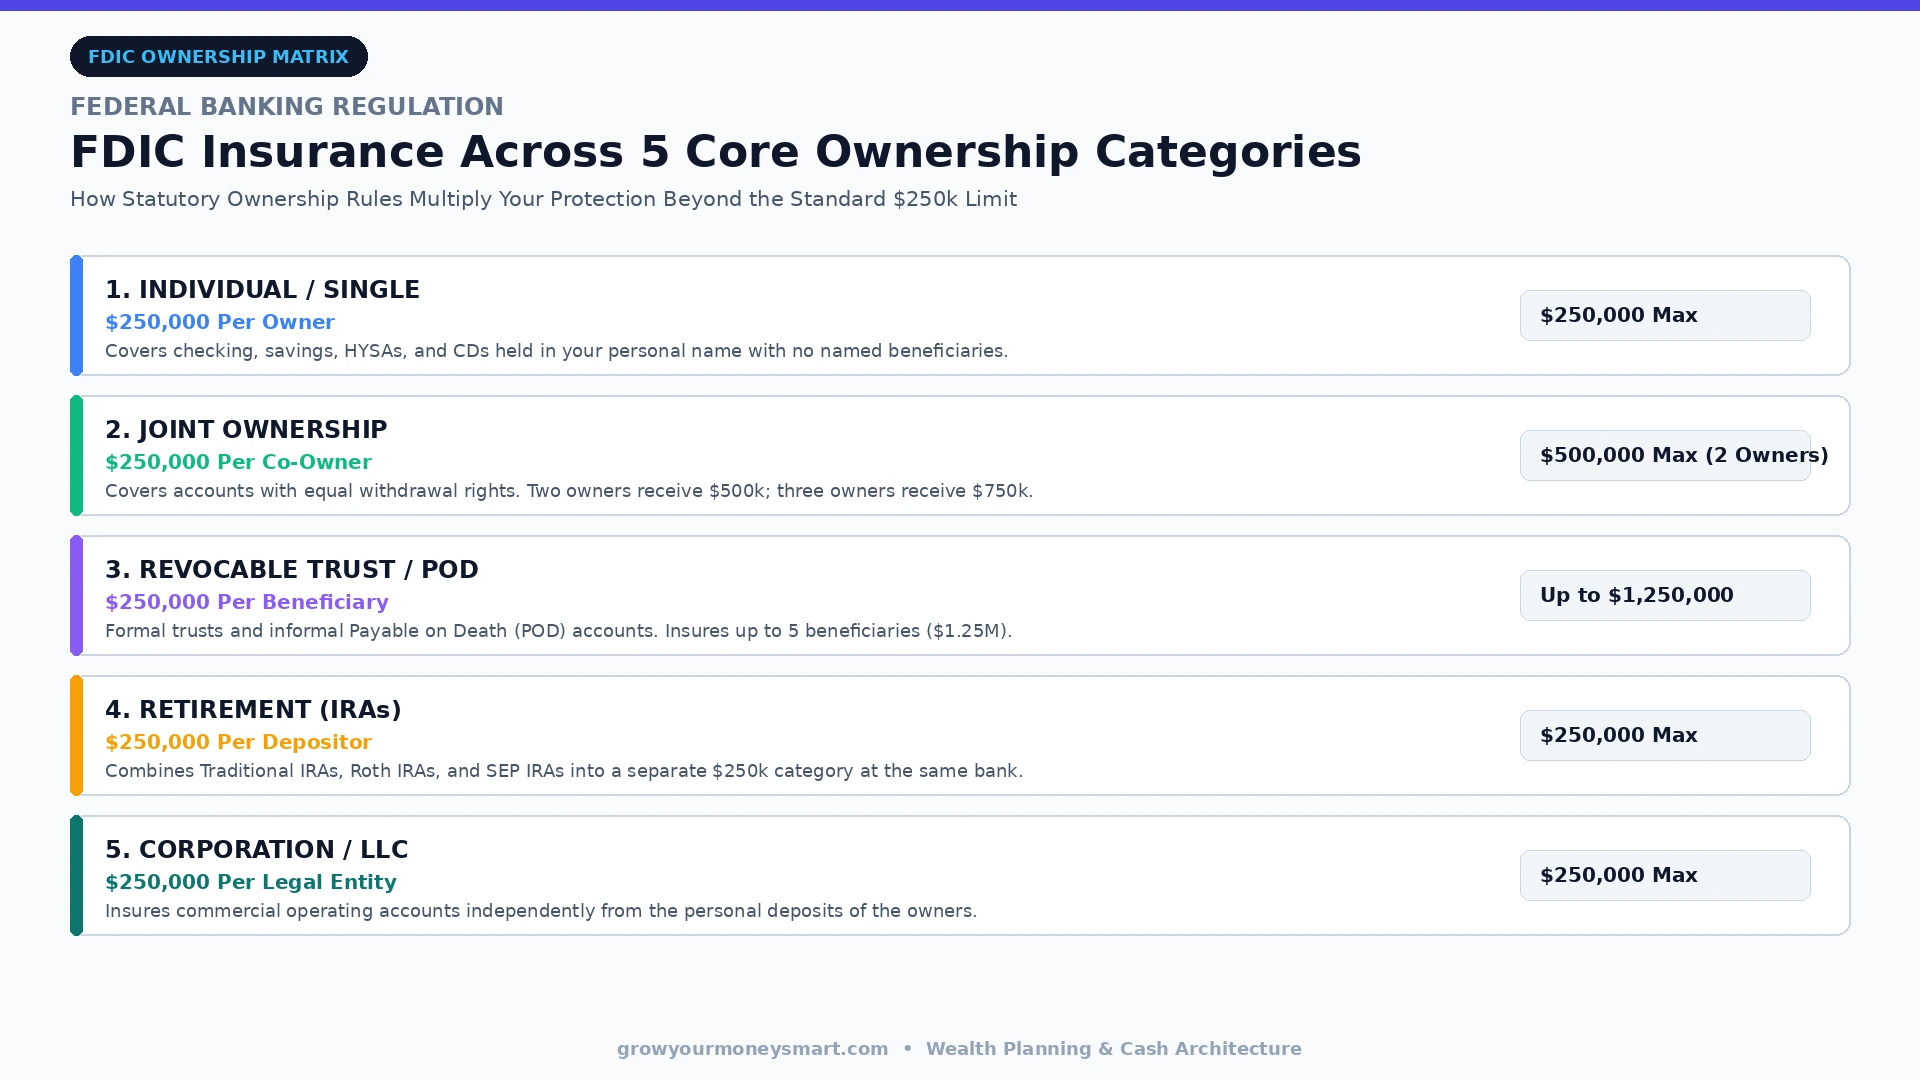
Chart detailing the 5 FDIC ownership categories including Single, Joint, Revocable Trust POD, Retirement IRAs, and Corporate accounts.

⚡ [QUICK ANSWER] FDIC Insurance Limits at a Glance The Federal Deposit Insurance Corporation (FDIC) provides standard coverage of $250,000 per depositor, per insured bank, for each account ownership category. You are not restricted to $250,000 per bank. By strategically structuring account ownership categories (single accounts, joint accounts, revocable trusts, and IRAs), a married couple … Read more
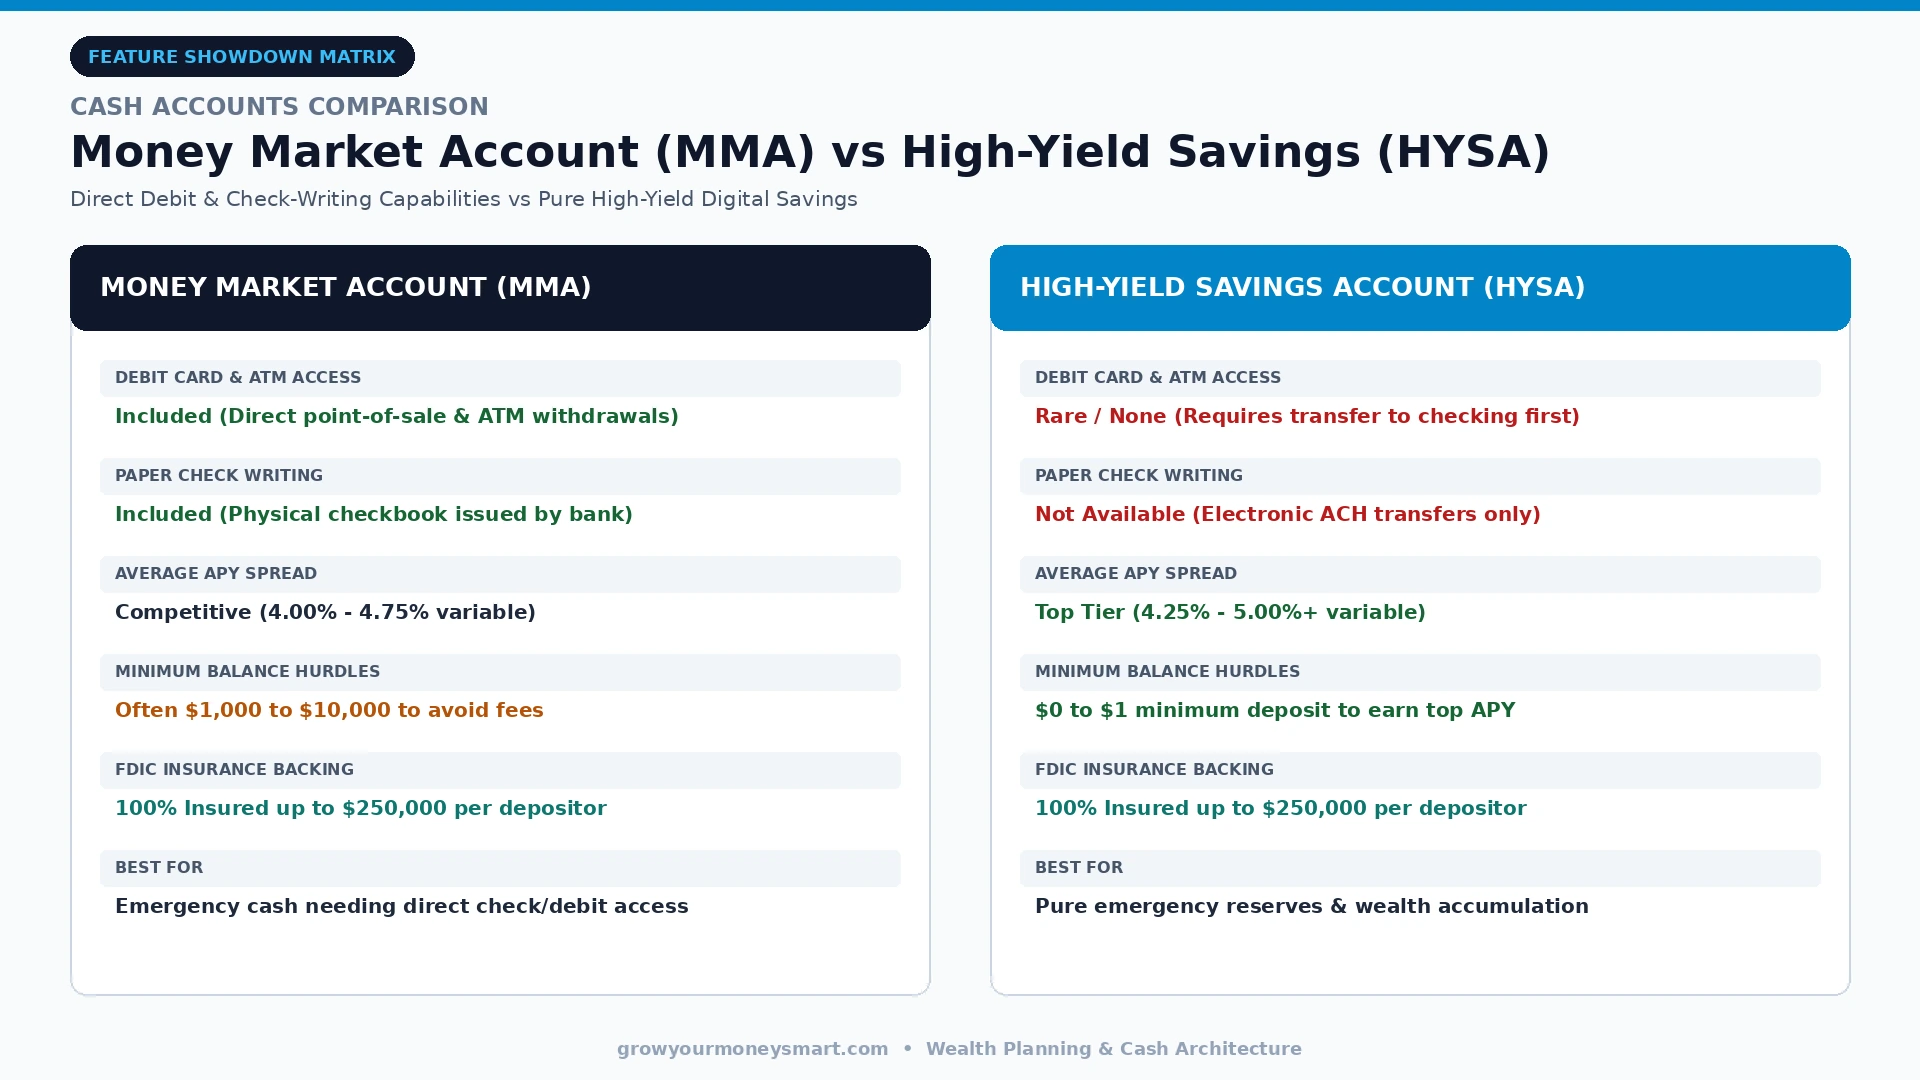
Money Market vs HYSA (2026): Key Differences Explained

Side-by-side comparison of Money Market Accounts and High-Yield Savings Accounts comparing debit cards, paper check writing, and APYs.

⚡ [QUICK ANSWER] Money Market Account vs HYSA at a Glance A Money Market Account (MMA) is an FDIC-insured bank deposit account that blends high savings yields with checking account features like debit cards and check-writing privileges. A High-Yield Savings Account (HYSA) focuses strictly on maximizing APY with pure digital transfers and zero checking frills. … Read more

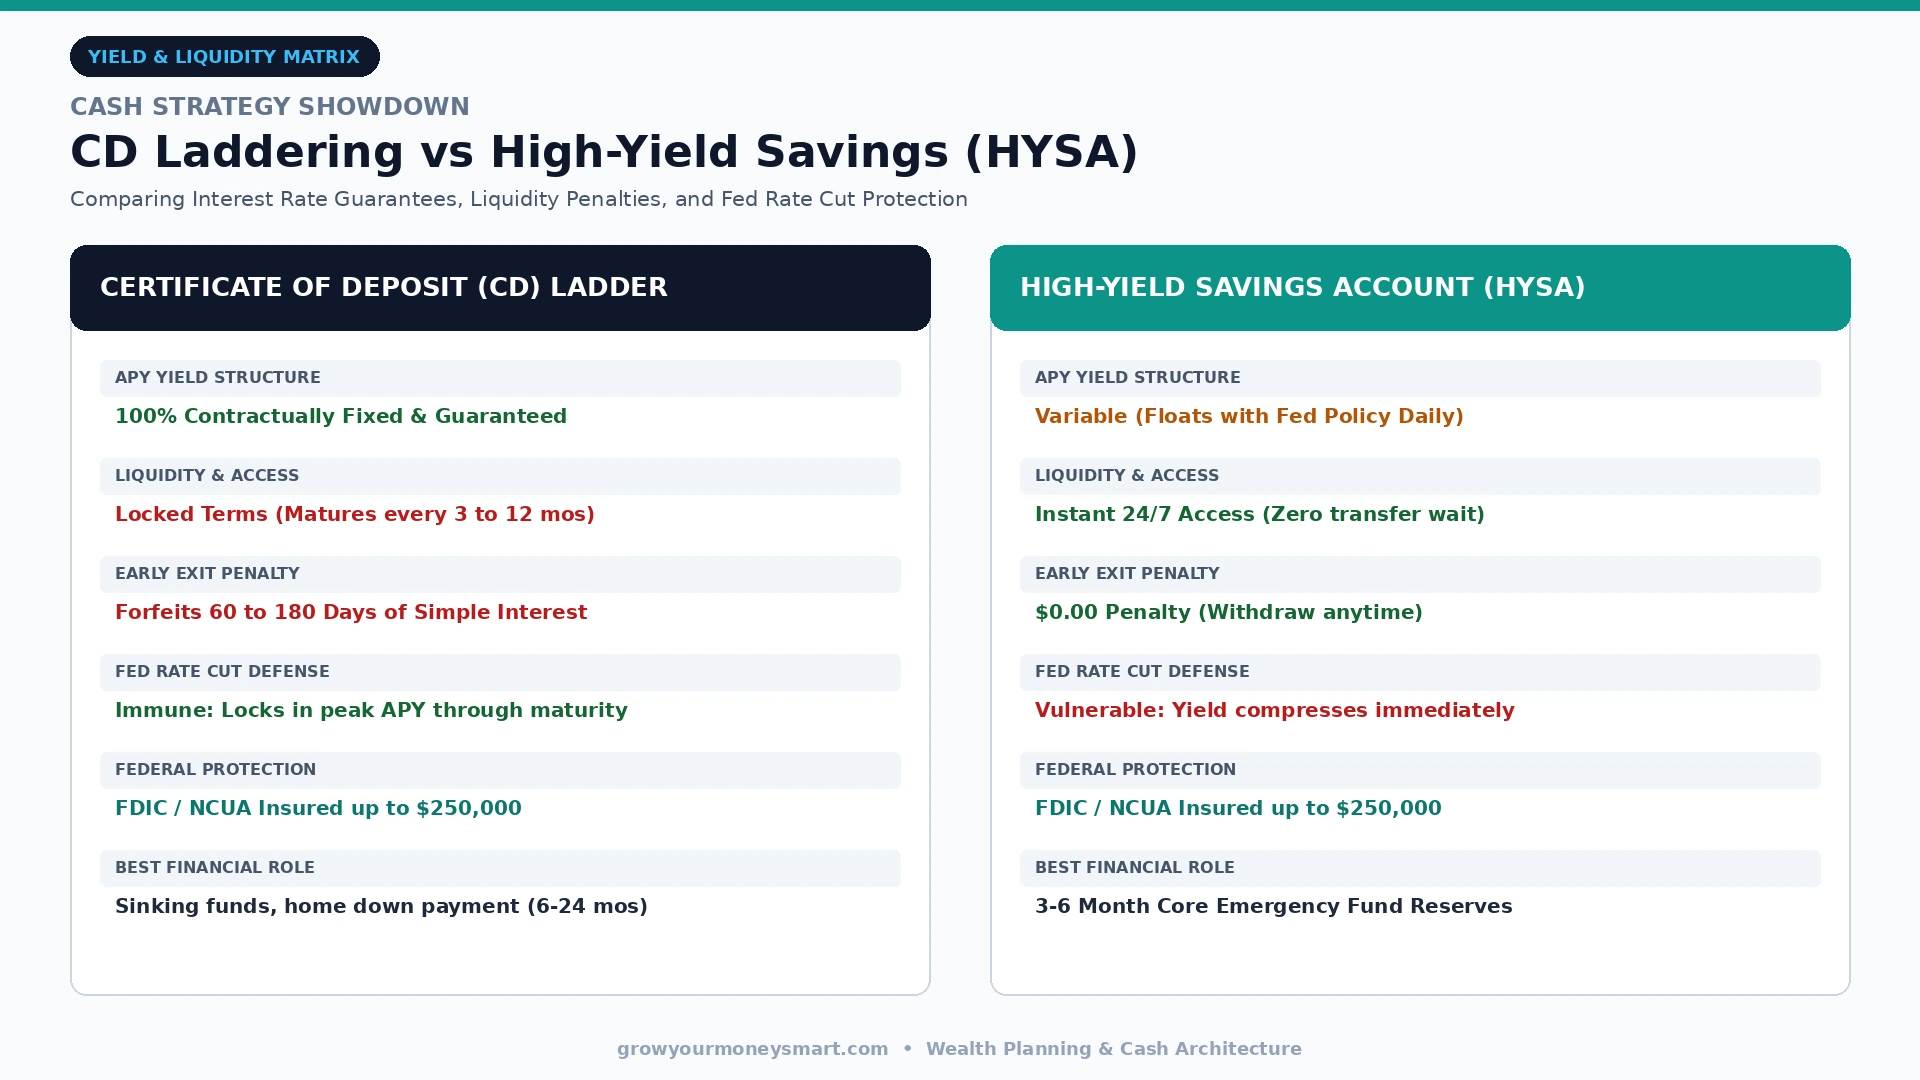
CD Laddering vs HYSA in 2026: Which Earns More Yield?

Comparison matrix of CD laddering vs high-yield savings accounts showing APY yield structure, liquidity access, and early exit penalties.

⚡ [QUICK ANSWER] CD Laddering vs HYSA at a Glance A Certificate of Deposit (CD) ladder locks in fixed APY yields (typically 4.25%–4.75%) across staggered maturities, shielding your interest from Federal Reserve rate cuts in exchange for early withdrawal penalties. A High-Yield Savings Account (HYSA) offers 100% daily liquidity with zero penalties, but features variable … Read more

Debt Consolidation vs Hardship Programs: 2026 Playbook

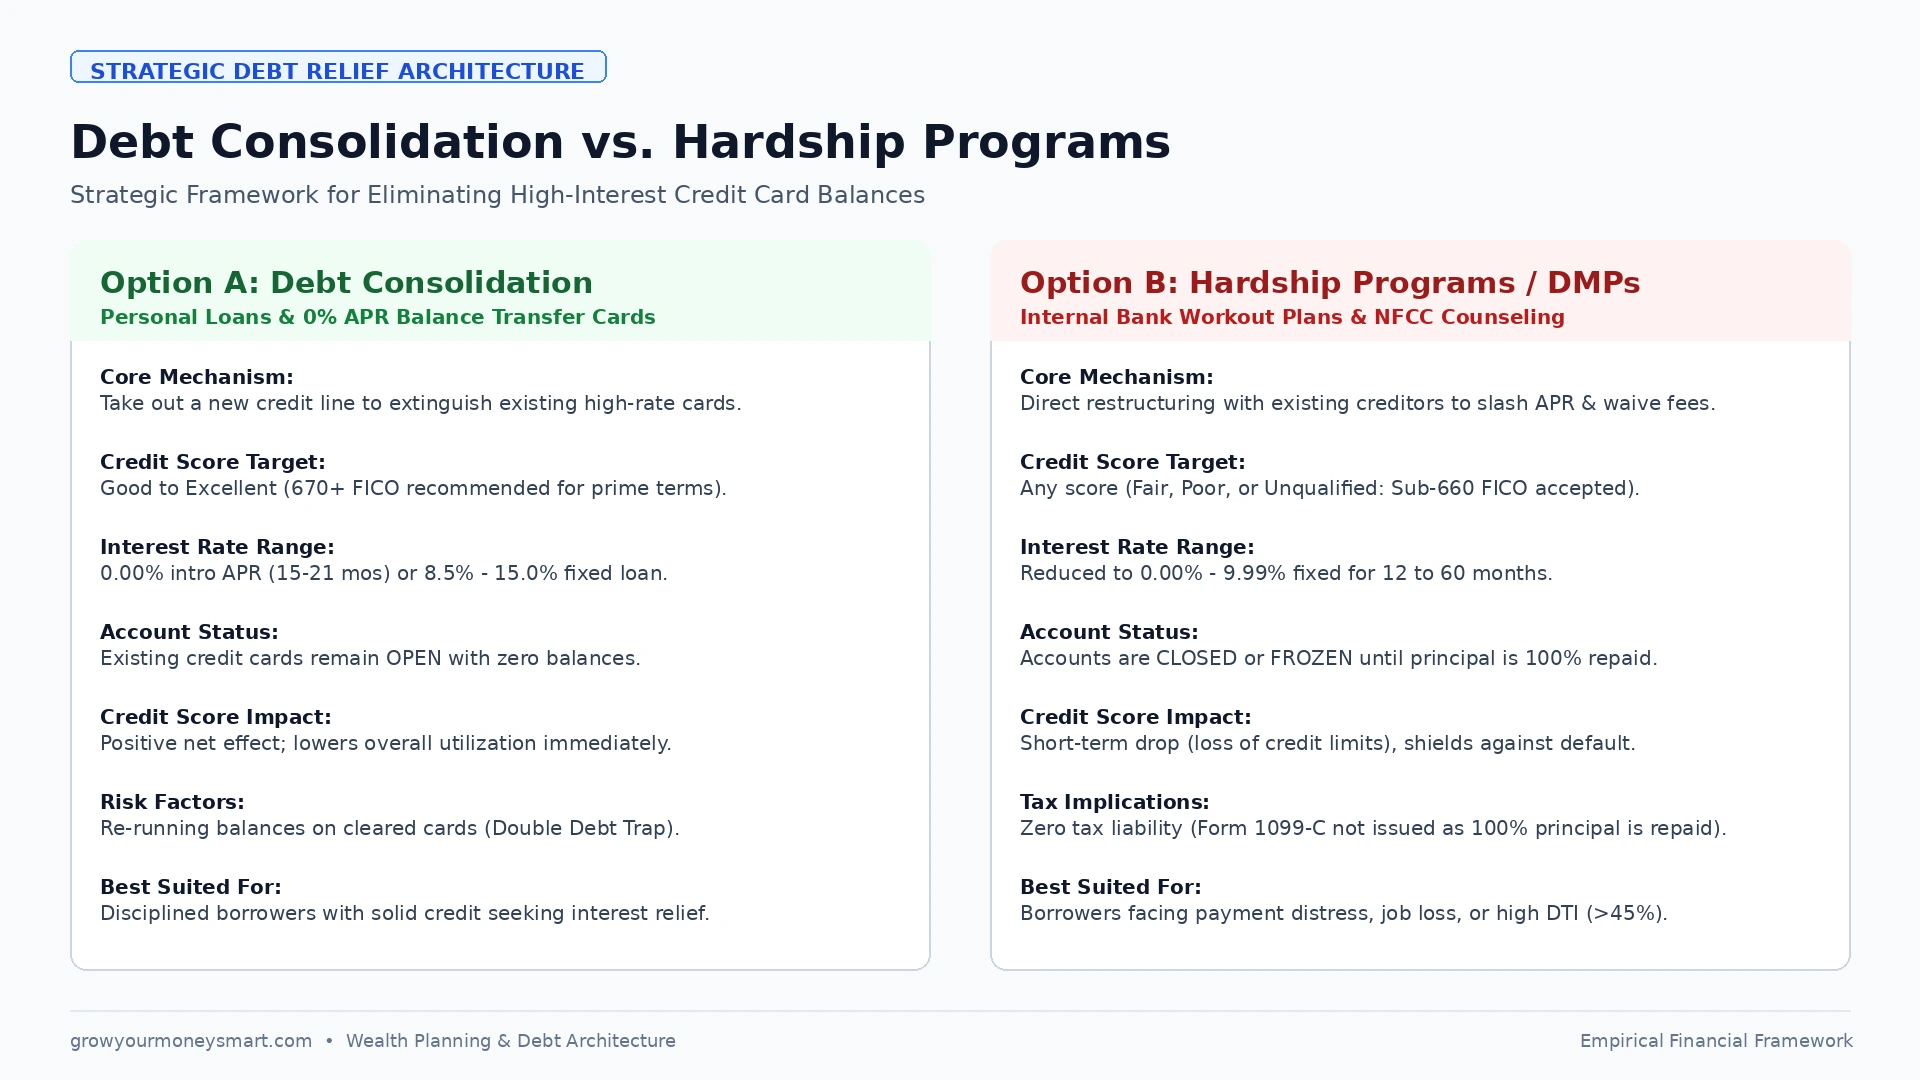
Debt Consolidation vs Hardship Programs comparative decision architecture blueprint

✓ Fact-Checked & Regulatory Aligned | Updated: September 2026 | Authored by Jaiveer Hooda | Review: Financial Planning & Debt Desk Empirical Modeling • CFPB & Federal Reserve Data Standards ⚡ [QUICK ANSWER] Debt Consolidation vs Hardship Programs at a Glance In the debate of debt consolidation vs hardship programs, debt consolidation combines multiple balances … Read more

The 5.0% HYSA Window Is Closing: Where to Park Your Cash Right Now

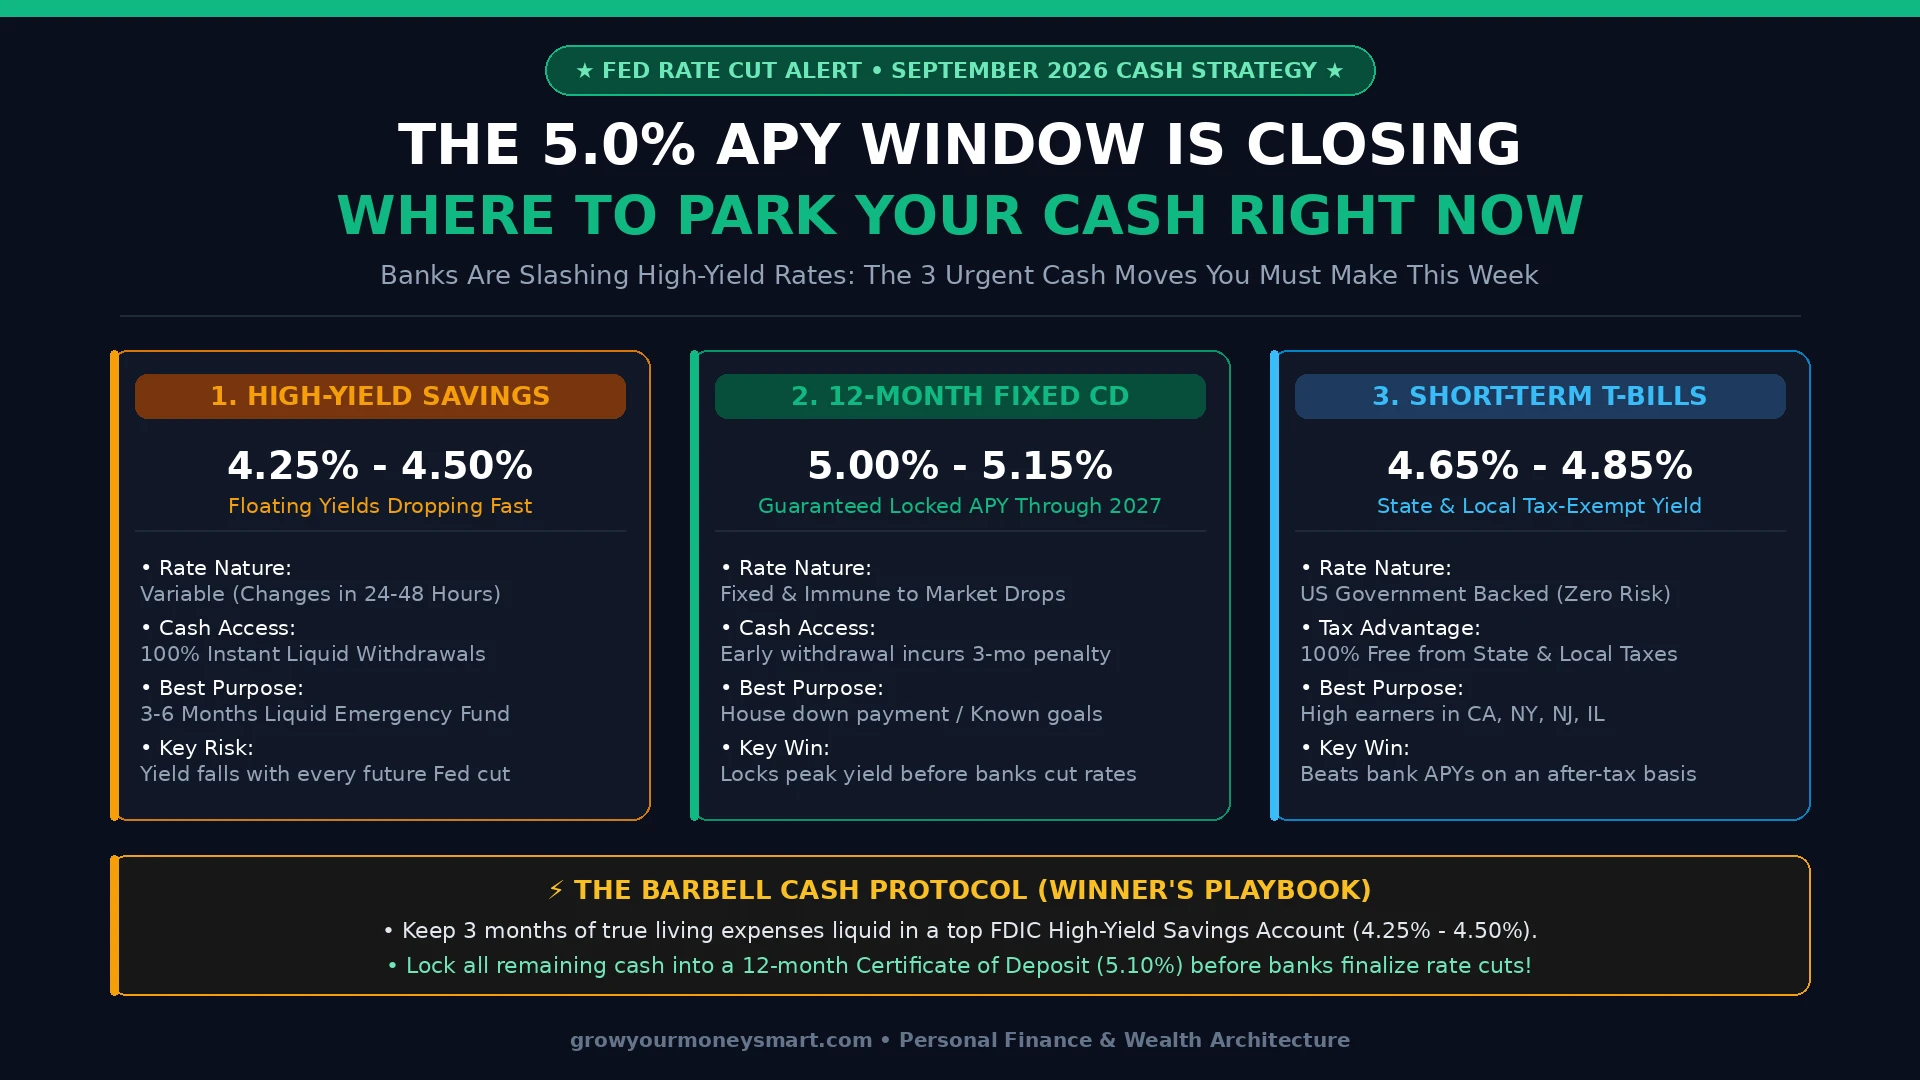
Infographic comparing high-yield savings accounts, fixed certificates of deposit, and Treasury bills following the Federal Reserve interest rate cut

The Federal Reserve’s long-anticipated interest rate decision has finally dropped, and if you have cash parked in an online savings account, the clock is officially ticking. Over the past two years, savers enjoyed an unprecedented golden era of risk-free yields hovering comfortably between 5.00% and 5.50% APY. But with the Fed executing a aggressive 50-basis-point … Read more

Sandwich Generation Financial Planning Guide (2026)

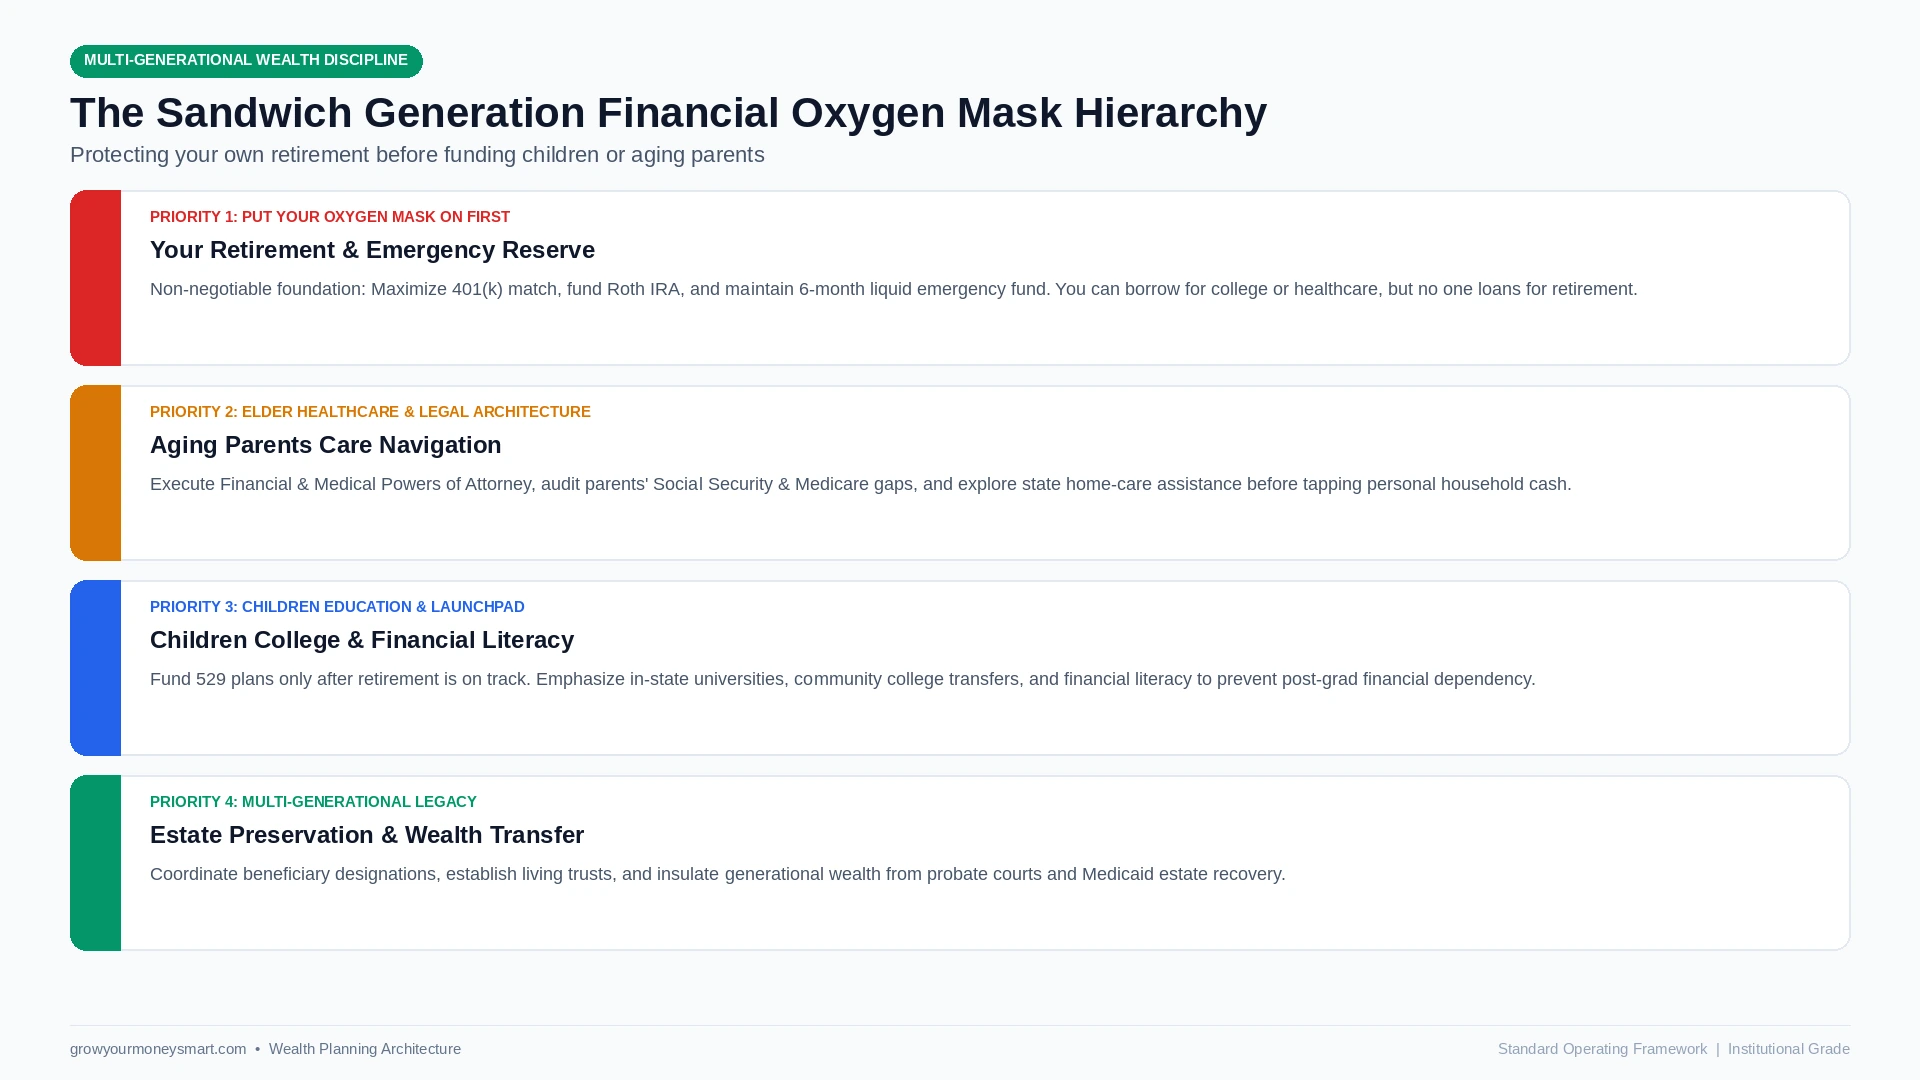
sandwich generation financial planning oxygen mask hierarchy diagram

[QUICK ANSWER] Sandwich Generation Financial Planning at a Glance Successful sandwich generation financial planning follows the Oxygen Mask Principle: Secure your own retirement savings (401k match and Roth IRA) and a 6-month emergency reserve before funding children’s college or subsidizing aging parents’ medical care. Because students can access college grants, loans, and scholarships while seniors … Read more

Is Long-Term Care Insurance Worth It in 2026? Guide

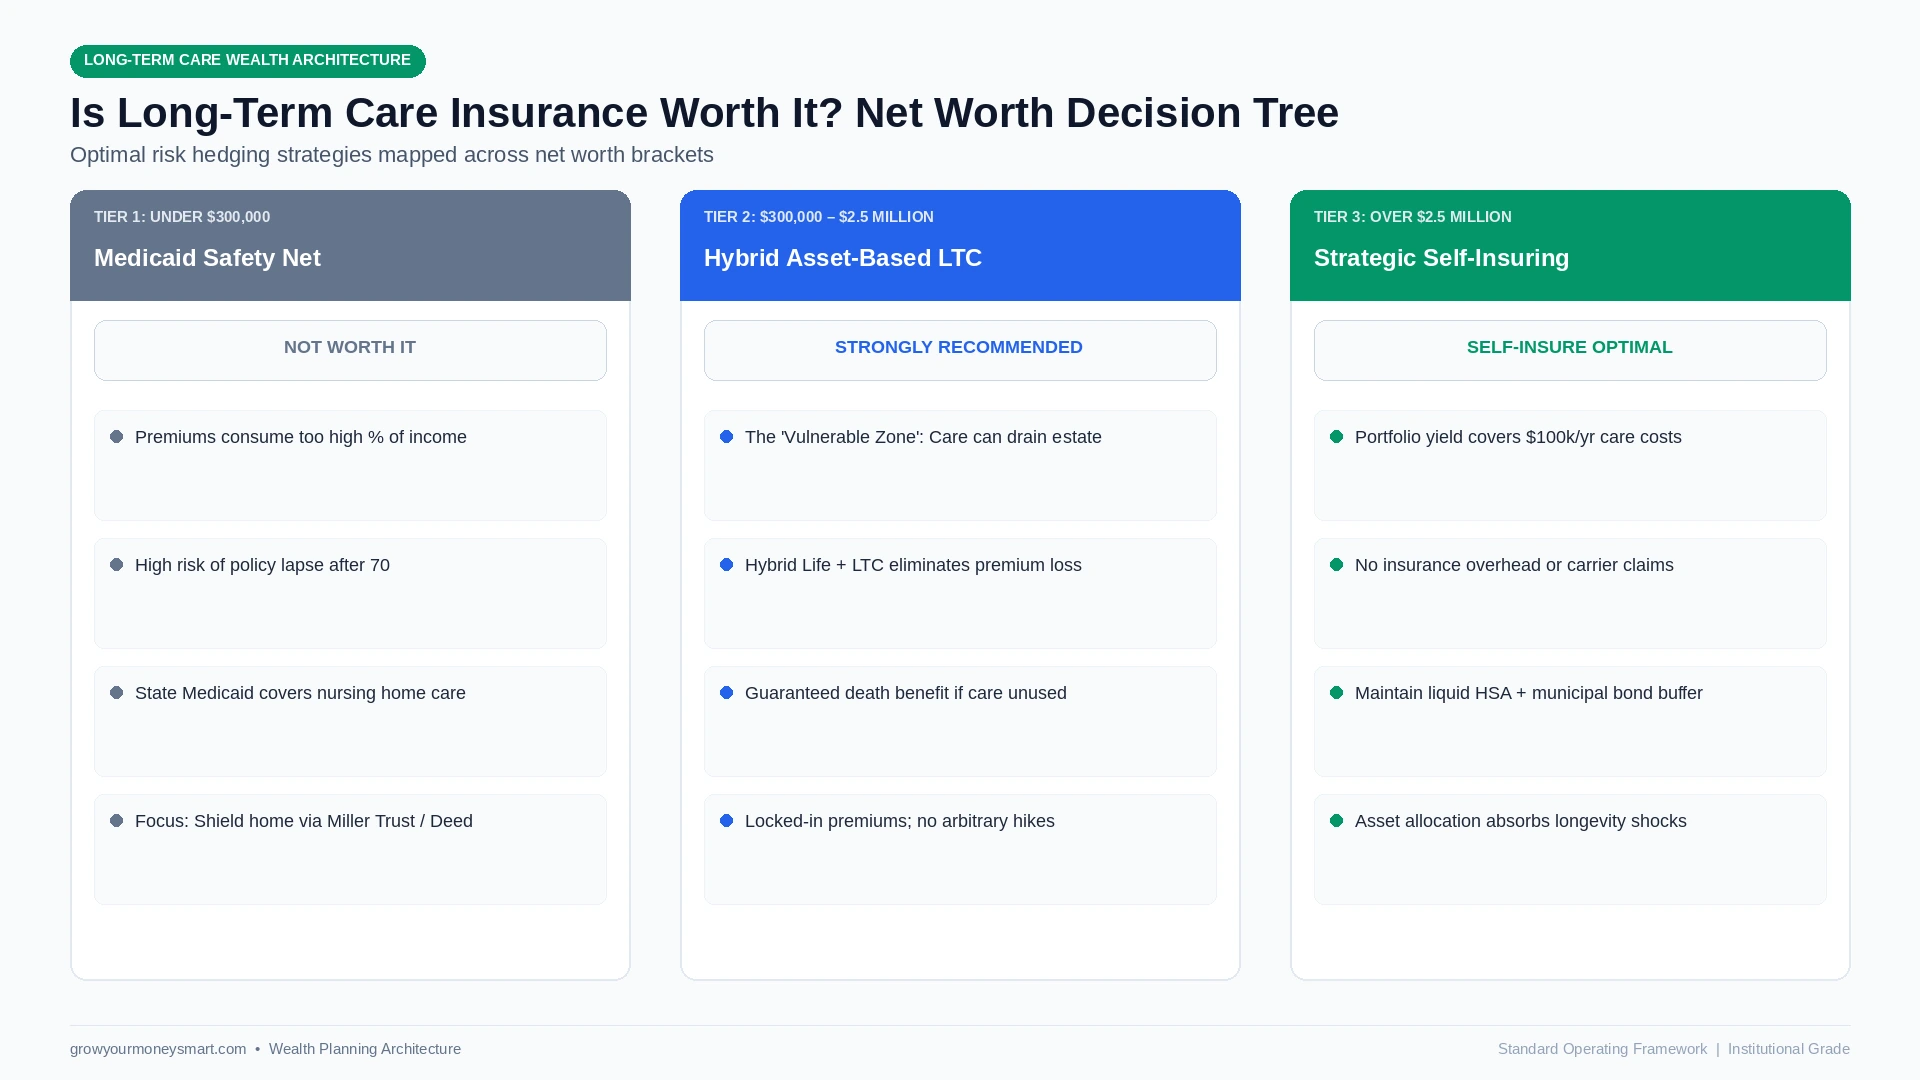
is long term care insurance worth it decision tree mapped by household net worth

[QUICK ANSWER] Is Long-Term Care Insurance Worth It in 2026? Deciding whether is long term care insurance worth it depends strictly on your household net worth: It is generally not worth it for individuals with under $300,000 in assets (who qualify for Medicaid) or over $2.5 million (who can self-insure via portfolio yield). However, for … Read more

Beneficiary Designation vs Will: Costly Traps (2026)

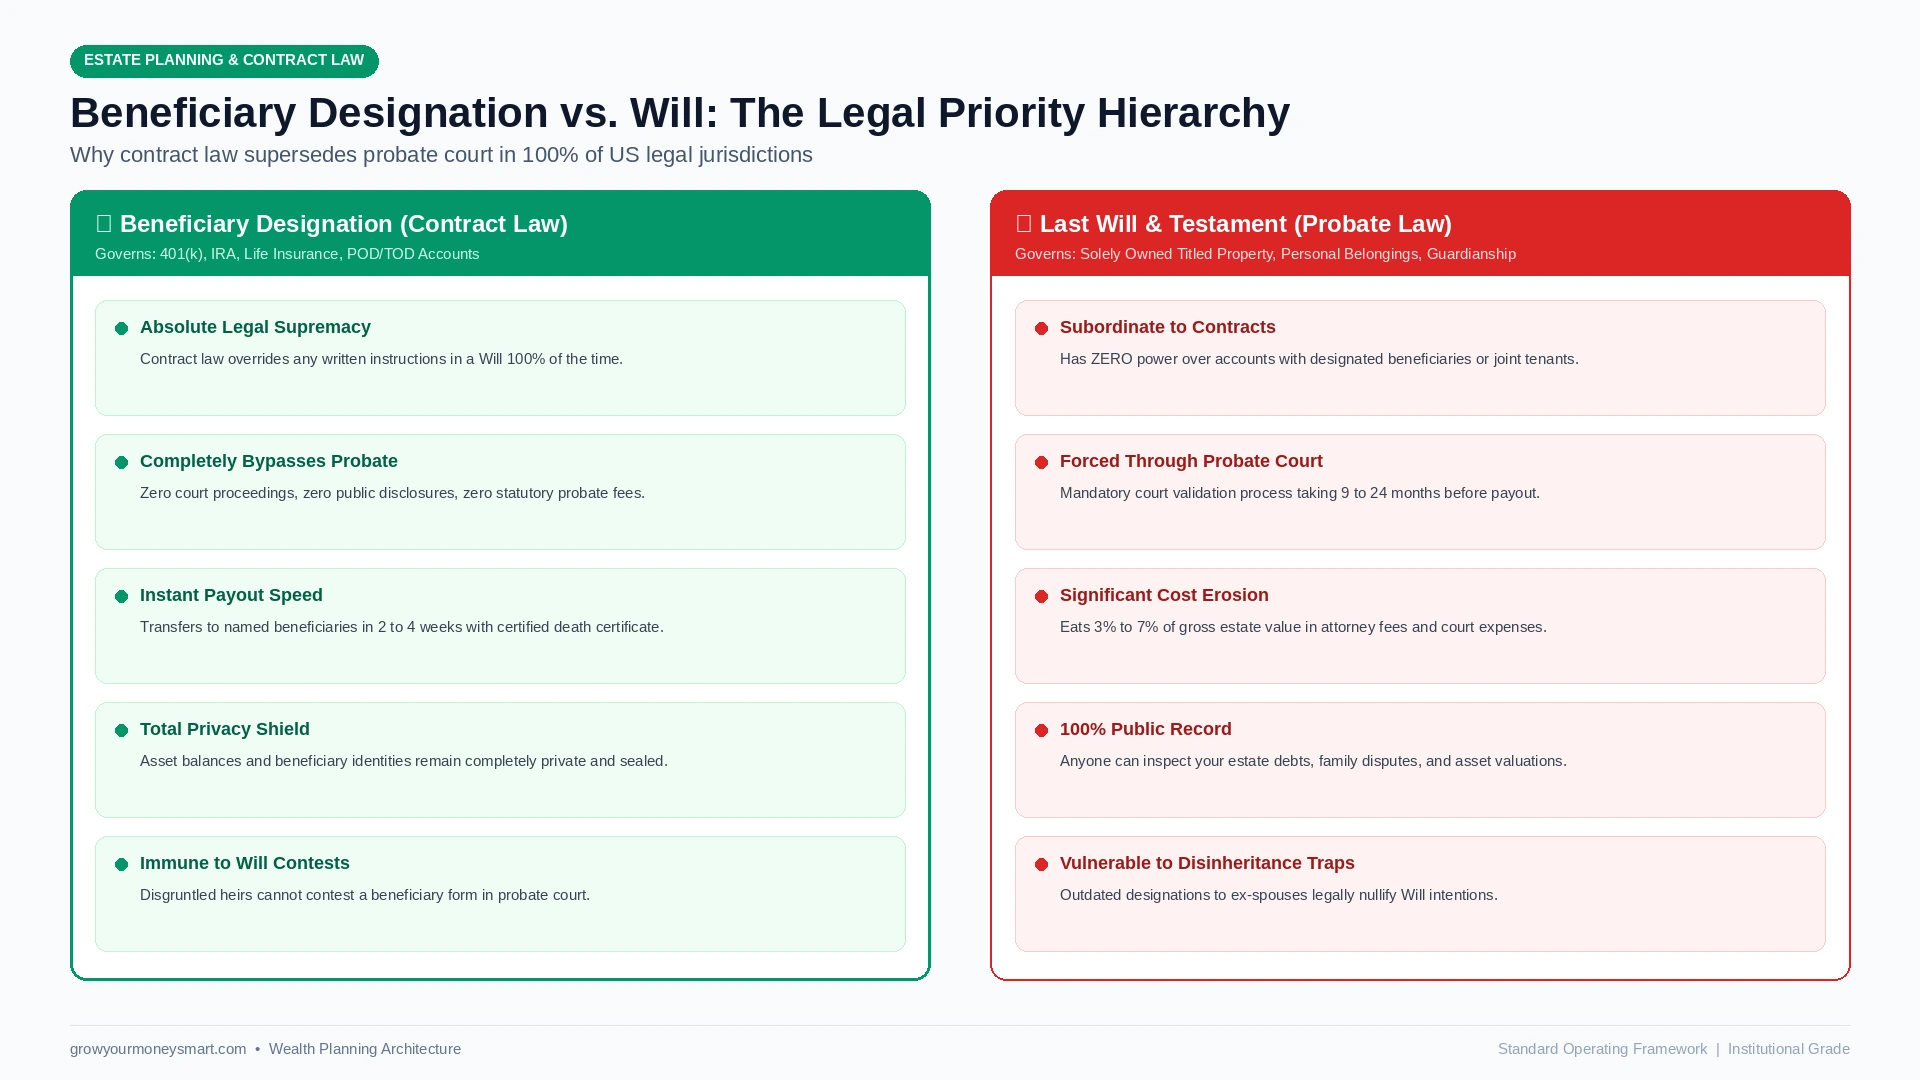
beneficiary designation vs will legal priority hierarchy diagram

[QUICK ANSWER] Beneficiary Designation vs Will at a Glance In the legal conflict of beneficiary designation vs will, beneficiary designations legally supersede a Last Will and Testament in 100% of US probate jurisdictions. Because accounts like 401(k)s, IRAs, life insurance, and Payable-on-Death (POD) bank accounts pass via contractual law, they transfer directly to named beneficiaries … Read more

Free Monthly Budget Spreadsheet: Net Worth Tracker (2026)

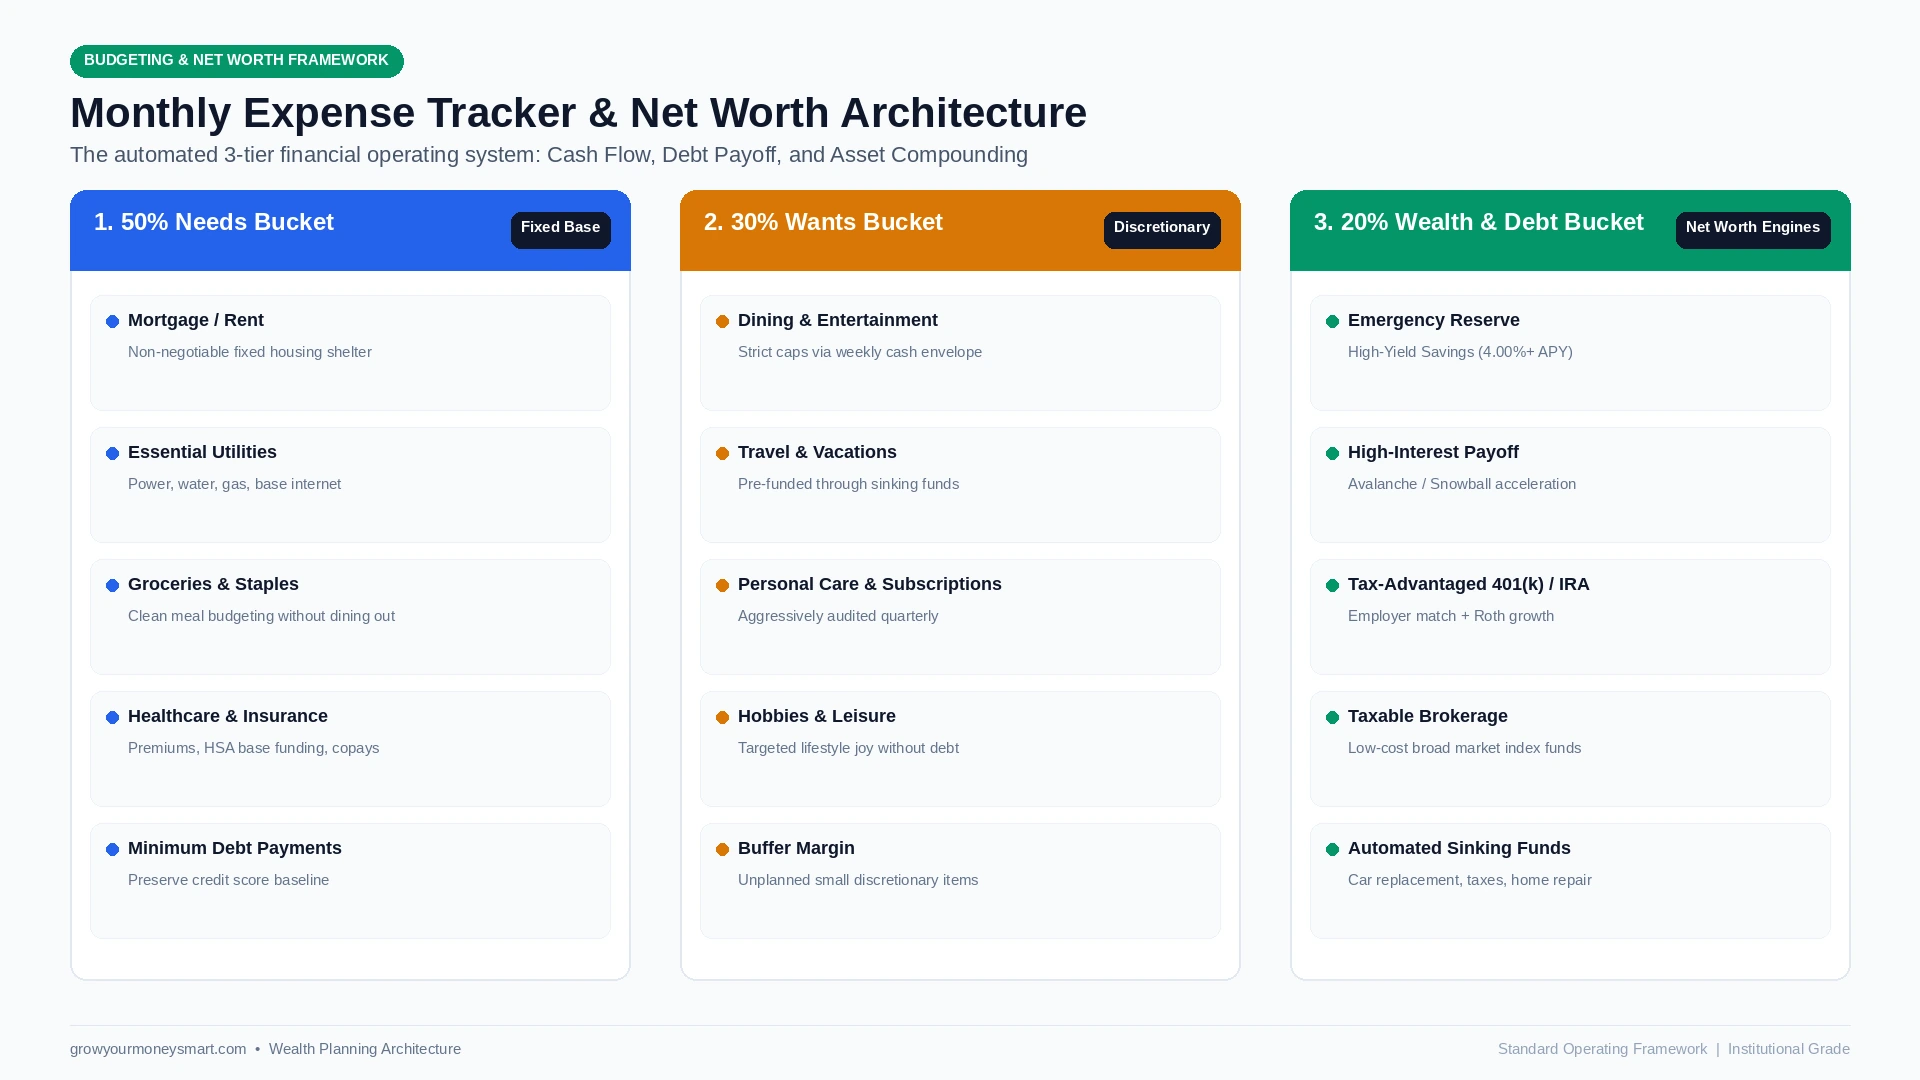
free monthly budget spreadsheet and net worth tracking architecture

[QUICK ANSWER] Free Monthly Budget Spreadsheet at a Glance A free monthly budget spreadsheet combines automated cash-flow tracking with a synchronized net worth balance sheet. By categorizing income into a 50/30/20 framework (Needs, Wants, Wealth) and logging liquid assets versus liabilities on the 1st of every month, it eliminates hidden subscription leaks and visualizes debt … Read more

Receive the latest articles in your inbox

Join smart readers getting actionable personal finance tips, debt payoff blueprints, and retirement guides directly to their inbox.

⚖️ Important Financial Disclaimer & Educational Notice

The articles, calculators, debt payoff strategies, and financial tools on Grow Your Money Smart are provided strictly for general educational, illustrative, and informational purposes. Content published on this website does not constitute tailored financial, investment, tax, or legal advice.

Financial markets, interest rates, and personal financial circumstances vary significantly. You should evaluate your unique financial situation or consult a licensed Fiduciary, Certified Financial Planner (CFP®), or certified tax professional before making any significant financial decisions.

×