Sandwich Generation Financial Planning Guide (2026)
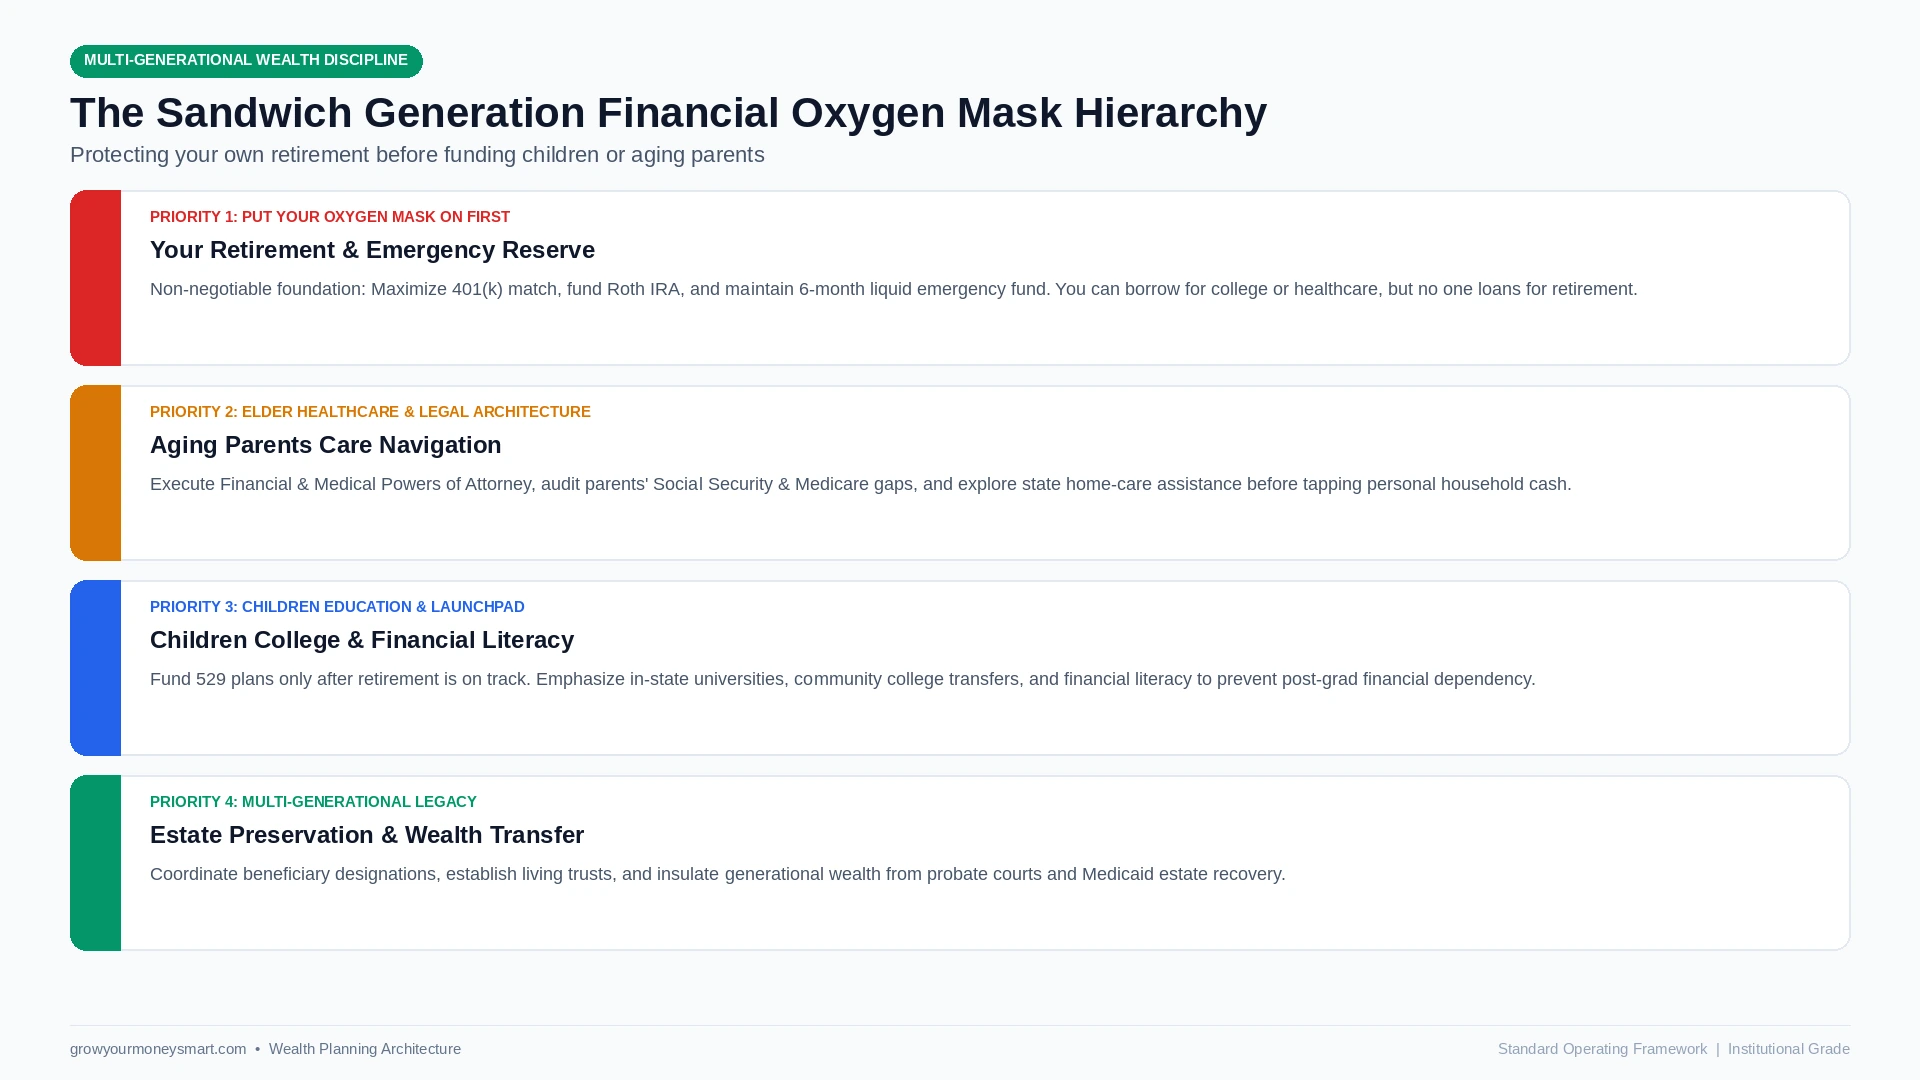
sandwich generation financial planning oxygen mask hierarchy diagram

[QUICK ANSWER] Sandwich Generation Financial Planning at a Glance Successful sandwich generation financial planning follows the Oxygen Mask Principle: Secure your own retirement savings (401k match and Roth IRA) and a 6-month emergency reserve before funding children’s college or subsidizing aging parents’ medical care. Because students can access college grants, loans, and scholarships while seniors … Read more
Is Long-Term Care Insurance Worth It in 2026? Guide

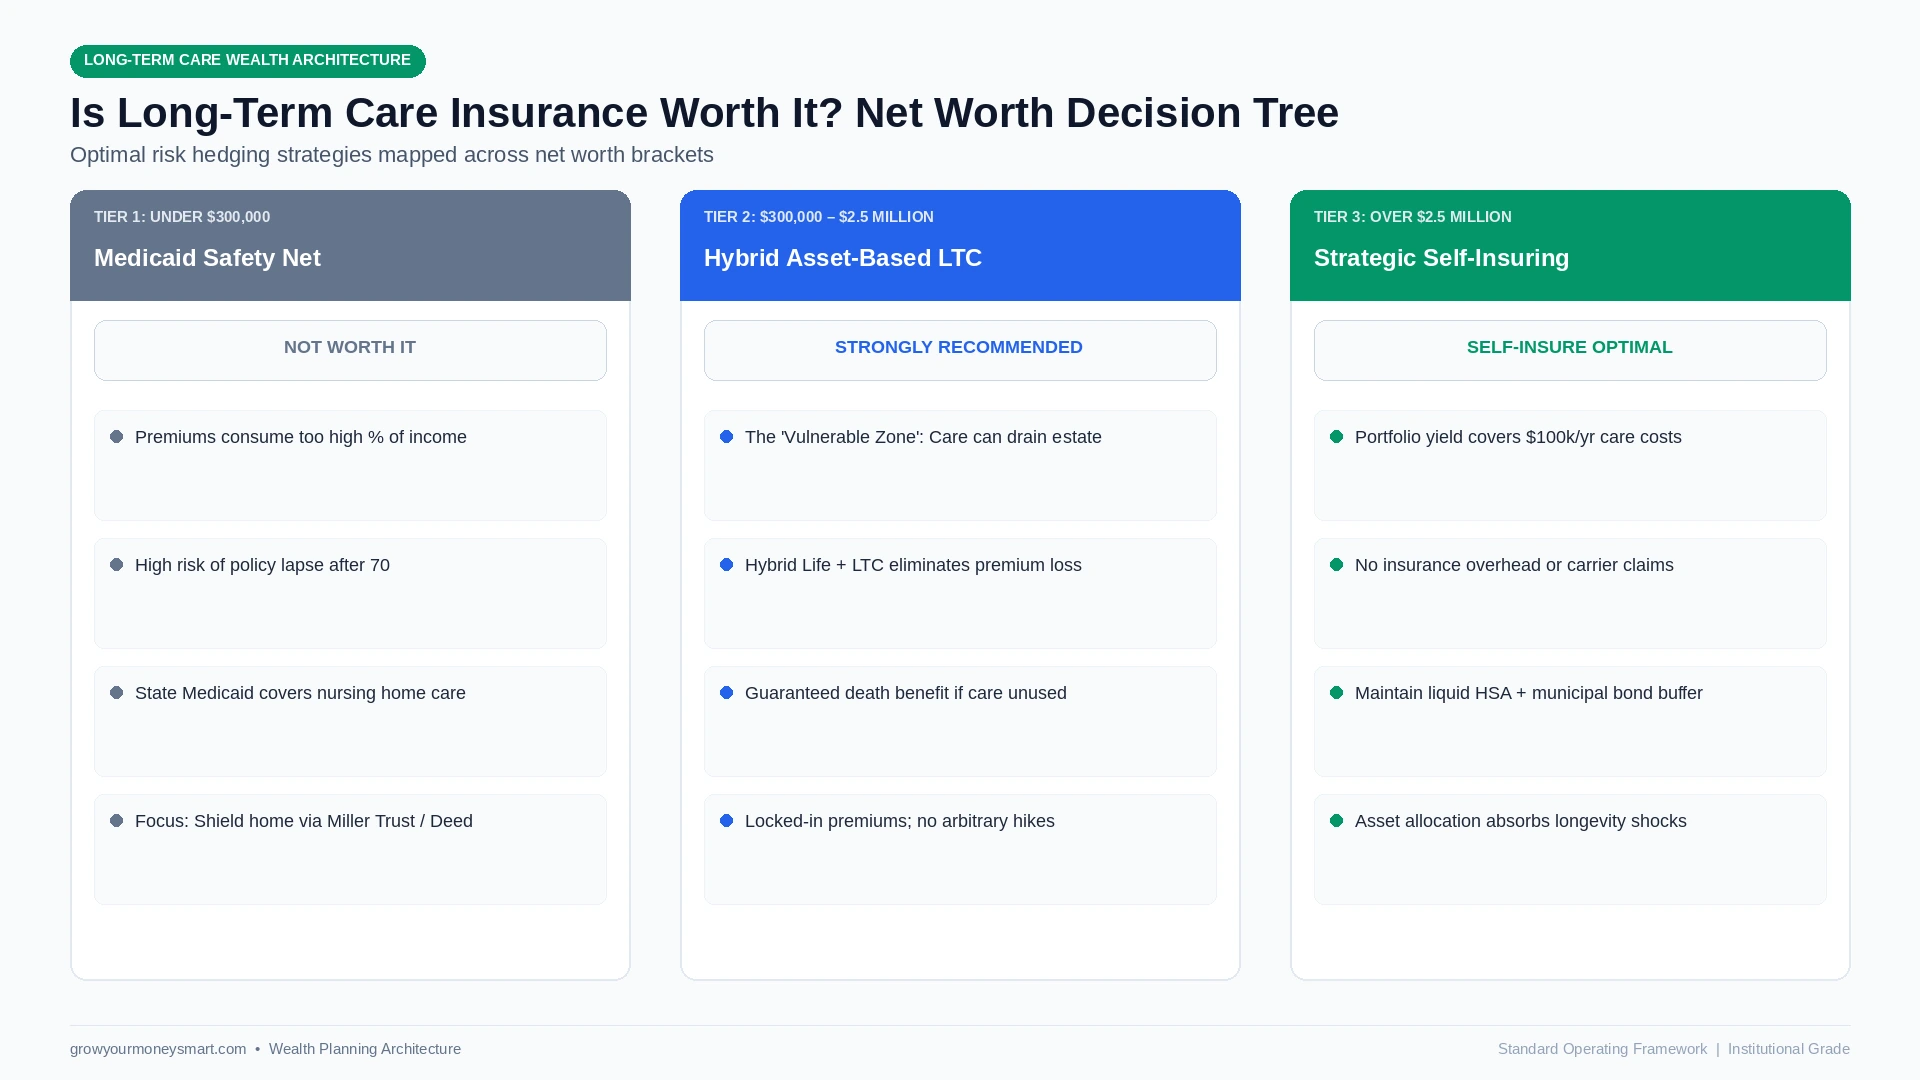
is long term care insurance worth it decision tree mapped by household net worth

[QUICK ANSWER] Is Long-Term Care Insurance Worth It in 2026? Deciding whether is long term care insurance worth it depends strictly on your household net worth: It is generally not worth it for individuals with under $300,000 in assets (who qualify for Medicaid) or over $2.5 million (who can self-insure via portfolio yield). However, for … Read more

Beneficiary Designation vs Will: Costly Traps (2026)

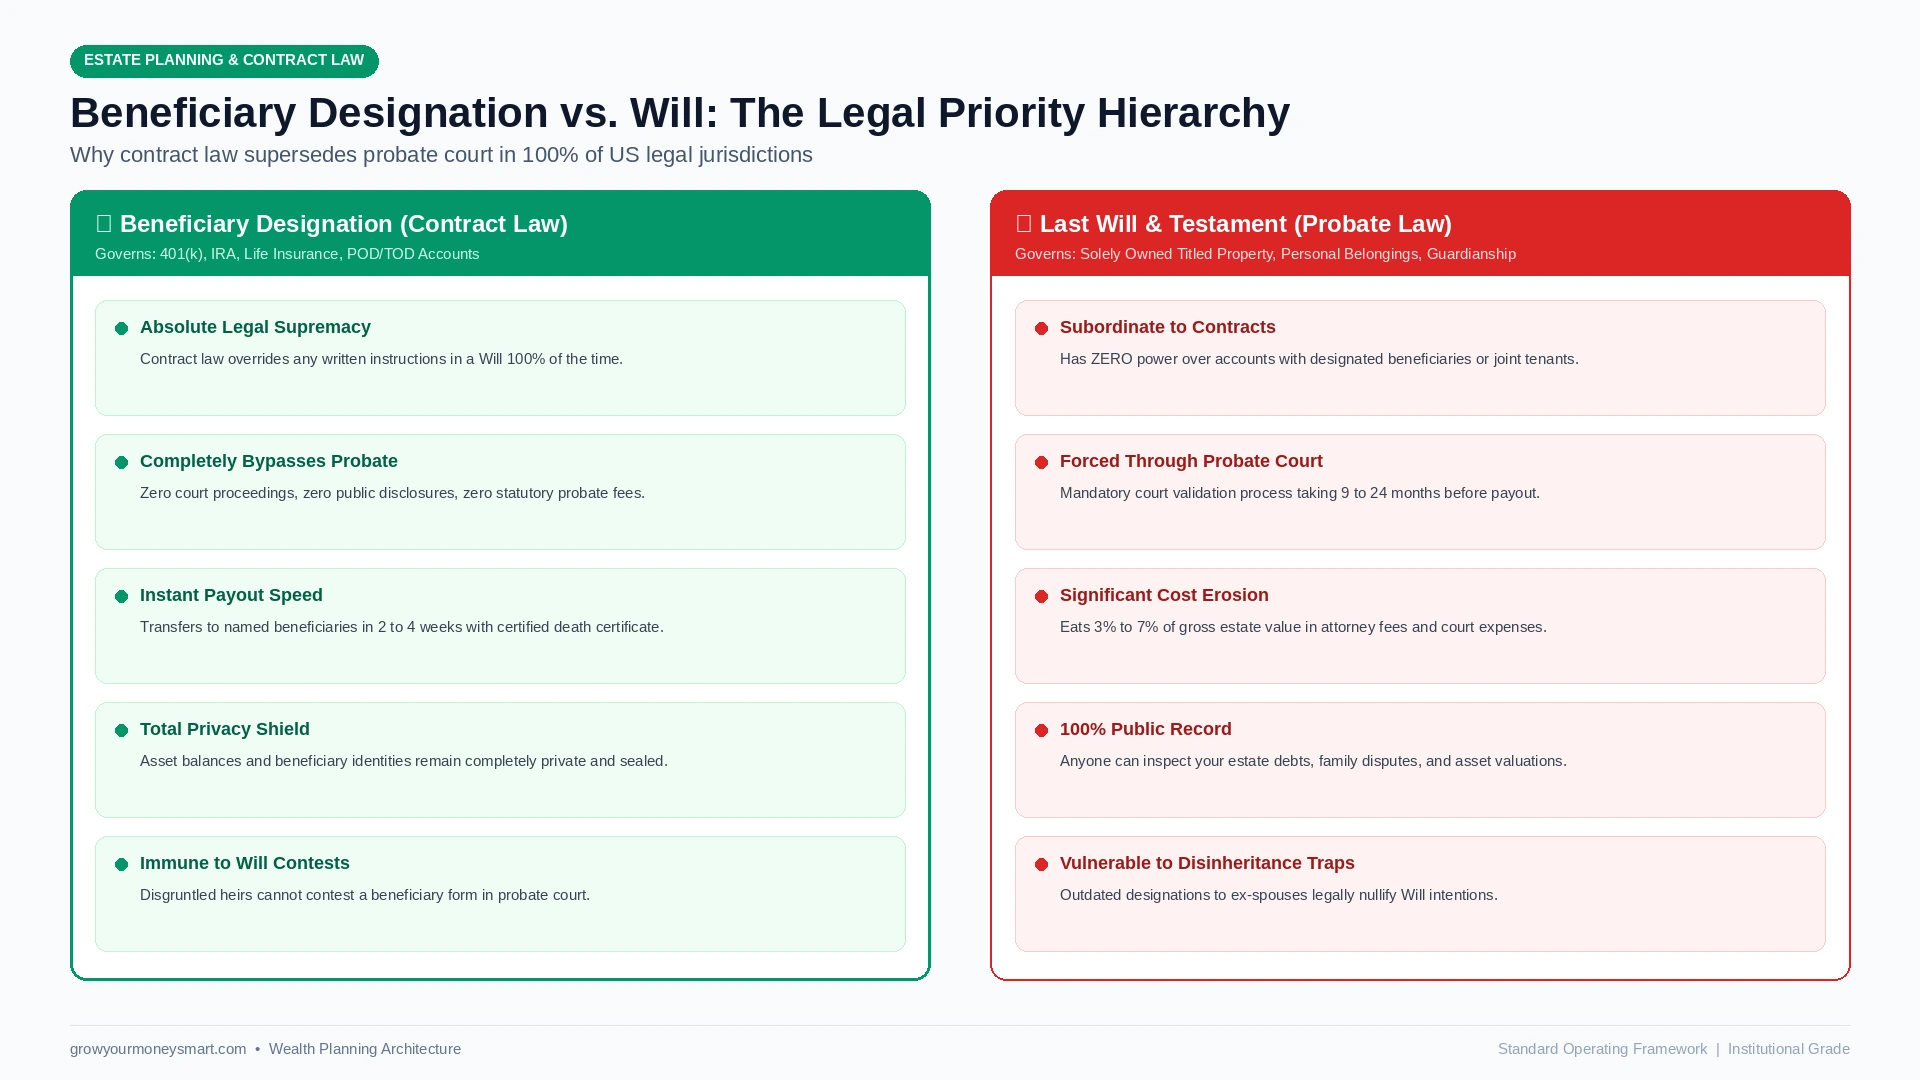
beneficiary designation vs will legal priority hierarchy diagram

[QUICK ANSWER] Beneficiary Designation vs Will at a Glance In the legal conflict of beneficiary designation vs will, beneficiary designations legally supersede a Last Will and Testament in 100% of US probate jurisdictions. Because accounts like 401(k)s, IRAs, life insurance, and Payable-on-Death (POD) bank accounts pass via contractual law, they transfer directly to named beneficiaries … Read more

How to Rollover a 401(k) to an IRA Without Taxes (2026)

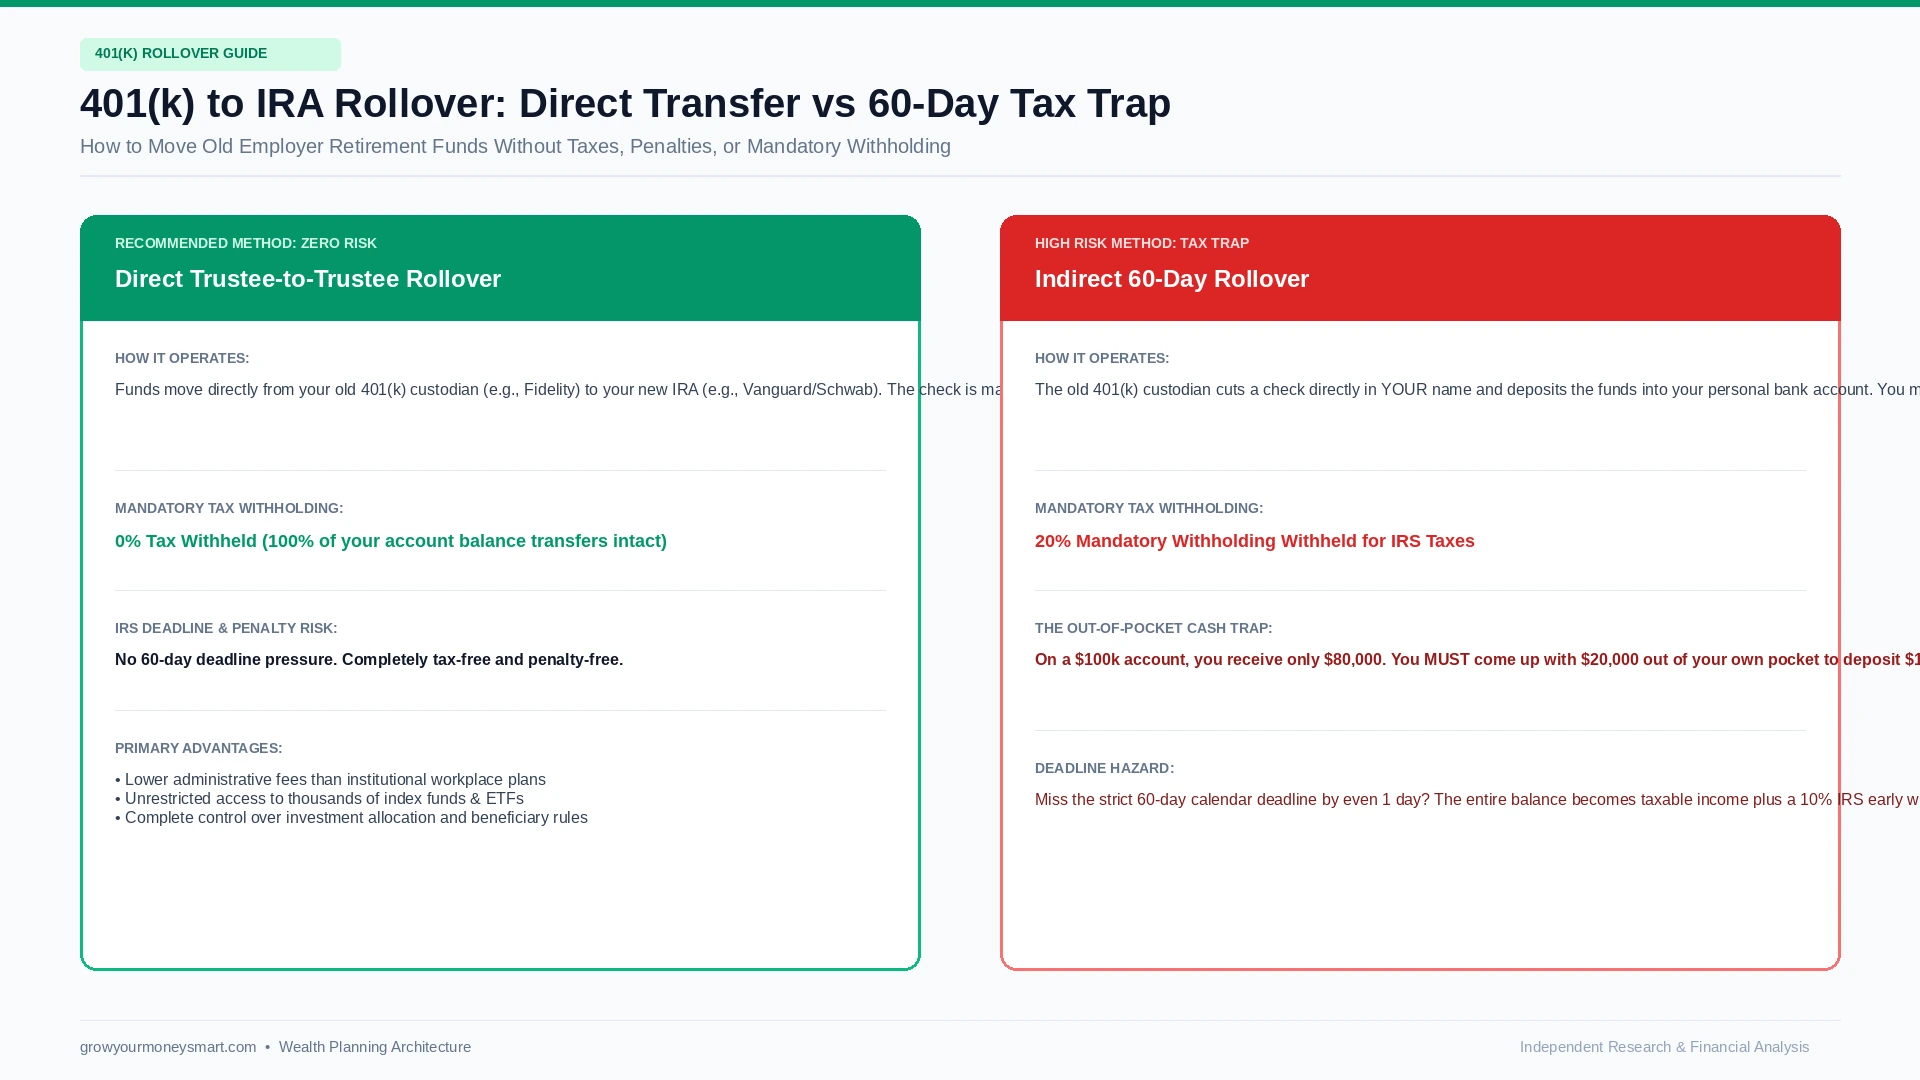
401k rollover to IRA comparison diagram highlighting direct rollover vs indirect 60 day rollover tax trap

[QUICK ANSWER] How to Rollover a 401(k) to an IRA at a Glance To Rollover a 401(k) to an IRA without triggering income taxes or early withdrawal penalties, you must execute a Direct Trustee-to-Trustee Rollover. In a direct rollover, your former 401(k) custodian transfers funds directly to your new IRA custodian (or issues a check … Read more

HSA Triple Tax Advantage: Stealth Retirement Account

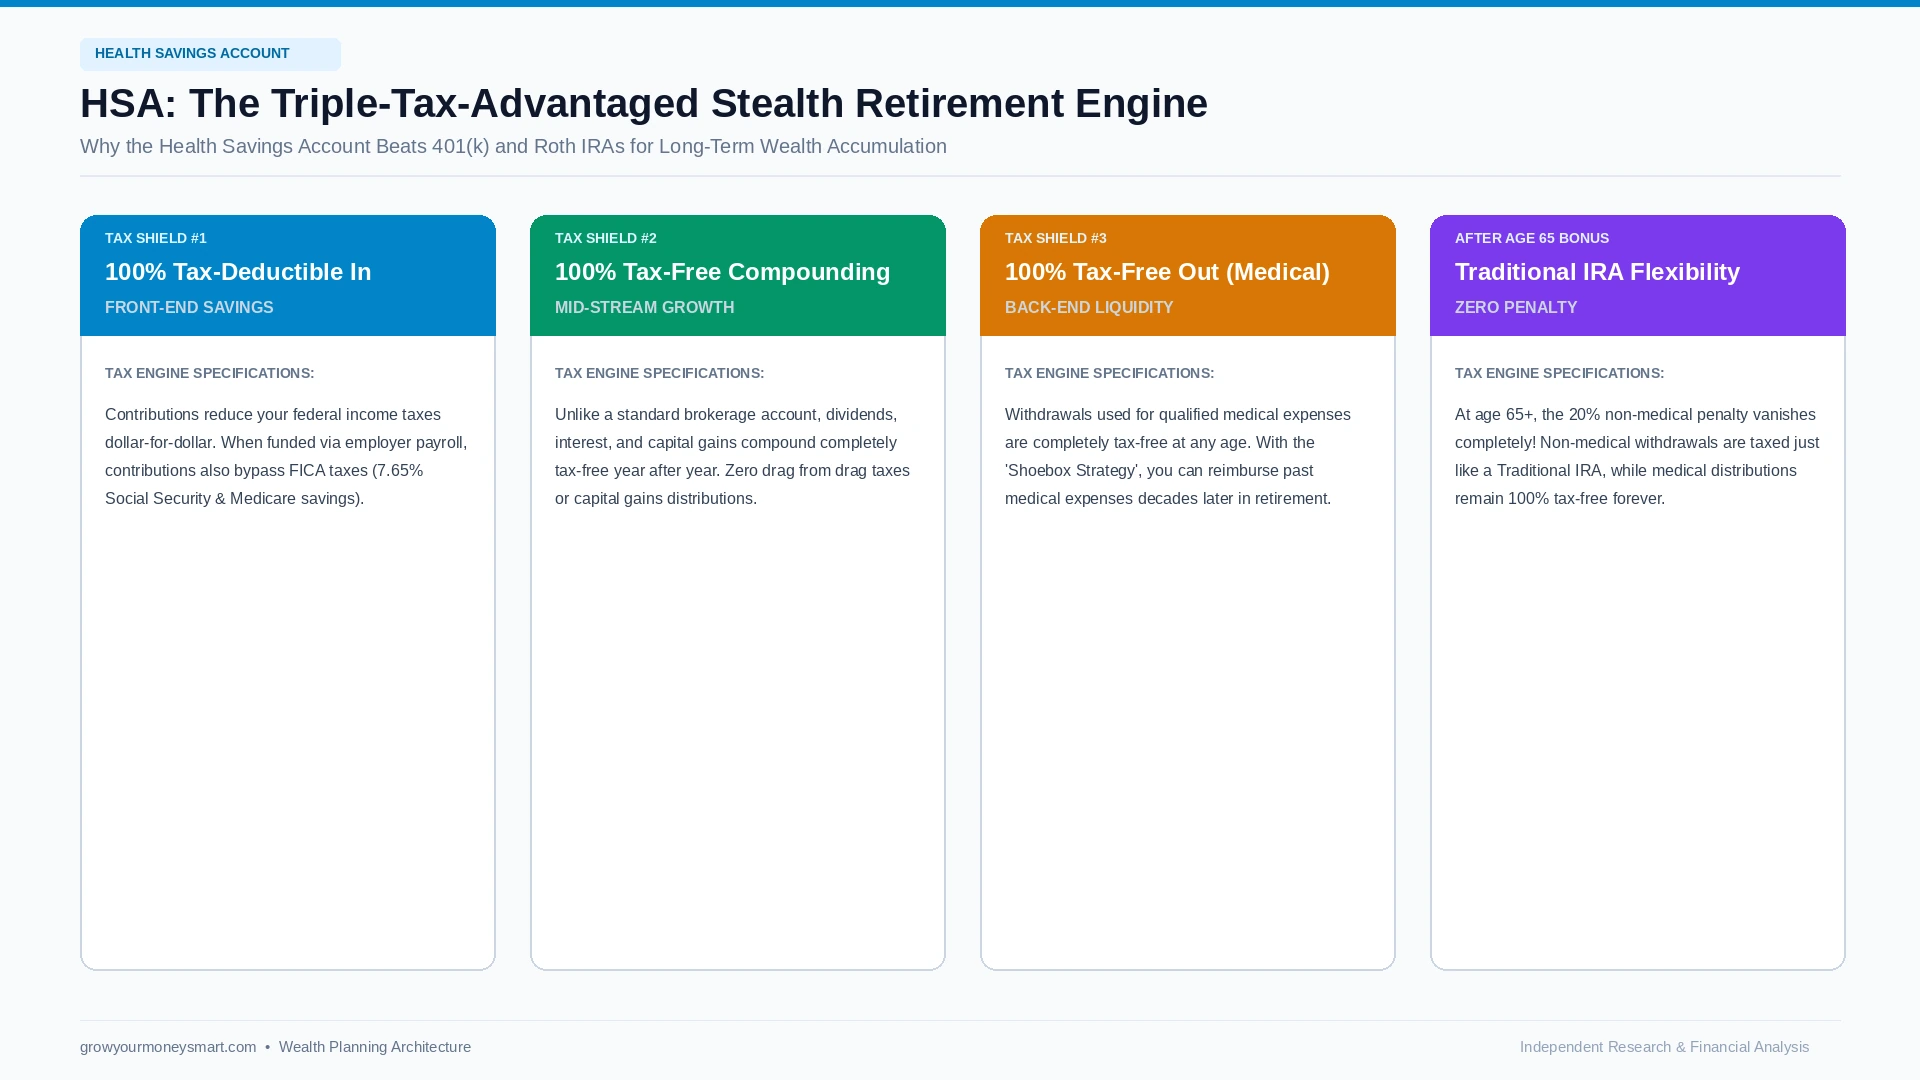
HSA as retirement account infographic explaining the triple tax advantage and shoebox reimbursement strategy

[QUICK ANSWER] The HSA Stealth Retirement Engine at a Glance The HSA Triple Tax Advantage operates as the single most tax-efficient retirement vehicle in the United States: contributions are 100% tax-deductible (and bypass 7.65% FICA payroll taxes), investment earnings compound completely tax-free, and distributions for qualified medical expenses are 100% tax-free at any age. In … Read more

Backdoor Roth IRA: Step-by-Step Guide for High Earners

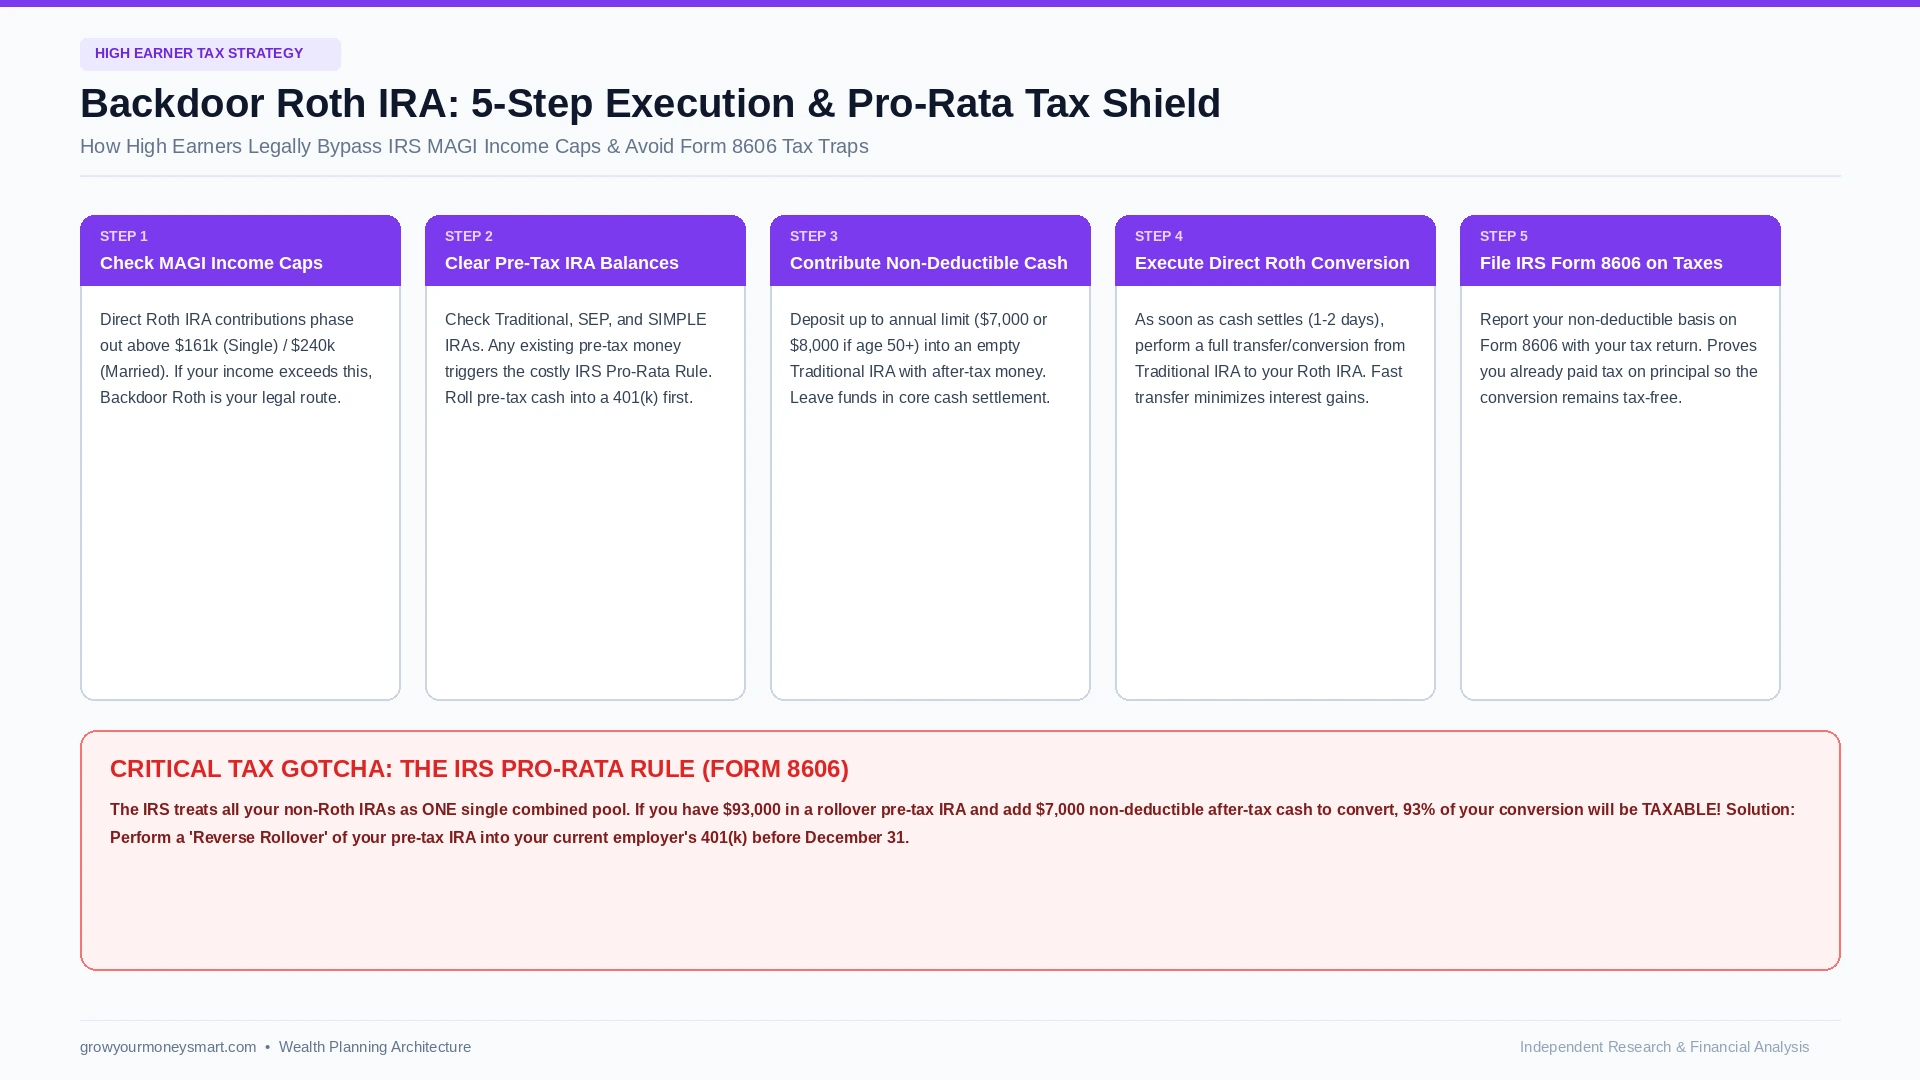
Backdoor Roth IRA guide workflow diagram showing non deductible contribution conversion and pro rata rule prevention

[QUICK ANSWER] Backdoor Roth IRA Strategy at a Glance A Backdoor Roth IRA is an IRS-sanctioned two-step wealth strategy allowing high earners exceeding annual income limits ($161,000 for single filers and $240,000 for married filing jointly in 2026) to legally fund a Roth IRA. By making a non-deductible contribution to an empty Traditional IRA and … Read more

The 4% Rule Explained: Safe Withdrawal Rate in 2026

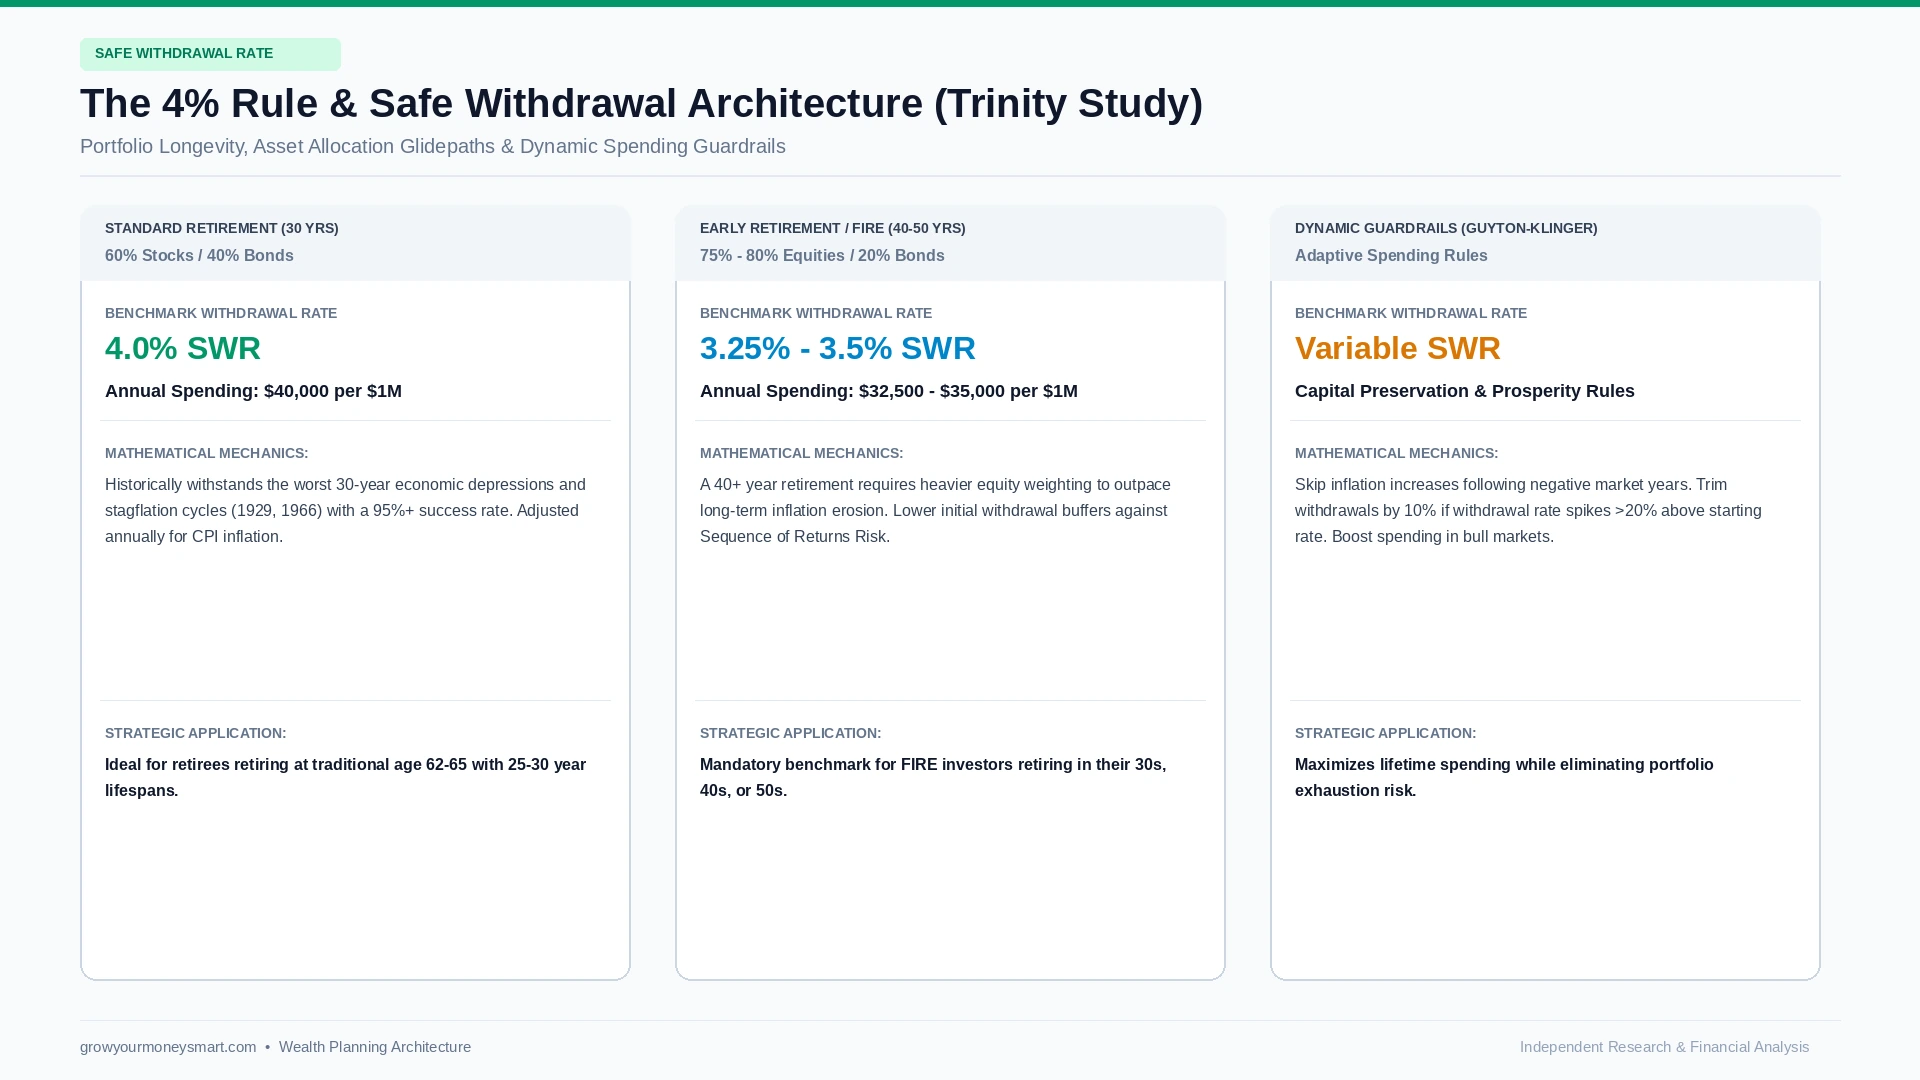
The 4 percent rule retirement safe withdrawal rate chart comparing 30 year standard retirement and early retirement FIRE portfolios

[QUICK ANSWER] The 4% Rule & Safe Withdrawal Rate at a Glance The 4% Rule states that a retiree can safely withdraw 4% of their total invested portfolio during their first year of retirement, adjusting subsequent annual withdrawals for inflation, with a 95%+ historical probability that the nest egg will survive at least 30 years … Read more

What to Do After Maxing Out 401k and Roth IRA (2026)

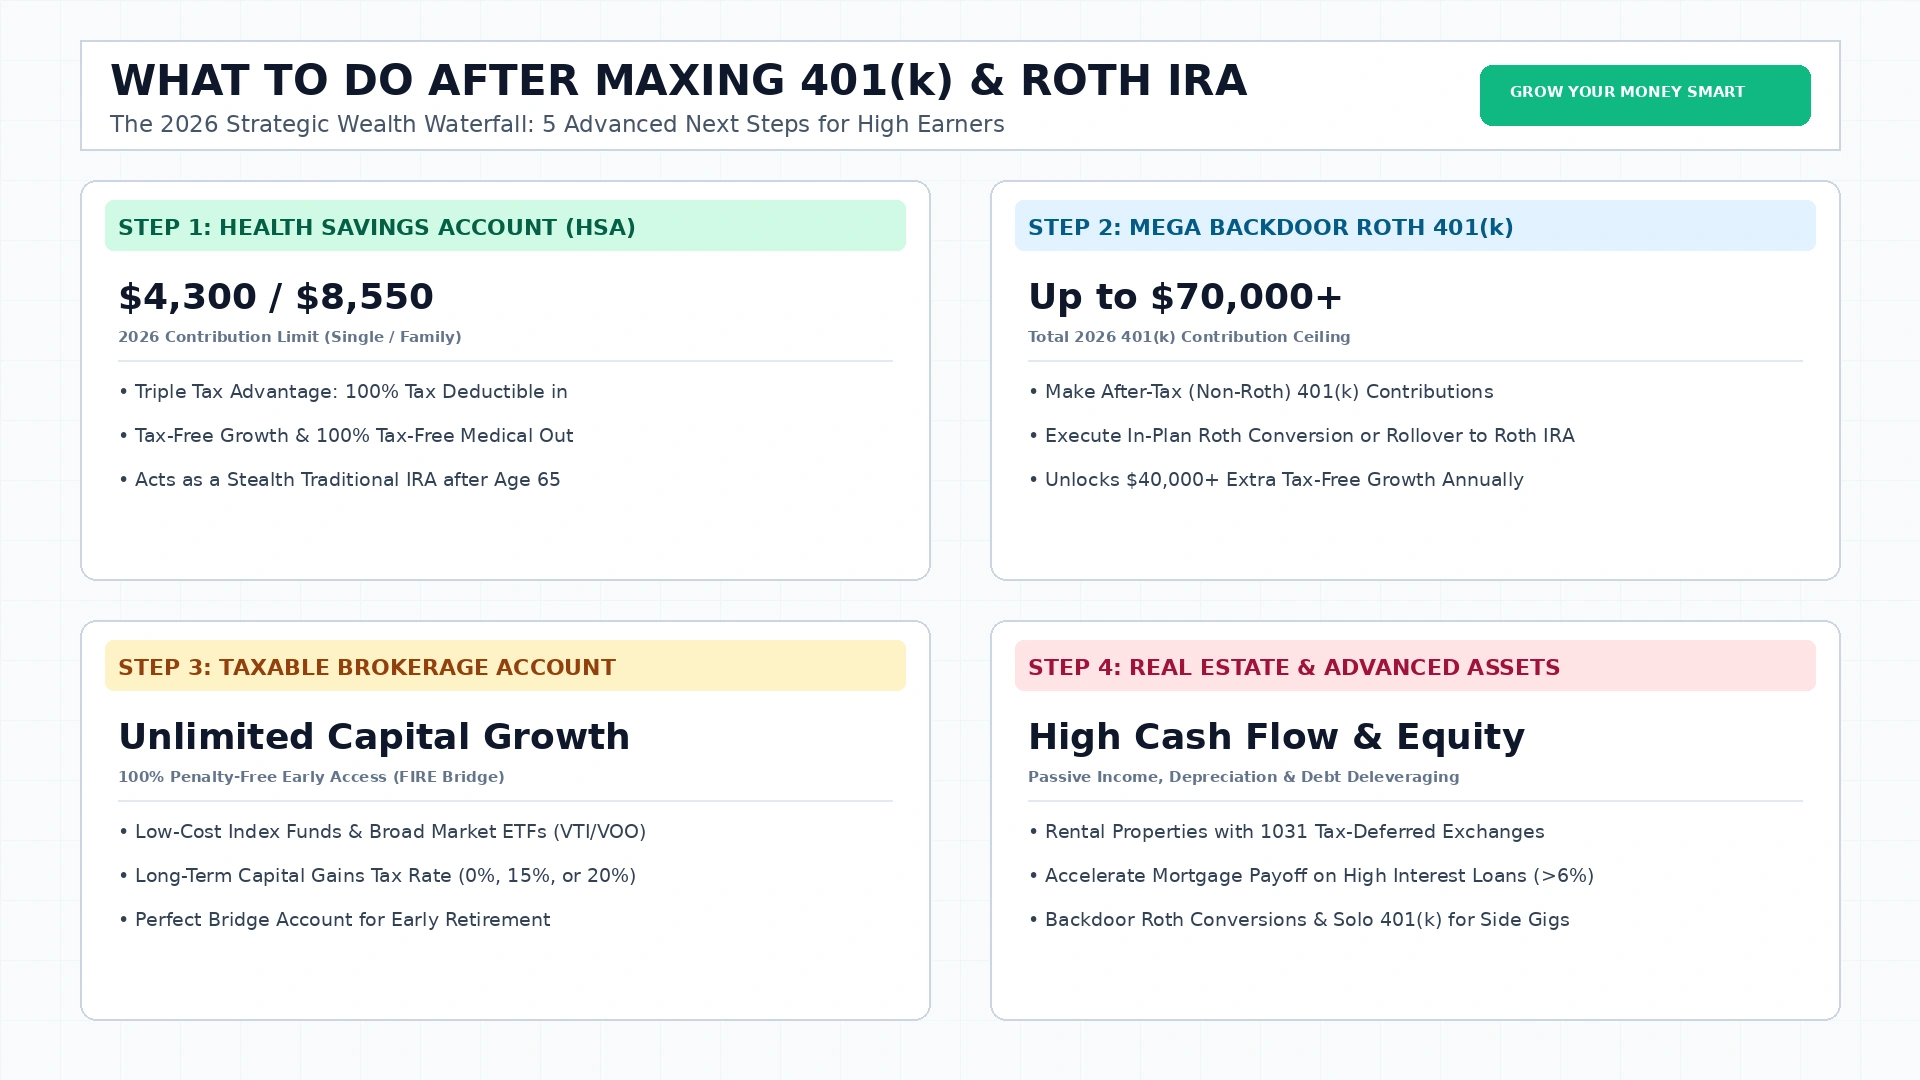
what to do after maxing out 401k and roth ira strategic wealth waterfall guide

If you are wondering what to do after maxing out 401k and roth ira accounts in 2026, you have reached an elite milestone in personal finance. In addition, consolidating orphan employer accounts via a rollover from a 401(k) to an IRA eliminates hidden administrative plan fees. Funneling over $30,500 annually into your 401(k) ($23,500) and … Read more

How to Max Out 401(k) and Roth IRA in 2026: Step-by-Step

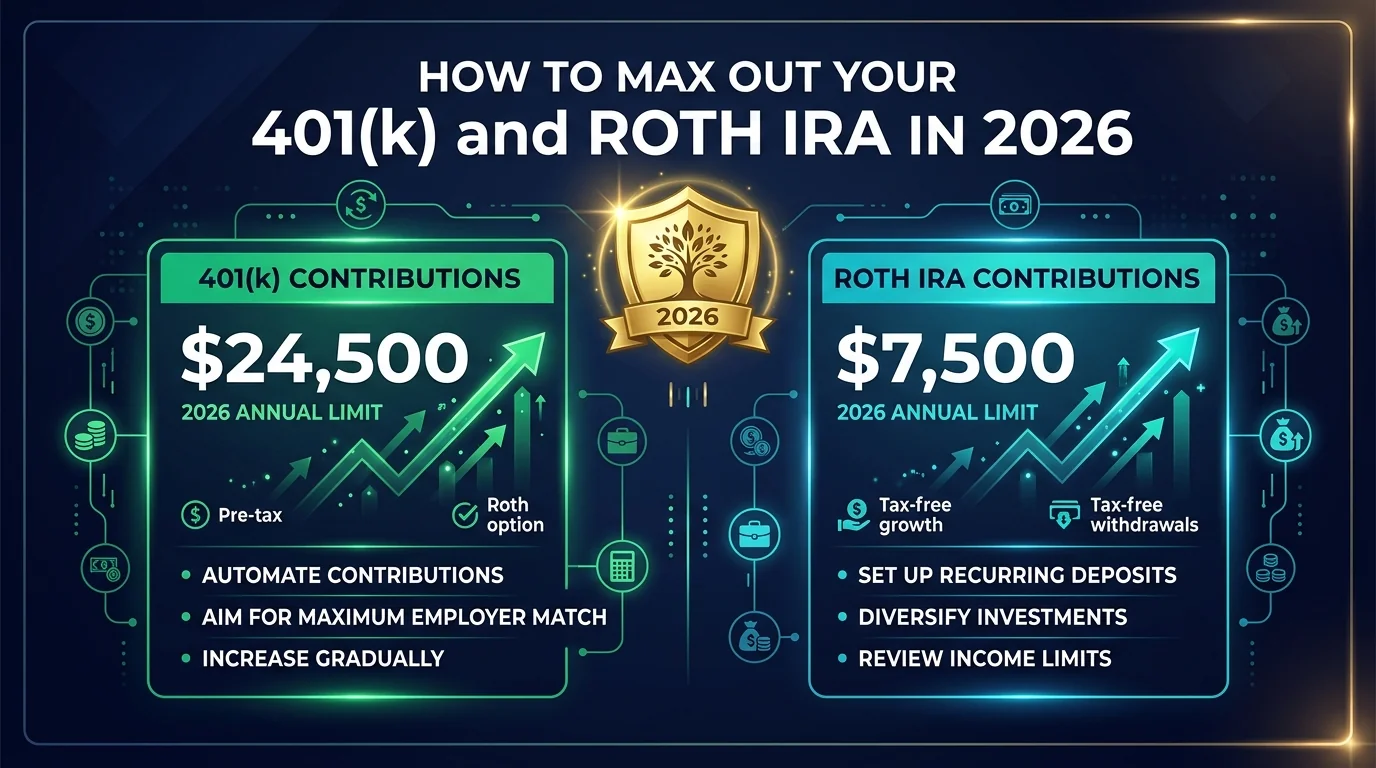
Infographic guide illustrating 2026 contribution limits of 4,500 for 401(k) and ,500 for Roth IRA with execution checklist

Learning how to max out 401(k) and Roth IRA in 2026 is the single most powerful strategy for building multi-generational wealth and achieving complete financial independence. If you have legacy accounts from previous employers, learn how to rollover a 401(k) to an IRA cleanly without triggering taxes or penalties. For high-income earners and disciplined savers … Read more

Receive the latest articles in your inbox

Join smart readers getting actionable personal finance tips, debt payoff blueprints, and retirement guides directly to their inbox.

⚖️ Important Financial Disclaimer & Educational Notice

The articles, calculators, debt payoff strategies, and financial tools on Grow Your Money Smart are provided strictly for general educational, illustrative, and informational purposes. Content published on this website does not constitute tailored financial, investment, tax, or legal advice.

Financial markets, interest rates, and personal financial circumstances vary significantly. You should evaluate your unique financial situation or consult a licensed Fiduciary, Certified Financial Planner (CFP®), or certified tax professional before making any significant financial decisions.

×