
Successful sandwich generation financial planning follows the Oxygen Mask Principle: Secure your own retirement savings (401k match and Roth IRA) and a 6-month emergency reserve before funding children’s college or subsidizing aging parents’ medical care. Because students can access college grants, loans, and scholarships while seniors can access Medicare, Medicaid, and VA benefits, there are no loans for your retirement. Implement durable powers of attorney early and claim IRS caregiver tax credits.
Caught squarely between supporting growing children and managing the declining health of aging parents, members of the sandwich generation carry one of the heaviest financial and emotional burdens in modern society. Typically in their 40s and 50s—the prime wealth-accumulation window of their careers—these dual-caregivers face an intense squeeze: college tuition bills arriving in the mail while home health aide copays and memory care facility deposits drain liquid checking accounts.
Without a structured financial operating model, this squeeze forces many caregivers to make catastrophic compromises: raiding their 401(k) accounts, halting retirement contributions, or racking up high-interest credit card debt. In this master guide, we provide a mathematical, multi-generational wealth framework to preserve your financial sanity, leverage government safety nets, and protect your own retirement.
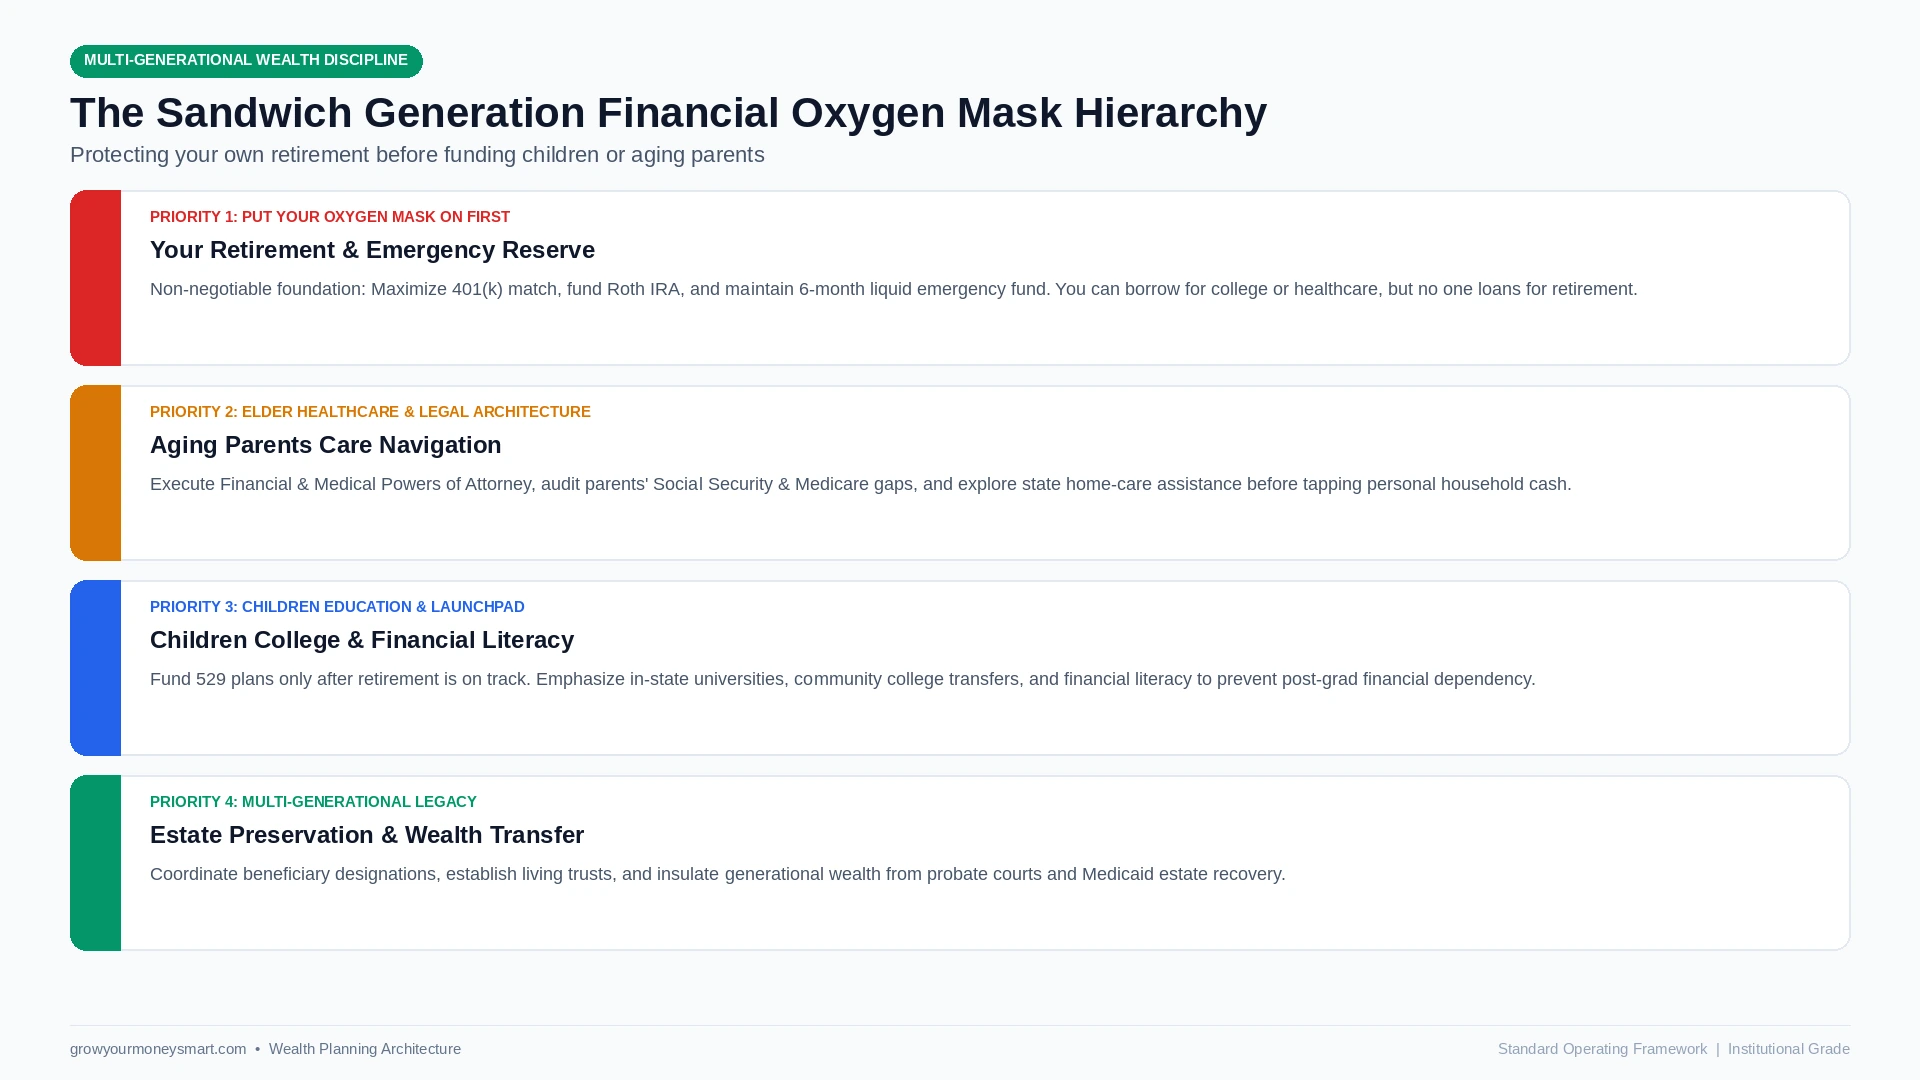
The Golden Rule: Put Your Financial Oxygen Mask on First
Whenever you board an airplane, flight attendants deliver an essential safety briefing: “Secure your own oxygen mask before assisting others.” In personal finance, this principle is absolute law. If you compromise your own financial solvency to pay for your child’s out-of-state private tuition or to cover your parents’ non-essential expenses, you simply pass the caregiving burden forward to your own children twenty years from now.
Consider the fundamental borrowing asymmetry of American finance:
- Your Children’s Education: Can be financed through a combination of federal student loans, merit scholarships, work-study programs, community college transfers, and in-state tuition discounts.
- Your Parents’ Healthcare: Can be structured through Medicare, Medicaid long-term care programs, Veterans Aid & Attendance, and state respite vouchers. To evaluate whether private asset protection is viable for aging parents, explore our guide on whether long-term care insurance is worth it.
- Your Retirement: Has zero financial aid, zero scholarships, and zero loans. If you arrive at age 65 with an empty nest egg, your only option is continuous manual labor or financial dependency on your children.
Maintain your baseline financial fortress by following our foundational guide on how much to save in an emergency fund and master your household cash allocations with our breakdown on how to budget a $5,000 monthly salary.
| Generational Priority Tier | Target Focus & Account Vehicle | Golden Financial Rule | Critical Hazard / Trap |
|---|---|---|---|
| Tier 1: Personal Wealth Base | 401(k) match, Roth IRA, 6-Month Emergency Fund | Non-negotiable automated funding | Halting 401(k) contributions to pay parent bills |
| Tier 2: Aging Parents Support | Powers of Attorney, Medicare, Medicaid planning | Optimize public entitlements first | Co-mingling personal bank accounts with parent funds |
| Tier 3: Children’s Education | 529 College Savings, scholarships, in-state options | Fund with surplus only after Tier 1 & 2 | Taking massive Parent PLUS loans without payoff plan |
| Tier 4: Family Legacy | Revocable Living Trust, Beneficiary TOD/POD | Bypass probate court completely | Dying intestate and freezing family assets in court |
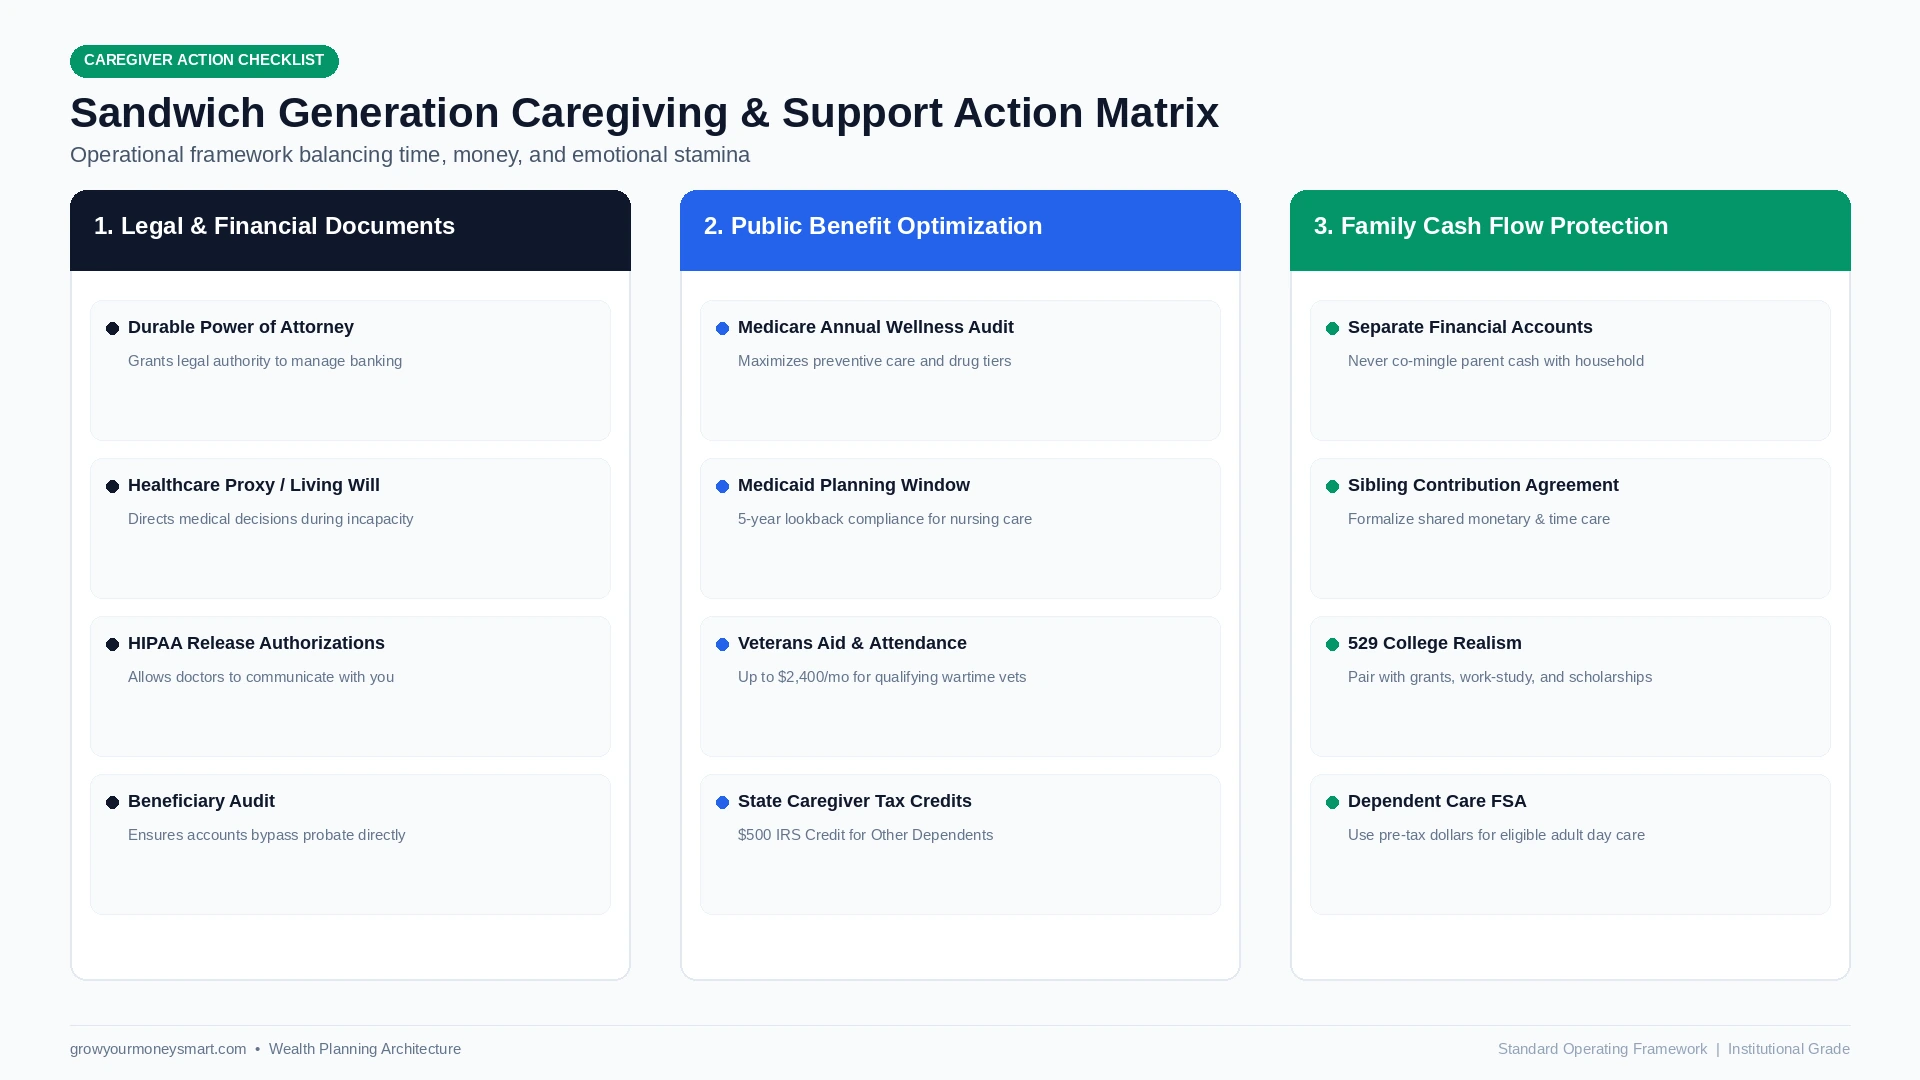
Crucial Legal & Medical Architecture to Establish Immediately
Before writing checks out of your personal accounts, establish legal authority over your parents’ affairs. When an unexpected cognitive decline or medical emergency hits, you cannot talk to your parents’ doctors or access their checking accounts without explicit legal documents:
1. Durable Financial Power of Attorney (POA)
Grants you legal authority to manage your parents’ bank accounts, pay property taxes, file tax returns, and apply for government benefits if they become incapacitated. Without a durable POA, you must petition a probate court for an expensive and intrusive conservatorship.
2. Healthcare Proxy & Living Will
Names you as medical decision-maker and outlines end-of-life preferences (intubation, palliative care). Pair this with signed HIPAA Release Authorizations so physicians can share medical updates with you without violating federal privacy laws.
3. Living Trust & Beneficiary Audit
Ensure your parents’ home and titled assets avoid probate court delays. For step-by-step guidance on structuring these documents, explore our guide on will vs living trust difference and ensure accounts bypass court with proper beneficiary designations vs wills.
Maximizing Government Benefits and Caregiver Tax Breaks
Caregiving generates substantial out-of-pocket expenses, but thousands of families fail to claim the government deductions and credits designed to assist them:
- IRS Credit for Other Dependents ($500): According to the Internal Revenue Service (IRS), you can claim a non-refundable $500 tax credit for an elderly parent if you provide more than 50% of their annual financial support and their gross taxable income falls below annual thresholds.
- Medical Expense Deduction: If you itemize deductions on IRS Schedule A, you can deduct medical expenses paid on behalf of a qualifying parent to the extent those expenses exceed 7.5% of your Adjusted Gross Income (AGI).
- Dependent Care Flexible Spending Account (FSA): You can allocate up to $5,000 in pre-tax dollars through your employer’s Dependent Care FSA to pay for qualified adult day care or in-home caregiving while you work.
- Veterans Aid & Attendance: If an aging parent served during wartime (WWII, Korea, Vietnam) and requires assistance with daily living, the VA provides monthly pension supplements of up to $2,400+ for single veterans or surviving spouses.
The official guidelines from Medicare.gov make clear that Medicare does NOT cover non-skilled, custodial long-term care. Understanding this distinction early prevents devastating surprise bills when home assistance is needed.
Tactical Family Wealth Meetings & Sibling Agreements
In most multi-sibling families, caregiving responsibilities fall disproportionately on one child—often the child living closest or the oldest daughter. This creates intense financial friction and emotional burnout. Follow these ground rules:
- Call a Neutral Family Meeting: Convene all siblings (in person or over video) to review parents’ actual financial balances, monthly shortfalls, and caregiving needs with total transparency.
- Draft a Personal Care Agreement: If one sibling quits their job or reduces working hours to provide daily hands-on care, formalize a written contract where parents’ funds (or shared sibling contributions) pay that caregiver a fair market hourly wage. This also protects against Medicaid gift penalties during asset lookback audits.
- Separate Accounts Strictly: Never deposit parent pensions into your personal checking account. Maintain dedicated accounts to preserve clear accounting.
If you carry lingering consumer debts, eliminate them quickly using our guide on how to prioritize multiple debts, optimize spousal retirement payouts with Social Security spousal benefits, and expand your wealth waterfall with what to do after maxing out 401(k) and Roth IRA.
Frequently Asked Questions
👨👩👧👦 Multigenerational Caregiving, Long-Term Care & Estate Hub
Balance elder care, college savings, and your own retirement with these companion strategic guides:
- Elder Care Insurance: is long-term care insurance worth it in 2026? — evaluating coverage to prevent aging parents’ care from depleting family savings.
- Estate Coordination: beneficiary designation vs will: costly traps — ensuring parent titles and retirement accounts bypass contested probate.
- Spousal Optimization: Social Security spousal benefits: maximize payouts — maximizing claiming strategies for elderly parents and spouses.
- Family Cash Flow Sheet: free monthly budget spreadsheet and net worth tracker — download our spreadsheet to model dual-generation caregiving costs.
- Budget Percentage Guide: zero-based budgeting vs 50/30/20 rule comparison — restructuring discretionary spending while funding dependent care.
Jaiveer Hooda is a personal finance researcher and the founder of Grow Your Money Smart. With a background in computer engineering, he approaches money the way an engineer approaches any complex system — through data analysis, mathematical modeling, and ruthless optimization.
He built this platform on a single conviction: financial freedom is not a matter of luck. It is a system that can be designed, tested, and executed by anyone willing to follow the right blueprint. Every strategy published here is researched to the numbers, not written to the trend.
Expertise: Debt elimination · Retirement planning · Passive income · Budgeting systems
Connect: Pinterest | growyourmoneysmart.com | Contact Us