
How long to pay off minimum payment? Paying only the minimum on a standard credit card takes 15 to 32+ years because formulas allocate only 1% toward principal while ~99% covers interest fees. On a $10,000 balance at the 2026 average 24.7% APR, minimum payments take 28.5 years and generate $19,450 in compound interest. Switching to a fixed $350–$400 monthly payment eliminates the debt in 3.1 years, saving $15,300+ in pure cash.
- The Math Trap: Banks deliberately design minimums to barely cover accumulated interest plus a sliver (1%) of principal, keeping you indebted for decades.
- The 3x Payoff Shock: Paying minimums on $10,000 forces you to repay nearly $30,000 in total cash—giving the credit card issuer a 200% profit on your debt.
- The CARD Act Legal Rule: Any payment made above the minimum must legally be applied to your highest interest balance first under consumer protection laws.
- Fix Your Payment: Never pay the declining minimum. Lock in a fixed monthly payment (e.g., $400 or $500) to crush the amortization curve.
- Zero-Cost Balance Transfer: Use our vetted 0% APR balance transfer cards to eliminate interest for up to 21 months.
When your monthly credit card statement arrives in the mail or pinging your mobile banking app, the most prominent number displayed in bold text is never your full balance. It is the deceptively harmless “Minimum Payment Due.”
Seeing a $250 minimum payment on a $10,000 balance creates a dangerous psychological illusion of affordability. You pay the $250, congratulate yourself on staying current, and assume your debt is slowly shrinking. But in reality, you have stepped directly into the most profitable mathematical trap ever devised by the banking industry.
Whether you are following our blueprint to pay off $10k debt in 1 year, tackling multiple cards with our debt priority guide, or negotiating with issuers in our credit card hardship guide, this guide reveals the exact math behind minimum payments and how to break free forever. You can also calculate your payoff trajectory directly with our interactive free debt payoff calculator.
Interactive Credit Card Minimum Payment & Payoff Calculator
Use our real-time debt acceleration tool below to calculate your exact payoff timeline. Adjust your credit card balance, APR, and monthly payments to see how thousands of dollars in compound interest vanish when you break the minimum payment trap:
Credit Card Minimum Payment Calculator Formula: How Banks Calculate Minimums
Federal regulations enforced by the Consumer Financial Protection Bureau (CFPB) require credit card issuers to calculate minimum payments using one of two standard formulas:
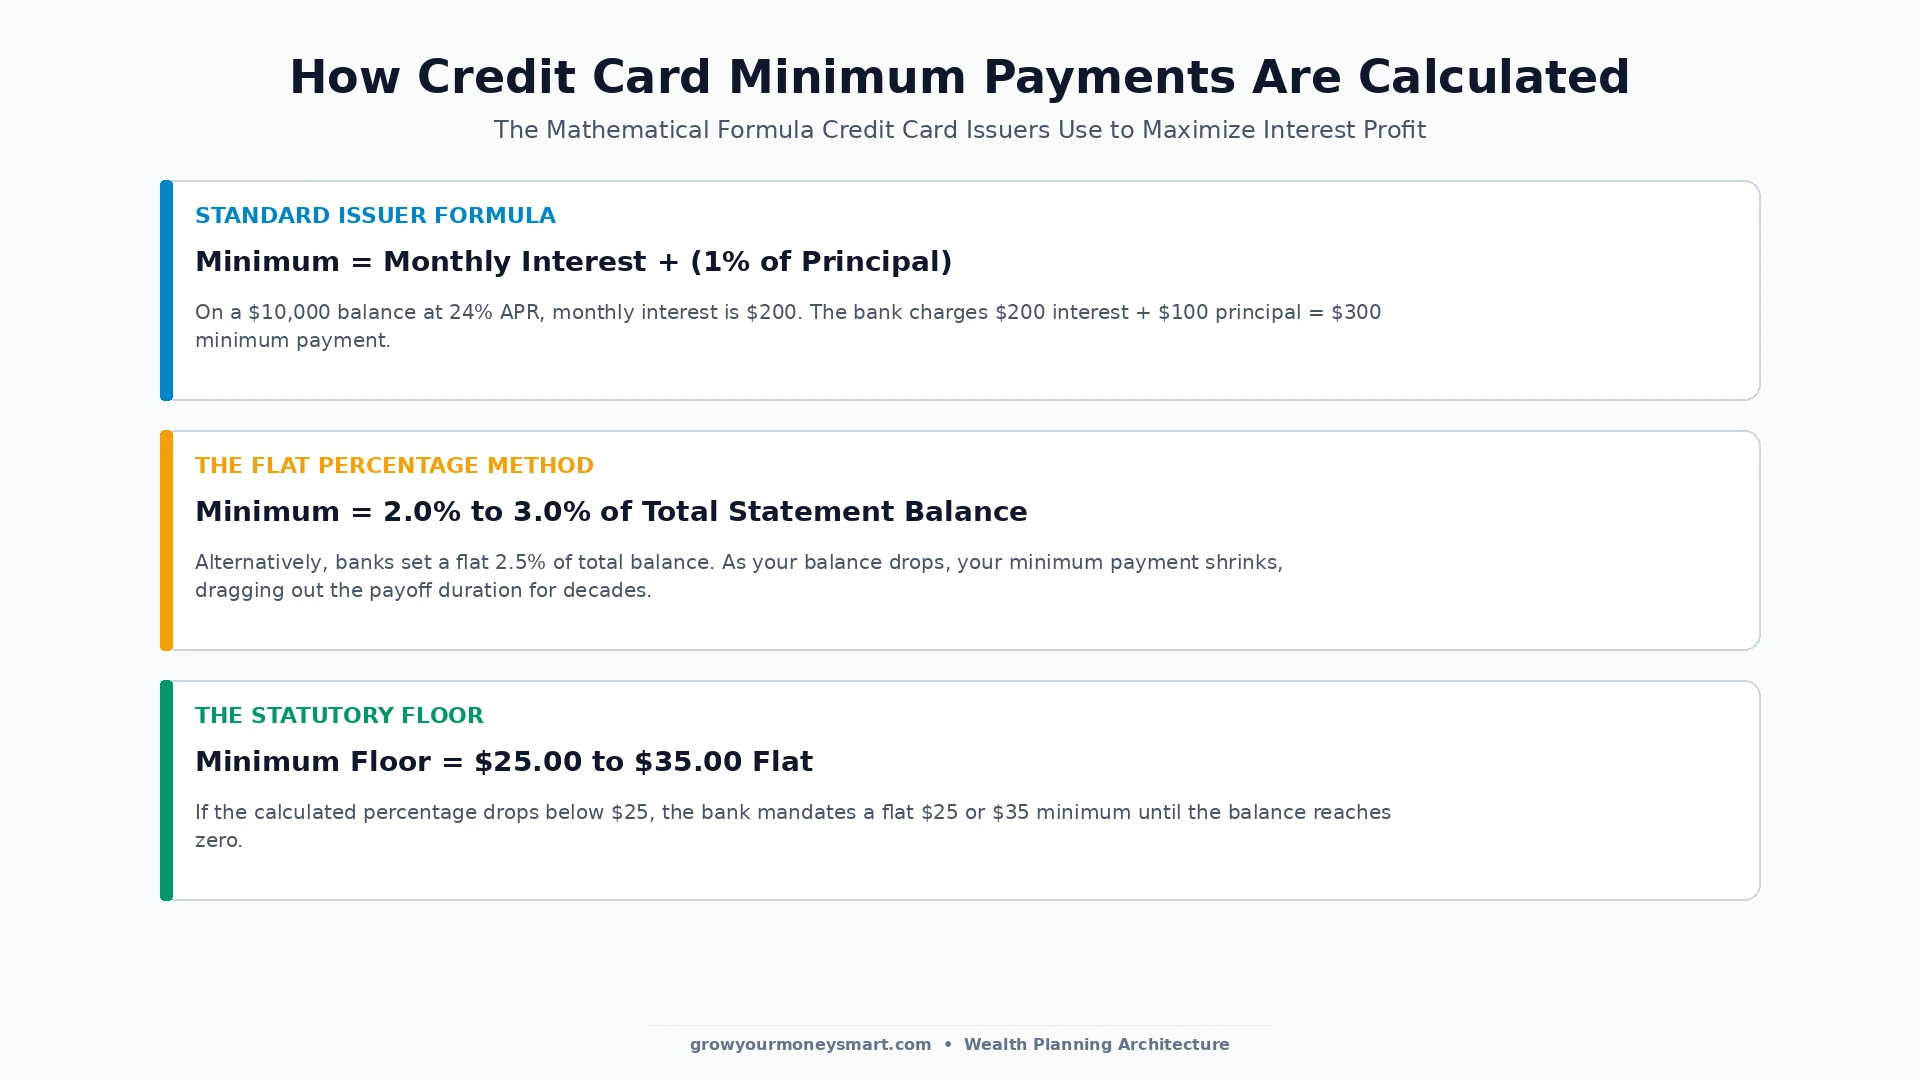
Under the standard formula (Interest + 1% of Principal), on a $10,000 balance at 24% APR, your monthly interest charge is approximately $200. The bank adds 1% of principal ($100), resulting in a $300 minimum payment. Out of your $300 check, two-thirds disappears into the bank’s profit margins, leaving only $100 to reduce your balance.
The $10,000 Credit Card Showdown: Minimums vs. Fixed Payments
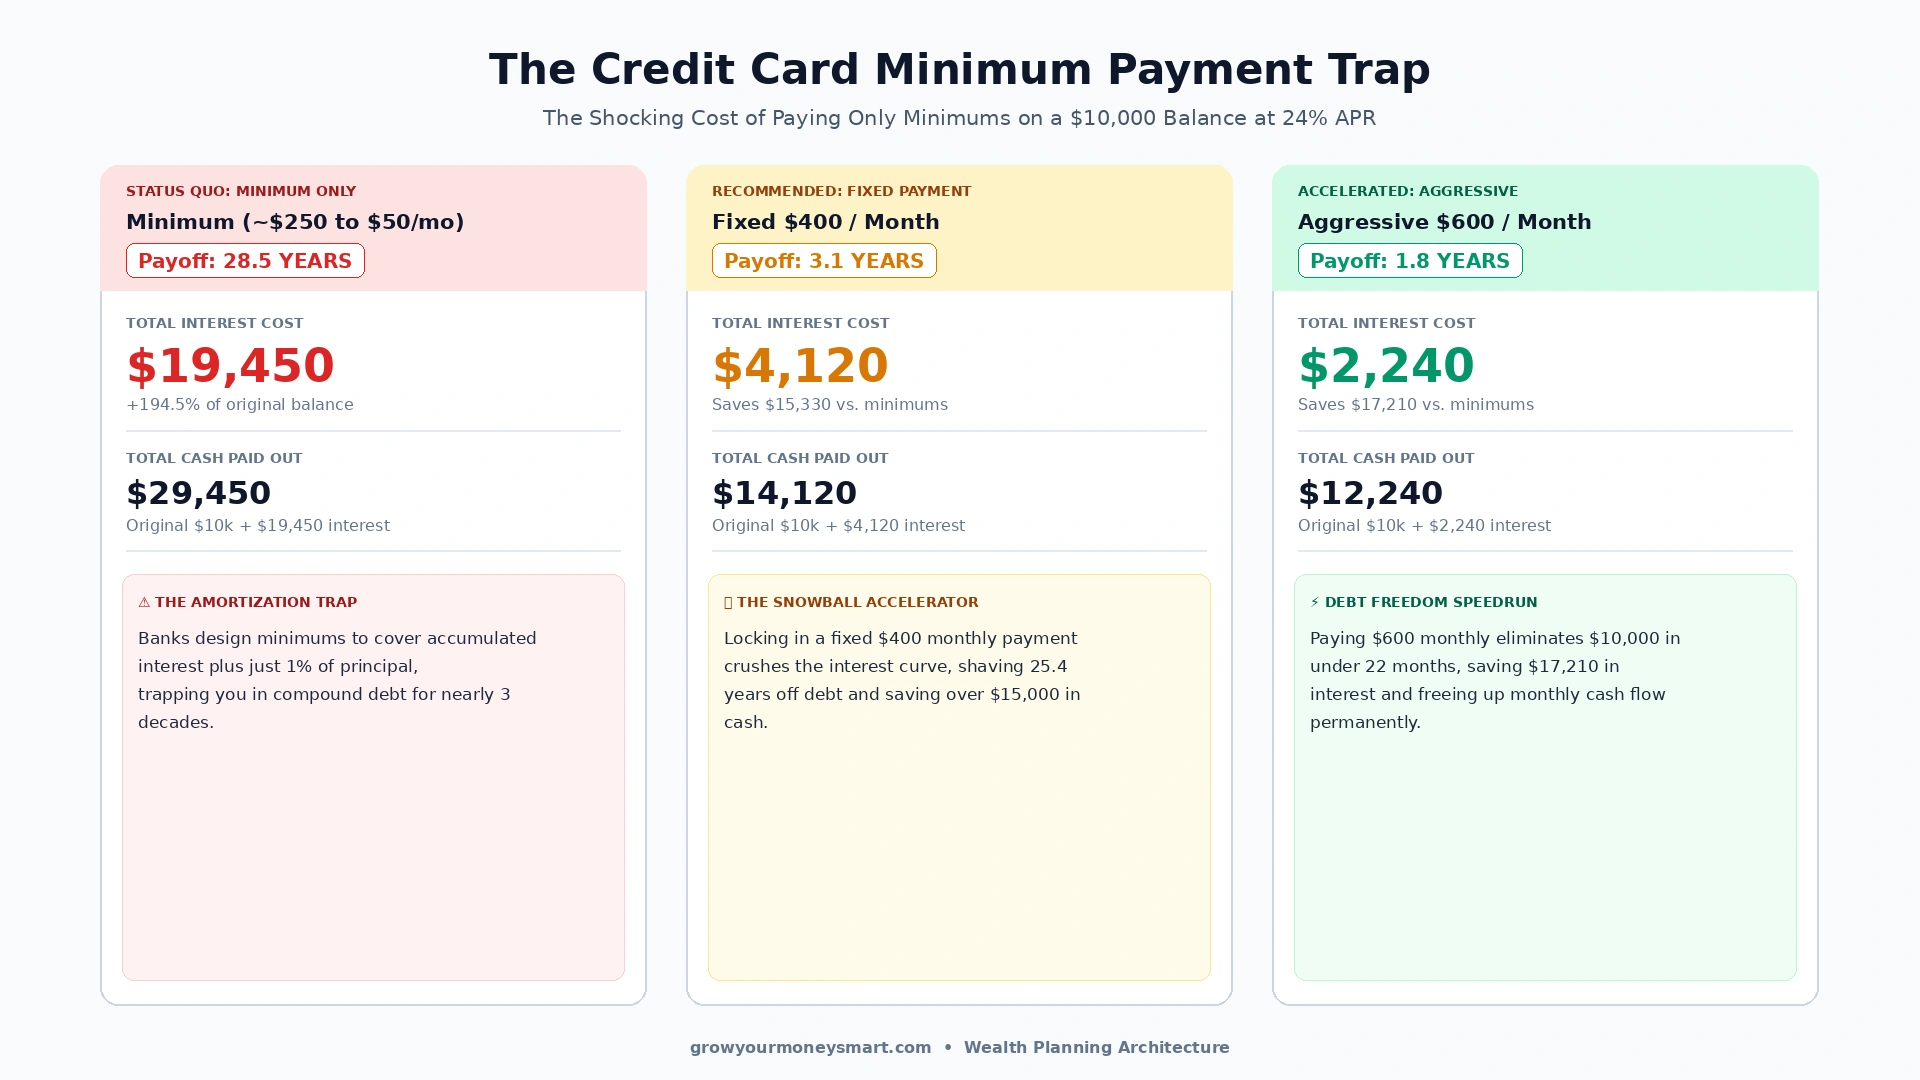
Let’s examine the mathematical reality of a $10,000 balance at 24% APR across three repayment strategies:
Notice the power of fixing your payment: by simply committing to a fixed $400 per month instead of letting the minimum payment decline, you shave over 25 years off your debt and save an astounding $15,330 in cash. That is over $15,000 you keep in your own pocket instead of gifting to credit card executives.
How Long to Pay Off Minimum Payment? (Real-World Timeline Table)
One of the most frequent questions borrowers ask is: how long to pay off minimum payment balances across different debt amounts? The table below illustrates the exact payoff timelines and devastating interest charges on typical credit card balances at the current 2026 benchmark APR (24.7% per Federal Reserve consumer credit data):
5 Actionable Steps to Escape the Minimum Payment Trap Today
- 1. Fix Your Monthly Payment: Never allow your monthly contribution to shrink as your balance drops. If your initial minimum was $300, keep paying $300 (or more) every single month until the balance hits zero.
- 2. Transfer to a 0% APR Balance Transfer Card: Move high-interest balances to a card offering 0% APR for 15 to 21 months. Every dollar paid goes 100% to principal. (See our top picks in the Best 0% APR Balance Transfer Cards Guide).
- 3. Negotiate Your Interest Rate: Call your card’s customer service number and cite your on-time payment history to request an APR reduction or hardship freeze. (Follow our scripts in Negotiating Credit Card Interest and our guide on Credit Card Hardship Programs).
- 4. Deploy the Debt Avalanche Method: Direct all extra debt payoff cash to the card carrying the highest APR (e.g., 26.99% store card) while paying minimums on the rest, mathematically minimizing interest expense. Compare timelines in our deep-dive on Debt Avalanche vs Snowball: Which Pays Debt Faster?.
- 5. Protect Your Emergency Cash Buffer: Avoid draining 100% of your liquidity to pay credit cards, which leads to immediate re-borrowing when unexpected expenses strike. Balance your cash reserves using our framework on Pay Off Debt vs. Save Emergency Fund or follow our blueprint to Pay Off Debt Living Paycheck to Paycheck.
Expert Video Breakdown: The Credit Card Minimum Payment Trap Explained
To understand the exact mathematical compounding formula credit card companies use to keep borrowers in decades of high-interest debt, watch Humphrey Yang’s breakdown:
Frequently Asked Questions (FAQs)
Most credit card issuers calculate minimum payments as the monthly interest charges plus 1% of the principal balance, or a flat 2.0% to 2.5% of the total statement balance (whichever is greater), subject to a minimum floor of $25 to $35.
Because minimum payments cover mostly interest and barely touch the underlying principal balance. On a $10,000 balance at 24% APR, paying only the minimum takes over 28 years and costs nearly $20,000 in interest alone.
Paying the minimum on time protects your payment history, but it keeps your Credit Utilization Ratio dangerously high (above 30% to 50%), which severely lowers your overall credit score.
Under the Credit CARD Act of 2009, any payment amount made above the minimum must legally be applied directly to the balance carrying the highest interest rate, dramatically reducing your total interest fees and payoff time.
Yes. Calling your credit card issuer and asking for a promotional interest rate reduction or requesting a hardship program can lower your APR from 25% down to 0% to 9%.
Switch from a declining minimum payment to a fixed monthly payment (e.g., $400/month), transfer balances to a 0% APR balance transfer credit card, or consolidate using the Debt Avalanche method.
Federal law requires all credit card issuers to print a ‘Minimum Payment Warning’ box on page 1 or 2 of your monthly billing statement, showing exactly how long payoff takes and total interest cost if paying only minimums.
A 0% APR balance transfer pauses interest accrual for 15 to 21 months, allowing 100% of your monthly payments to attack the principal balance.
At the 2026 national average APR of 24.7%, paying only the minimum payment takes 15 to 32 years depending on your balance. For instance, a $5,000 balance takes 22.8 years and costs $8,940 in interest, while a $10,000 balance takes 28.5 years and $19,450 in interest. Setting a fixed payment of $250 to $400/month reduces the payoff duration to approximately 2.3 to 3.1 years, saving thousands in cash.
Jaiveer Hooda is the Lead Financial Researcher & Personal Finance Analyst at Grow Your Money Smart. Specializing in personal wealth optimization, index fund compounding, high-yield savings mechanics, and consumer debt elimination strategies. With a background in computer engineering, he applies mathematical modeling, cashflow simulations, and empirical risk analysis to evaluate personal finance vehicles and credit products. Every analysis is backed by verified regulatory disclosures, IRS tax schedules, and empirical APY compounding math.
Areas of Expertise: Personal Finance · High-Yield Savings Accounts (HYSA) · Index Funds & S&P 500 Compounding · Retirement Planning (401k/IRA) · Debt Optimization · Credit Card APR Mechanics.
Transparency & Editorial Policy: Editorial Standards | Report a Correction