
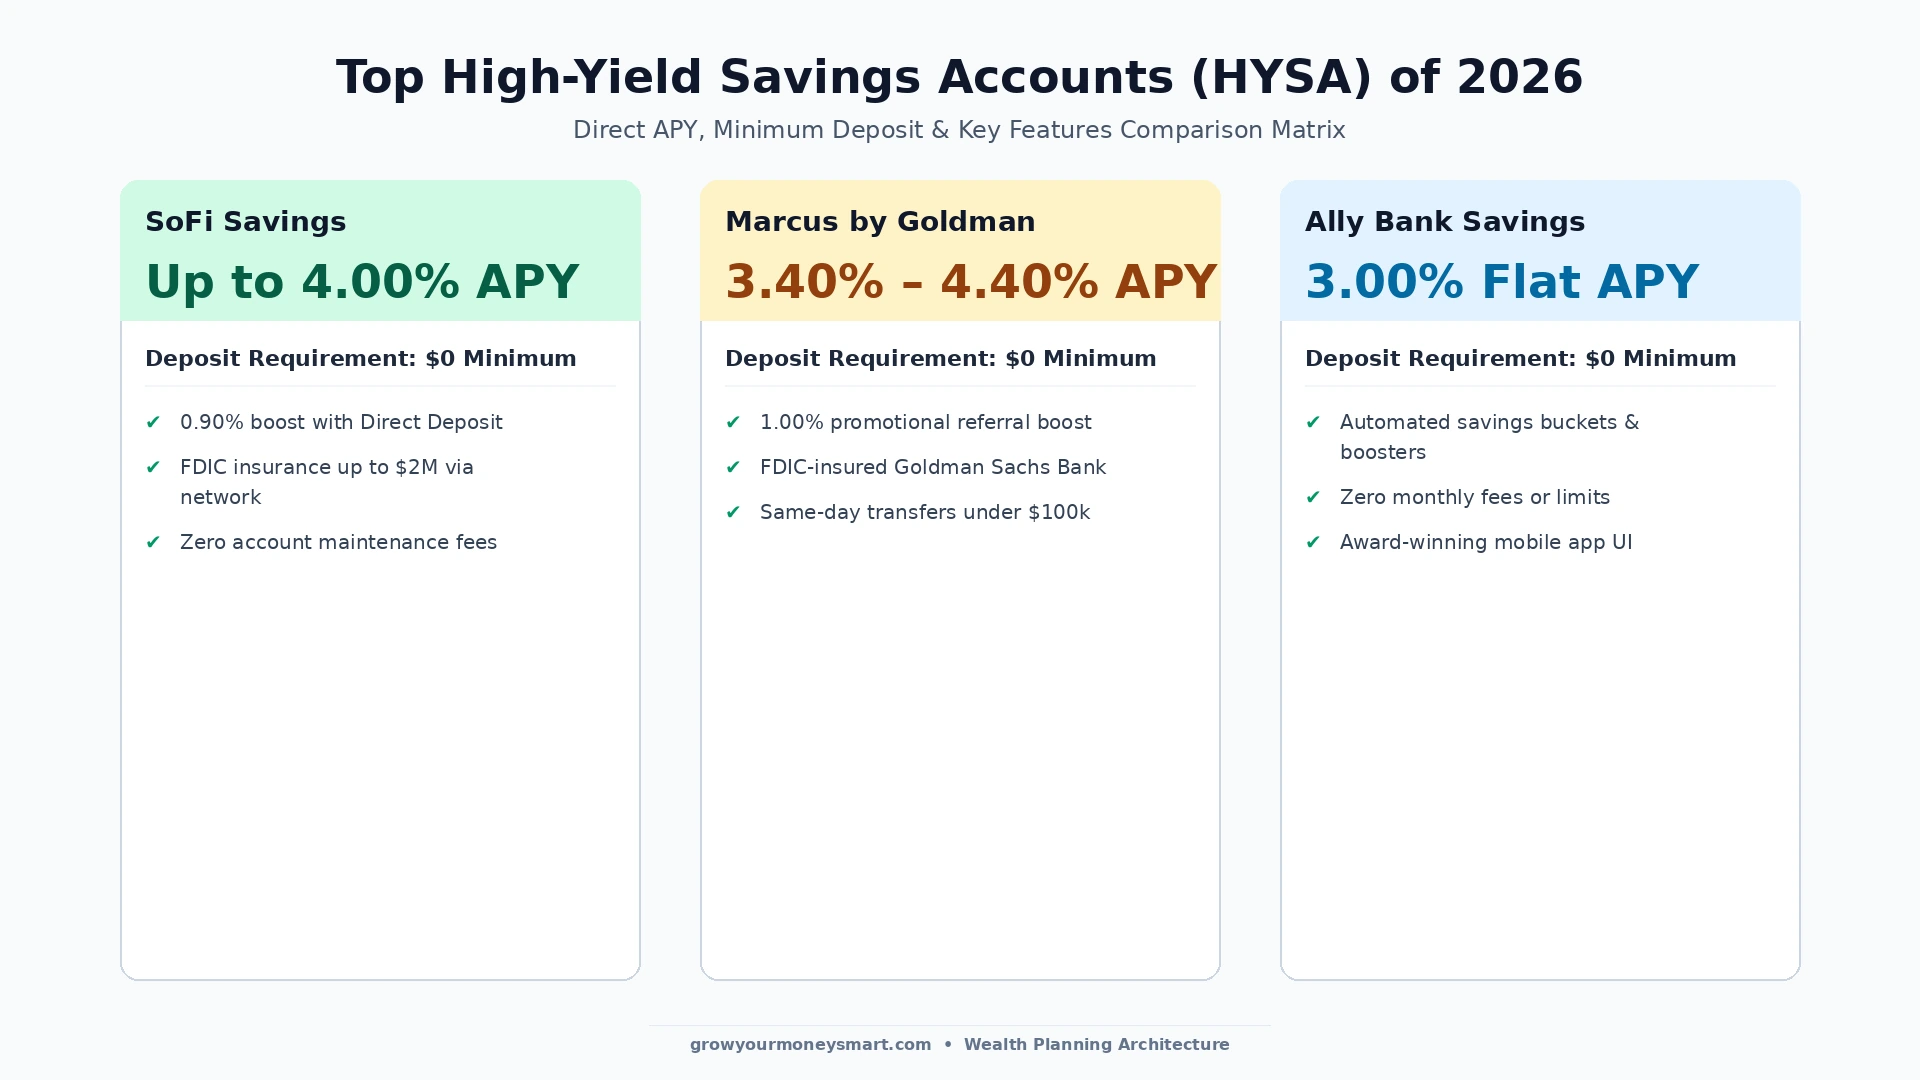
The best HYSA accounts 2026 (and top high-yield savings picks) yield between 3.00% and 4.40% APY—roughly 10x to 12x higher than legacy brick-and-mortar banks. For the highest APY savings, top contenders include Marcus by Goldman Sachs (3.40%–4.40% with referral/AARP bonus), SoFi (up to 4.00% with qualifying direct deposit), and Ally Bank (3.00% with automated smart savings buckets). All accounts feature $0 monthly maintenance fees and $250,000 FDIC deposit protection (read our full breakdown on FDIC insurance limits and how to protect $1M+ safely). Looking to lock in guaranteed fixed rates before central bank cuts? Explore our comprehensive comparison of a CD ladder vs high-yield savings account.
- The 10x APY Advantage: Traditional brick-and-mortar checking and savings accounts pay an average of 0.01% to 0.45% APY, while leading online HYSAs pay 3.00% to 4.40% APY on liquid cash.
- Zero Risk, FDIC Backed: Deposits are federally insured by the FDIC up to $250,000 per depositor, making HYSAs 100% capital protected.
- The $1,000 Difference: Keeping $25,000 in an HYSA generates over $1,000 in annual interest, compared to just $2.50 in a standard checking account.
- Top Standouts: SoFi leads for high-earning direct deposits, Marcus leads for pure transfer speed, and Ally leads for multi-goal savings buckets.
- Complete Liquidity: Unlike CDs or market investments, your cash remains 100% accessible with zero lock-in penalties.
Leaving your emergency fund or short-term cash reserves in a traditional commercial checking account is one of the most expensive financial mistakes in personal finance. In 2026, the national average savings interest rate at legacy brick-and-mortar institutions lingers at a microscopic 0.01% to 0.45% APY. At that rate, inflation quietly devours your purchasing power every single year.
By contrast, the best high-yield savings accounts (HYSAs) currently offer between 3.00% and 4.40% APY. Because online financial institutions do not maintain thousands of expensive physical branches, they return their operational savings directly to account holders. Best of all, your cash remains liquid, accessible within 24 to 48 hours, and backed by the full faith and credit of the United States government via the Federal Deposit Insurance Corporation (FDIC).
Whether you are parking cash for our emergency fund master guide, accumulating a down payment using our house deposit savings strategy, or deciding between market growth in our HYSA vs. Stocks guide, this 2026 review breaks down the top high-yield accounts, their exact APYs, fee structures, and transfer speeds.
Top 5 Highest APY HYSA Accounts for 2026: Head-to-Head Comparison
Here is how the market leaders stack up across APY benchmarks, deposit requirements, and core features. If you need direct check-writing privileges or debit card access alongside top yields, compare an HYSA against a Money Market Account (MMA) before opening an account.
If your sole priority is securing the absolute highest APY savings rate regardless of brand familiarity, niche online deposit platforms such as Bask Bank (4.60% APY) and Western Alliance Bank (4.50% APY via Raisin) currently lead the national league tables. However, variable HYSA yields fluctuate dynamically with Federal Reserve benchmark rate changes.
⚡ Strategic Cash Alert: With the Federal Reserve transitioning into an active rate-cutting cycle, peak yields on liquid cash accounts will not last indefinitely. Read our tactical guidance on The 5.0% HYSA Window Is Closing: Where to Park Your Cash Right Now to explore high-yield CD ladders and Treasury bill alternatives before rates normalize further.
The Mathematical Compounding Power: $25,000 Cash Case Study
To understand why moving your cash to an HYSA is non-negotiable, examine the math of keeping a standard $25,000 emergency fund in a legacy bank (0.01% APY) versus a leading high-yield account (4.00% APY):
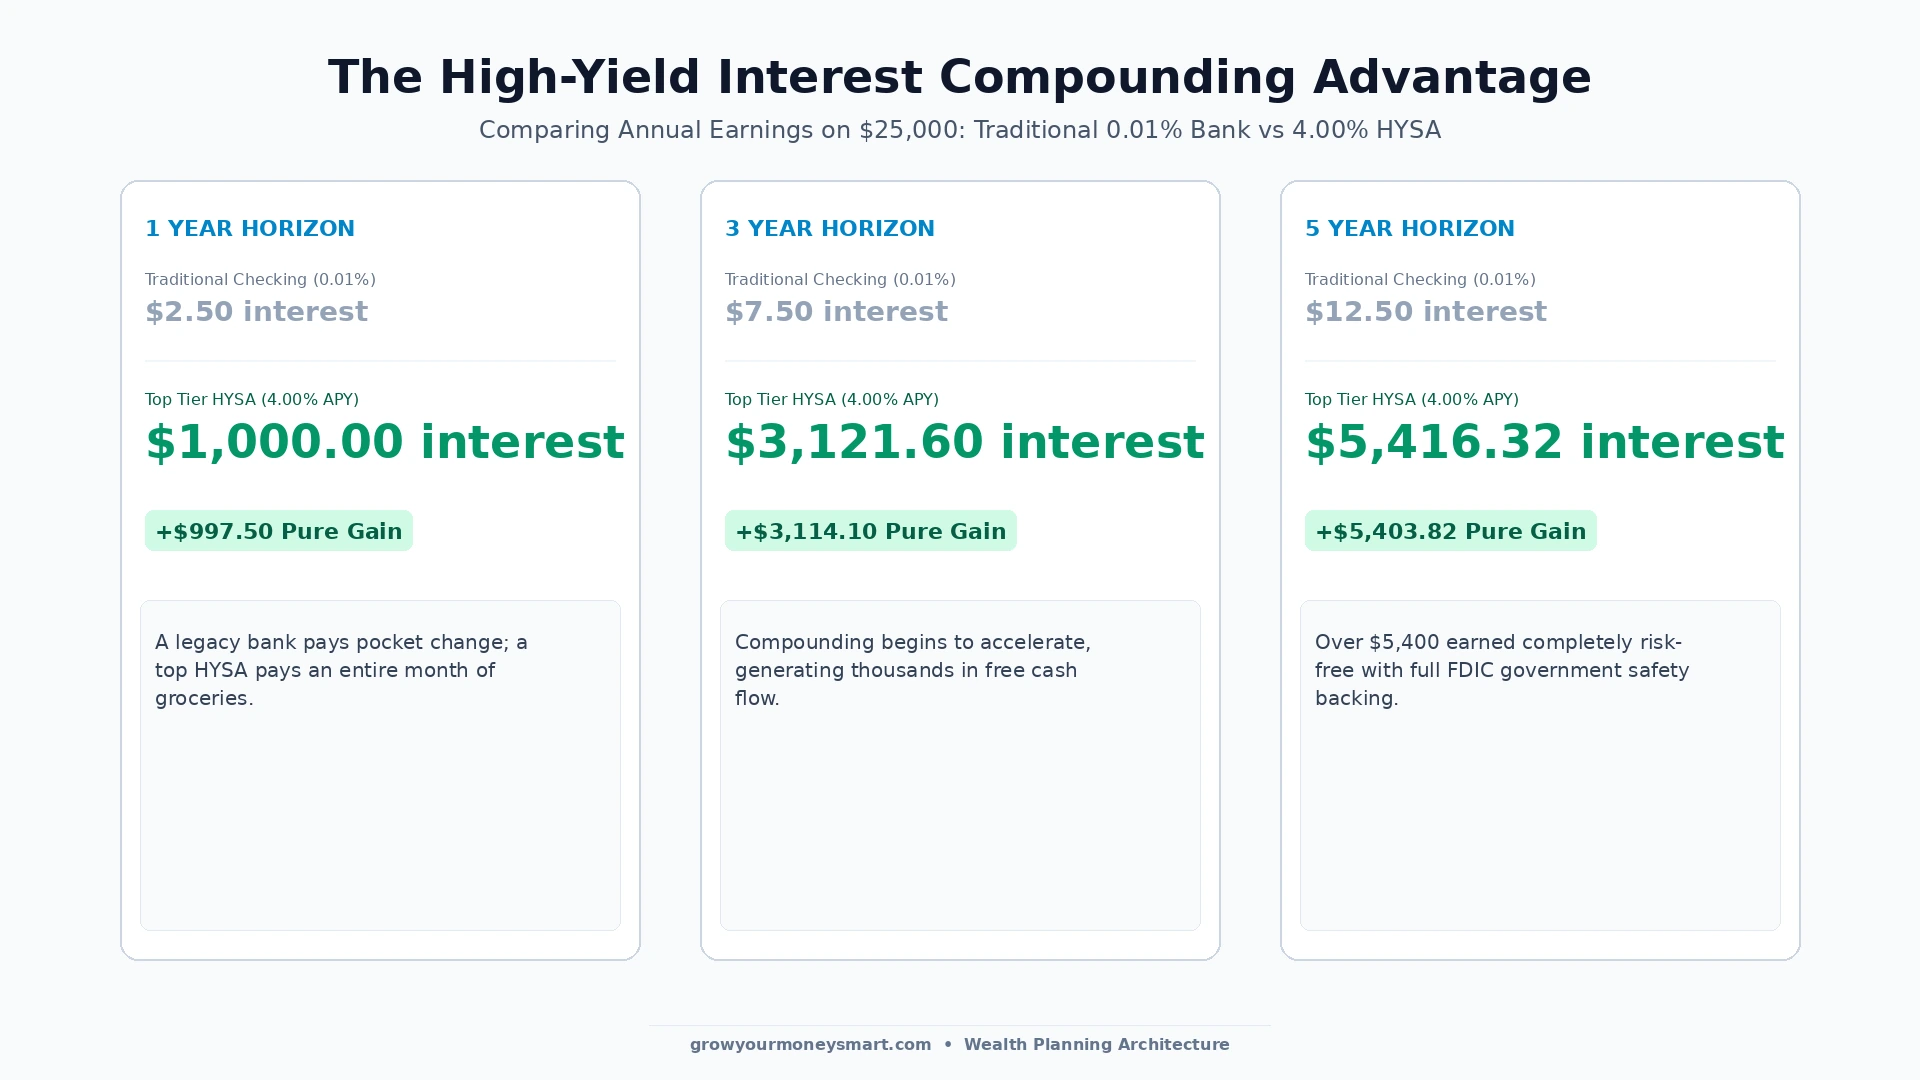
Over a 5-year period, leaving $25,000 in a traditional checking account earns a meager $12.50—essentially zero. In an HYSA compounding monthly at 4.00%, that exact same balance produces $5,416.32 in completely passive, risk-free cash flow. That is over $5,400 of wealth generated with zero effort and zero market volatility risk.
You can simulate your specific cash balance directly using our interactive free emergency fund calculator and our comprehensive budget calculator.
5 Crucial Criteria to Evaluate Before Opening an HYSA
- 1. FDIC / NCUA Government Insurance: Never deposit cash into an uninsured fintech app. Ensure the institution is a direct member of the FDIC or sweeps deposits into FDIC-insured partner banks up to $250,000 per depositor.
- 2. Account Requirements & Direct Deposit Hurdles: Some banks (like SoFi) require active direct deposits to unlock their promotional top tier. If you are self-employed or on an irregular income, choose a bank like Marcus or Ally that offers a flat rate with zero deposit conditions. (See our blueprint on budgeting on an irregular income).
- 3. Emergency Buffer Benchmarking: Before allocating capital, calculate your true baseline expenses with our interactive Emergency Fund Calculator, read our core guide on How Much Emergency Fund Do I Need?, and compare reserves in 3 Months vs 6 Months Emergency Fund.
- 4. Transfer Speed & Hands-Free Automation: When an unexpected expense strikes, you need seamless liquidity. Marcus and Ally offer fast ACH transfers under $100,000. To grow your cash effortlessly every payday, pair your account with our blueprint on How to Automate Savings: Hands-Free System or plan a dedicated property fund via Saving for a House Down Payment Fast.
- 5. Zero Maintenance Fees & Zero Hidden Hurdles: Every top-tier account on our list features $0 monthly service fees, $0 minimum opening balance rules, and full mobile app banking with biometric authentication.
HYSA vs. Money Market Funds vs. Treasury Bills: Where Should Cash Sit?
A frequent question among disciplined savers is whether to park short-term capital in an online HYSA, a brokerage money market fund (MMF), or short-term U.S. Treasury bills. While all three are conservative instruments, their risk structure, tax treatment, and liquidity mechanics differ significantly:
The Fixed Rate Myth: Can You Lock in a High APY?
One common misconception is the search for a “fixed high-yield savings account.” By statutory design, all HYSA rates are variable. Financial institutions maintain the legal right to calibrate their yields overnight in response to the Federal Open Market Committee (FOMC) interest rate announcements. When the benchmark rate declines, variable savings yields naturally follow.
If your financial objective requires locking in a guaranteed annual yield over the next 12 to 36 months without interest rate volatility risk, combine your liquid HYSA with a strategic CD laddering strategy or explore short-term Treasury bills before rate reductions normalize cash yields.
Fintech Deposit Sweeps and Partner Bank Network Protection
Modern cash management platforms and high-yield fintech accounts frequently utilize partner bank sweep networks. Through automated software integrations and multi-bank program agreements, your aggregate deposit is programmatically dispersed across an ecosystem of 8 to 10 distinct partner banks. This architecture extends your effective deposit coverage from the standard 50,000 threshold up to ,000,000 or more in FDIC insurance, while maintaining a single, unified account dashboard.
Expert Video Breakdown: Top High-Yield Savings Accounts Compared
For a comprehensive visual walkthrough of current online banking APYs, withdrawal limits, and FDIC protections, watch personal finance expert Humphrey Yang break down the top high-yield savings accounts:
Frequently Asked Questions (FAQs)
A High-Yield Savings Account (HYSA) is a federally insured savings account offered primarily by online banks that pays an Annual Percentage Yield (APY) 10 to 30 times higher than traditional brick-and-mortar banks, while offering full liquidity and zero risk.
Yes. Legitimate high-yield savings accounts are backed by the Federal Deposit Insurance Corporation (FDIC) or National Credit Union Administration (NCUA) up to $250,000 per depositor, per institution, guaranteeing that your money is 100% safe.
Online banks do not have the massive overhead costs of maintaining physical branch networks, tellers, and commercial real estate leases. They pass these operational cost savings directly to customers in the form of higher APY rates and zero monthly fees.
Yes. HYSA rates are variable and fluctuate in response to monetary policy set by the Federal Reserve. When the Fed adjusts benchmark interest rates, online banks adjust their APYs accordingly.
Yes. Interest earned from a high-yield savings account is treated as ordinary income by the IRS and is subject to federal and state income taxes. Banks issue a Form 1099-INT if you earn $10 or more in annual interest.
Electronic ACH transfers typically take 1 to 3 business days to transfer cash from an online HYSA back to your local checking account. Several institutions, such as Marcus and Ally, offer same-day ACH transfers for qualifying amounts.
An HYSA provides variable interest with complete liquidity, allowing you to deposit or withdraw cash at any time. A Certificate of Deposit (CD) locks your interest rate for a fixed term (e.g., 6, 12, or 24 months), but penalizes you if you withdraw capital early. For a complete mathematical comparison on rate locking versus liquidity trade-offs, read our dedicated guide on CD Laddering vs HYSA.
Most top-rated HYSAs—including Marcus by Goldman Sachs, Ally Bank, and Capital One 360—require a $0 minimum opening deposit and have no minimum monthly balance requirements.
For everyday savers, the best overall HYSA accounts combine high yields with zero hurdles: Marcus by Goldman Sachs provides a clean 3.40%–4.40% APY with same-day transfers and no direct deposit requirement, while Ally Bank offers 3.00% APY with advanced multi-goal savings buckets and spending roundups.
The highest APY savings yields in 2026 reach between 4.50% and 4.60% APY through online institutions such as Bask Bank and Western Alliance Bank (via Raisin). However, for maximum stability and ecosystem benefits, Marcus (up to 4.40% with referral bonus) and SoFi (up to 4.00% with direct deposit) offer superior user experiences.
Keep funds needed within 3 to 5 years (such as an emergency fund or home down payment) in an HYSA for 100% FDIC capital safety. For horizons exceeding 5 to 7 years, equities historically deliver superior compounding. Compare your options in our detailed guide on whether you should keep money in a 5% HYSA or invest in stocks.
An HYSA is an FDIC-insured bank deposit account with guaranteed capital protection up to 50,000. A money market fund (such as Vanguard VMFXX or Fidelity SPAXX) is an investment fund holding short-term government and corporate debt with SIPC coverage. While money market funds often yield competitive rates and state tax advantages, an HYSA remains the gold standard for zero-volatility emergency reserves.
No. High-yield savings accounts offer variable APYs that fluctuate with Federal Reserve interest rate benchmarks. To lock in a fixed guaranteed rate for a specified period (such as 6, 12, or 24 months), use a Certificate of Deposit (CD) or fixed-rate Treasury bills.
State Tax Tip: If you live in a high-tax state (like CA, NY, or NJ), compare Treasury Bills vs HYSA to see if state-tax-free government debt yields more net take-home cash.
Jaiveer Hooda is the Lead Financial Researcher & Personal Finance Analyst at Grow Your Money Smart. Specializing in personal wealth optimization, index fund compounding, high-yield savings mechanics, and consumer debt elimination strategies. With a background in computer engineering, he applies mathematical modeling, cashflow simulations, and empirical risk analysis to evaluate personal finance vehicles and credit products. Every analysis is backed by verified regulatory disclosures, IRS tax schedules, and empirical APY compounding math.
Areas of Expertise: Personal Finance · High-Yield Savings Accounts (HYSA) · Index Funds & S&P 500 Compounding · Retirement Planning (401k/IRA) · Debt Optimization · Credit Card APR Mechanics.
Transparency & Editorial Policy: Editorial Standards | Report a Correction