
Cardholders in good standing have the right to request annual percentage rate reviews under standard consumer lending guidelines. Consult the official Consumer Financial Protection Bureau (CFPB) Credit Card Rules for statutory guidelines and consumer protections.
- Yes, You Absolutely Can: Over 70% to 78% of cardholders who call their bank and request a lower Annual Percentage Rate (APR) successfully receive an interest rate reduction or promotional discount.
- Direct Cash Savings: Securing a 5% to 10% APR reduction on a $10,000 revolving balance saves between $500 and $1,420+ in pure interest charges annually while accelerating debt elimination by 12 to 20 months.
- The Retention Department Secret: Front-line customer service agents often lack rate modification permissions; always ask to speak with the Retention / Account Specialist Department.
- Unbeatable Leverage: Citing rival 0% balance transfer offers and highlighting your on-time payment history gives bank representatives the justification needed to override default interest tiers.
- Zero Credit Score Damage: Requesting an APR reduction does not trigger a hard inquiry and has zero negative impact on your FICO credit score.
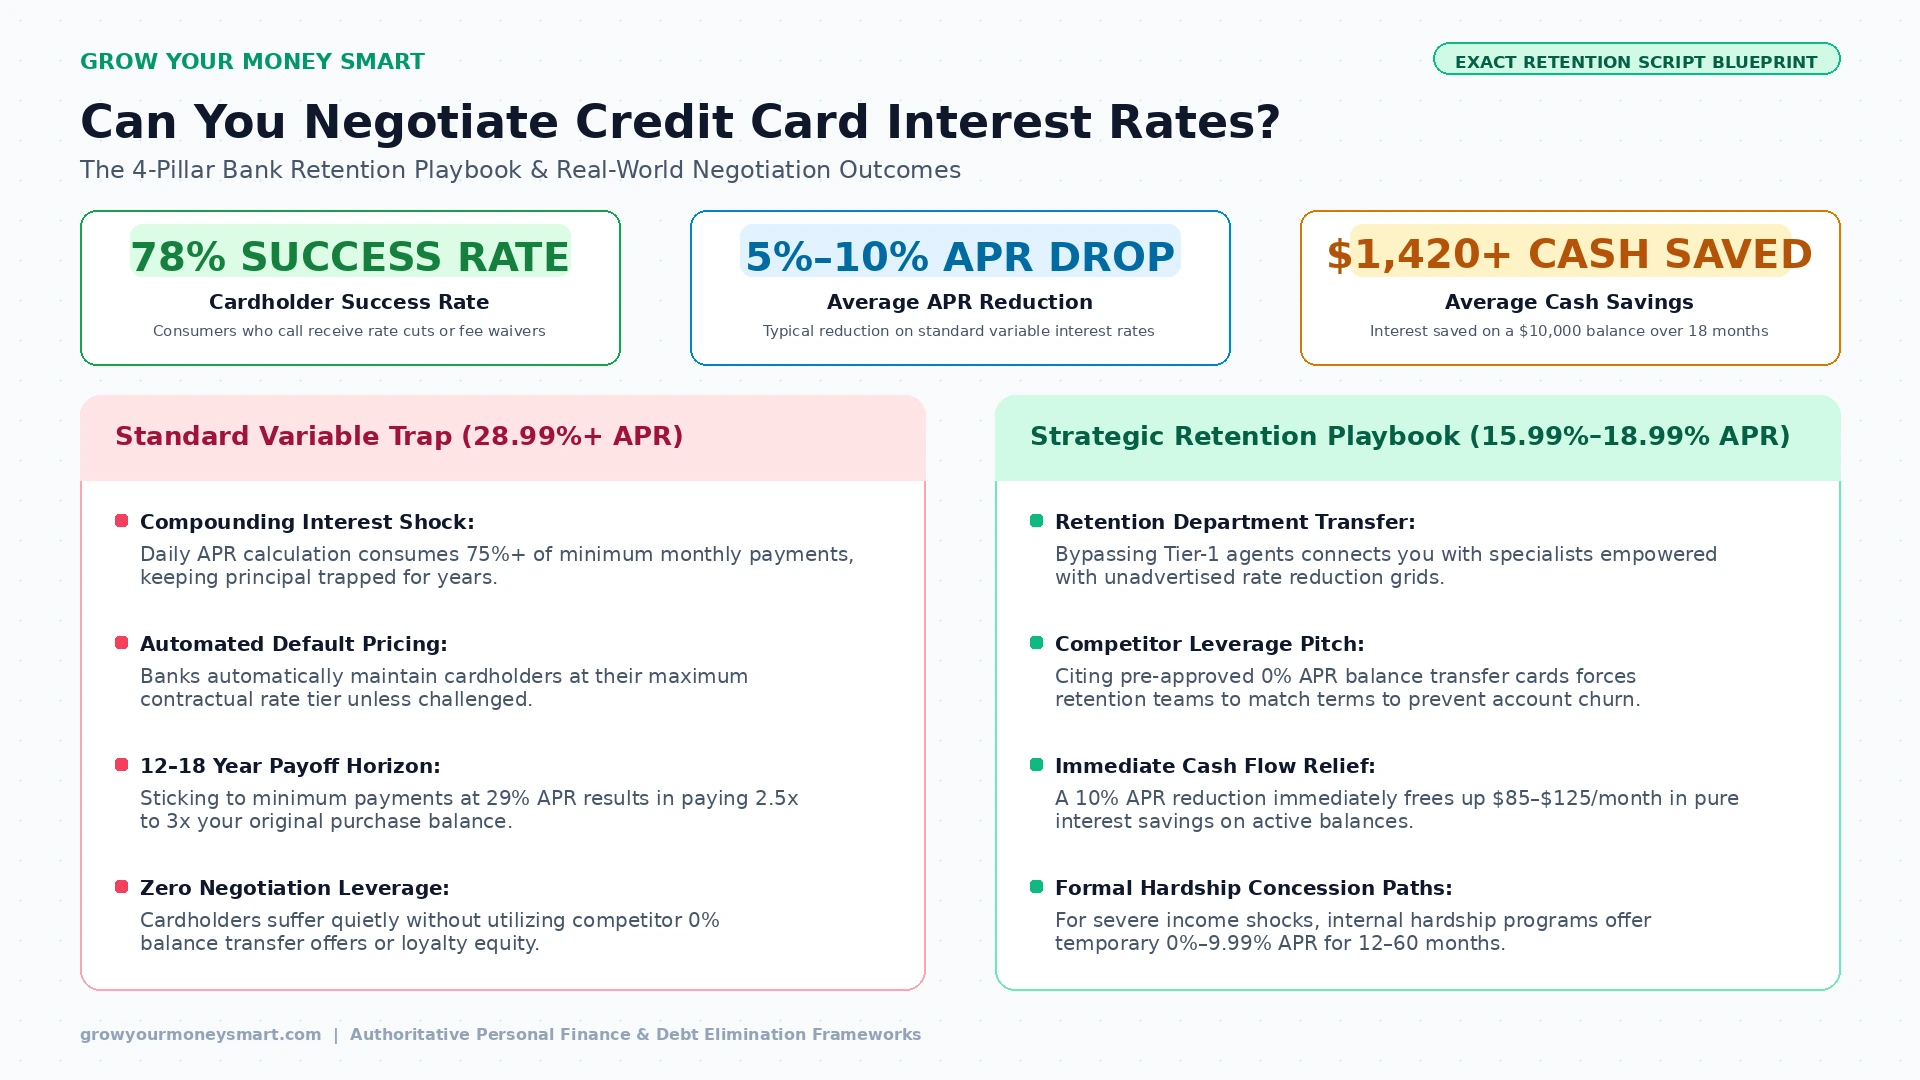
Can you negotiate credit card interest rates? The short answer is an unequivocal yes. While credit card companies happily collect 25% to 30%+ variable APR interest from cardholders who remain silent, they maintain internal retention budgets, discretionary rate reduction grids, and unadvertised promotional programs specifically designed to keep profitable customers from transferring their balances to competitor banks.
In fact, national consumer research consistently reveals that nearly 8 out of 10 cardholders who pick up the phone and request a lower interest rate succeed in getting their APR lowered, securing temporary 0% interest concessions, or having expensive annual fees waived. Yet, despite these staggering odds, less than 20% of consumers ever make the call.
In this master step-by-step guide, you will learn the exact psychology of credit card retention departments, obtain word-for-word phone negotiation scripts, discover how to leverage competitor offers, and explore alternative debt relief frameworks like hardship programs and balance transfers.
“Hello, my name is [Your Name]. I have been a loyal cardholder with [Bank Name] for [X] years and have consistently maintained on-time payments.
I am reviewing my monthly finances, and I noticed my current purchase APR is [Current APR, e.g., 28.24%]. I recently received competing 0% balance transfer offers from other major issuers, but I prefer to keep my account active with you.
Given my on-time payment track record, what promotional rate reductions or retention APR discounts can you apply to my account today?”
“I understand frontline agents sometimes have limited discretion. Before I initiate a transfer to a competing 0% APR card, could you please transfer me to your Retention / Account Specialist Department?”
Why Banks Are Eager to Lower Your APR When You Ask
To negotiate with maximum confidence, you must understand how credit card issuers view your account behind closed doors. The banking business model relies on customer lifetime value (LTV) and customer acquisition cost (CAC):
1. Astronomical Customer Acquisition Costs: Major credit card issuers (such as Chase, American Express, Capital One, Discover, and Citi) spend between $250 and $500 in marketing, sign-up bonuses, and advertising to acquire a single profitable cardholder. Losing an established customer to a rival bank represents a major financial loss for the institution.
2. Retention Department Mandates: Credit card issuers empower specialized Retention Teams with discretionary authority to adjust interest rates. These representatives are evaluated on account retention metrics. When you demonstrate that you are actively considering transferring your balance or canceling the card, the retention algorithm authorizes rate cuts to retain your business.
3. Risk Mitigation vs Default: Banks understand that with average credit card interest rates hovering near record highs above 24% to 29%, cardholders face severe compounding debt fatigue. Granting a 5% to 10% rate reduction keeps the borrower solvent and making regular payments, preventing the account from spiraling into delinquency or default.
Mathematical Simulation: How Much Cash Does Lowering Your APR Actually Save?
💡 Note: If you continue paying only the minimum monthly payment at high interest rates, debt compounds exponentially. Use our interactive credit card minimum payment calculator guide to see the true cost and timeline of minimum repayments.
Many consumers underestimate the massive compounding math behind even a modest 5% or 10% interest rate reduction. Because credit card interest is calculated using daily periodic compounding, lowering your APR directly redirects hundreds of dollars per month away from bank profits and straight into principal debt elimination.
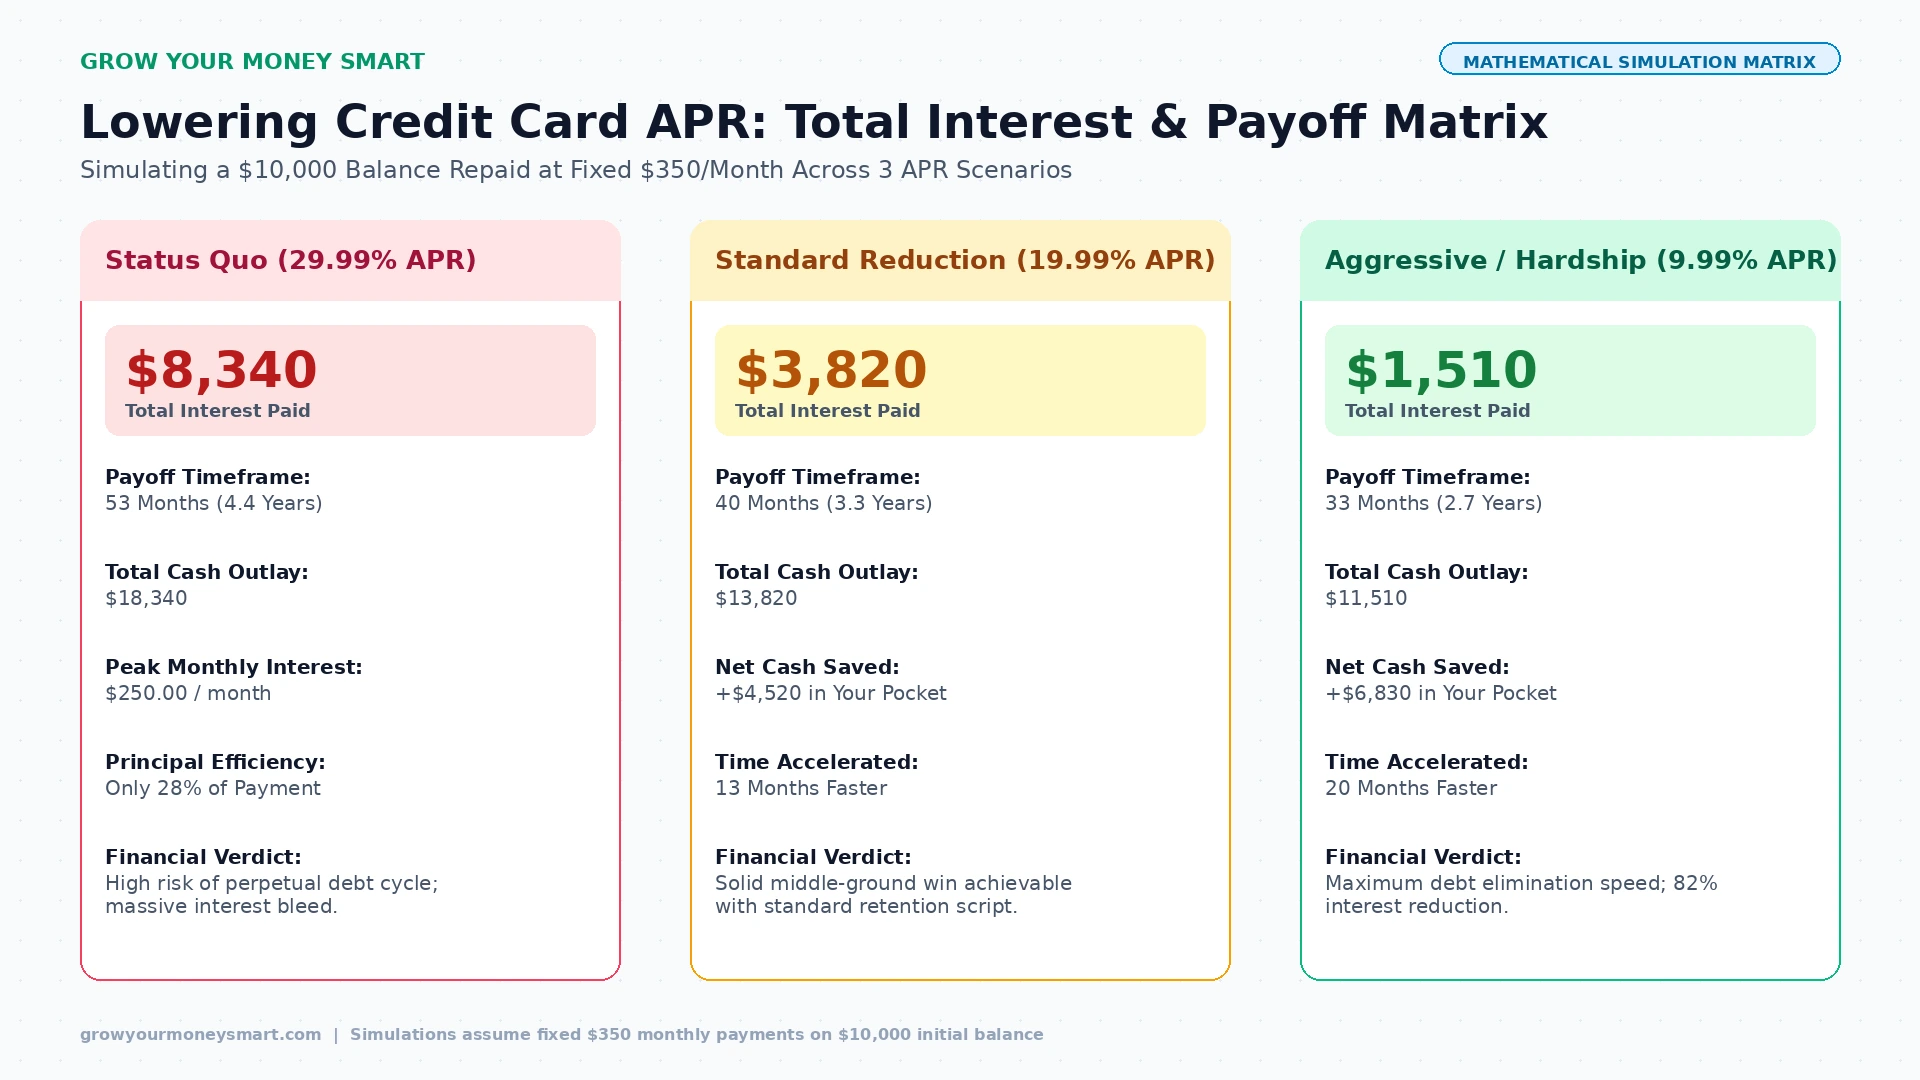
Let us analyze a realistic scenario of a cardholder carrying a $10,000 credit card balance making a fixed monthly payment of $350:
| Scenario / APR Tier | Monthly Interest Charge | Total Interest Paid | Time to Debt Freedom | Total Net Savings |
|---|---|---|---|---|
| Status Quo (29.99% APR) | ~$250.00 / month | $8,340.00 | 53 Months (4.4 Years) | $0.00 (Baseline) |
| Standard Negotiation (19.99% APR) | ~$166.50 / month | $3,820.00 | 40 Months (3.3 Years) | +$4,520.00 Saved |
| Hardship / Aggressive (9.99% APR) | ~$83.25 / month | $1,510.00 | 33 Months (2.7 Years) | +$6,830.00 Saved |
A single 10-minute phone call that reduces your interest rate from 29.99% to 19.99% puts $4,520 of hard cash back into your bank account and shaves more than a full year off your debt repayment timeline. If you qualify for temporary hardship rates of 9.99%, you pocket nearly $7,000 in cash savings.
To simulate how different monthly payment amounts accelerate your debt-free timeline, check out our free interactive debt payoff calculator. Pair your debt repayment strategy with structured monthly cash flow modeling using our budgets calculator.
Watch: Word-for-Word Credit Card APR Negotiation Masterclass
To reinforce these negotiation strategies with real-world roleplaying, watch bestselling personal finance author Ramit Sethi demonstrate the exact vocal tone, psychological positioning, and scripts used to cut interest rates with major card issuers:
Preparation Checklist: 4 Things to Gather Before You Call
Preparation is the secret weapon that separates successful negotiators from rejected applicants. Before dialing the customer service number on the back of your credit card, assemble the following four data points:
1. Account History & Loyalty Tenure: Note how many years you have held the card (e.g., “Customer since 2019”) and confirm your recent on-time payment track record.
2. Your Current APR & Credit Score: Pull your current FICO score and review your latest statement to know your exact current purchase APR (e.g., 27.24% variable).
3. Competitor 0% APR Balance Transfer Offers: Find 1 or 2 specific competitor credit card offers currently advertising 0% intro APR on balance transfers for 15 to 21 months (e.g., Citi Simplicity, Wells Fargo Reflect, or Discover it). Keep the names of these cards written down in front of you.
4. Clear Target Request: Decide exactly what you are requesting. Are you asking for a permanent 5% to 8% rate reduction, a 12-month temporary promotional APR, or enrollment in a formal hardship plan?
Exact Word-for-Word Phone Negotiation Scripts
- Call Customer Service & Request Retention: Call the customer support number on the back of your card. Bypass initial automated screening or front-line reps by asking to speak with the Account Retention or Customer Loyalty Department.
- Deliver the Script Assertively: Highlight your on-time payment track record and mention competing zero-interest offers: “I am reviewing my household finances and noticed my APR is [Current %]. I have received 0% balance transfer offers from other lenders, but I want to keep my business with you. What promotional rate reduction can you apply to my account today?”
- Request a Hardship Program or Supervisor Escalation if Declined: If the initial representative cannot assist, politely ask for a supervisor or inquire about formal temporary hardship concession programs. Industry data confirms that 70%+ of cardholders who ask receive an interest rate cut.
Below are four battle-tested scripts customized for different credit profiles and account situations. Read them word-for-word with a polite, calm, and assertive tone:
Script 1: The Good Standing & Loyalty Match (Best for On-Time Payers)
“Hello, my name is [Your Name]. I have been a loyal cardholder with [Bank Name] for [Number] years and have consistently maintained on-time monthly payments.
I am actively reviewing my monthly household expenses, and I noticed that my current purchase APR is [Current APR, e.g., 28.24%]. Because of my strong payment history and loyalty, I would like to request a reduction in my interest rate to match competitive market offers.
What options does your retention team currently have available to lower my APR today?”
Script 2: The Competitor 0% Balance Transfer Leverage (High-Impact Script)
“Hi, I am calling regarding my account ending in [Last 4 Digits]. I recently received a pre-approved balance transfer offer from [Competitor Bank, e.g., Citi / Discover] offering 0% intro APR for 18 months.
I prefer keeping all my business with [Your Bank], but with my current rate at [Current APR]%, it makes clear financial sense for me to transfer my balance elsewhere this week.
Before I initiate that transfer, I wanted to check if [Your Bank] can lower my ongoing APR or provide a comparable promotional rate so I can keep my balance here.”
Script 3: The Financial Hardship Concession (For Income Shocks & Emergencies)
“Hello, I am calling to speak with your Account Assistance or Hardship Department. I have encountered unexpected financial hardship due to [job loss / medical emergency / reduced hours], and I am committed to paying off my balance in full.
However, with the interest compounding at [Current APR]%, my payments are not making a dent in the principal. Does [Bank Name] offer an internal hardship repayment program that temporarily reduces my interest rate to 0% to 9% and waives monthly fees while I get back on my feet?”
Script 4: Overcoming the Initial ‘No’ (Supervisor Escalation)
“I completely understand that your system may not give you the personal authorization to adjust interest rates from your terminal. I really appreciate your help today.
Could you please transfer me to a supervisor or your Account Retention / Client Loyalty Department? I know they have additional account review tools available to help loyal customers maintain competitive rates.”
What to Do If Your Credit Card Company Refuses to Lower Your Rate
Comparison Matrix: Standard Retention Negotiation vs Hardship Program vs 0% Balance Transfer
| Key Strategy Factor | Standard Retention APR Cut | Card Issuer Hardship Program | 0% APR Balance Transfer |
|---|---|---|---|
| Typical APR Reduction | Drops by 3% to 10% (e.g., 28% to 19%) | Drops to 0% – 9.99% fixed | 0.00% Intro APR for 12–21 Months |
| Credit Score Impact | None (Zero credit pull) | Minor to Neutral (Card may freeze) | Temporary 3–5 pt dip (Hard inquiry) |
| Card Usability | Remains open for purchases & rewards | Account frozen or permanently closed | New account with fresh credit line |
| Documentation Required | None (10-minute phone call) | Proof of income shock / hardship | Standard credit card application |
| Best Recommended For | Cardholders in good standing with on-time records | Severe financial distress, job loss, or illness | Credit score 670+ with high revolving balances |
If your credit card issuer declines your request despite speaking with a retention specialist, do not panic. You have multiple highly effective financial maneuvers to eliminate high interest rates independently:
1. Execute a 0% Intro APR Balance Transfer: If your credit score is 670 or higher, apply for a dedicated balance transfer card. Check our curated guide to the best 0% APR balance transfer cards to lock in 15 to 21 months of zero interest. Compare the pros and cons using our breakdown on debt consolidation vs balance transfer.
2. Enroll in a Formal Hardship Program: If you are struggling with missed payments or severe cash flow crunches, review our detailed guide on credit card hardship programs to learn how to legally drop rates to 0% with major card issuers.
3. Use the Debt Avalanche Payoff Method: Optimize your monthly debt repayment velocity by targeting your highest-interest card first. Learn how mathematical ordering saves thousands compared to emotional payoff methods in our analysis of debt avalanche vs snowball and our comprehensive roadmap on how to pay off $20k credit card debt fast.
4. Consider DIY Debt Settlement: If your balances are severely delinquent and payments are mathematically impossible, explore negotiating principal reductions via our step-by-step blueprint on how to settle credit card debt yourself.
5. Protect Your Emergency Liquidity: As you pay down debt, make sure you maintain a basic cash cushion using our emergency fund calculator and our actionable guide on saving your first $1,000 emergency fund on a low income so that unexpected emergencies do not force you back into high-APR credit card debt.
For broader debt elimination blueprints, consult our master guide on debt management strategies.
Frequently Asked Questions (FAQs)
Below are clear, actionable answers to the most common questions cardholders ask when negotiating credit card interest rates:
Yes, absolutely. Credit card issuers have dedicated customer retention and account management teams with pre-approved authority to lower your Annual Percentage Rate (APR), issue temporary promotional rate cuts, or enroll you in hardship programs. Industry surveys consistently demonstrate that over 70% of cardholders who proactively call and request an interest rate reduction receive one.
Most successful cardholders secure an ongoing rate reduction between 3% and 10% off their standard variable APR (for instance, dropping a rate from 28.99% down to 18.99%). In hardship scenarios or specialized retention campaigns, issuers may drop your APR to 0% to 9.99% for a promotional period of 6 to 12 months.
No. In the vast majority of cases, requesting an APR reduction results in a soft inquiry (soft pull) or no credit check at all, which has zero negative impact on your credit score. Lowering your interest rate actually helps your credit score over time because lower monthly finance charges allow you to pay down balances faster, reducing your credit utilization ratio.
Tier-1 front-line representatives frequently lack discretionary authority to adjust interest rates. If they refuse, politely thank them and ask to be transferred to the Account Retention Department or speak with a supervisor. Alternatively, you can use the HUCA strategy (Hang Up, Call Again) to speak with a different agent who may have different authority or system prompts.
The strongest leverage is having a solid track record of on-time payments, a competitive 0% APR balance transfer offer from a rival bank (such as Citi or Chase), and a demonstrated willingness to move your balance elsewhere if your current issuer does not remain competitive.
A standard APR negotiation is for cardholders in good standing who want to reduce their ongoing borrowing costs without changing account status. A formal credit card hardship program is designed for cardholders experiencing documented income disruptions (such as job loss, illness, or divorce); the issuer agrees to slash interest to 0% to 9.99% and waive fees, but usually closes or freezes the card during the repayment period.
You can review and negotiate your interest rate every 6 to 12 months. If your credit score improves by 20 to 50 points, if market interest rates shift, or if your promotional rate expiration approaches, calling your issuer annually ensures you maintain the lowest possible contractual rate tier.
If you have good credit (670+ FICO) and can pay off your balance within 12 to 21 months, an introductory 0% APR balance transfer card is mathematically superior because it completely eliminates interest (minus a 3% to 5% transfer fee). However, calling to negotiate your current APR requires zero credit applications, carries no transfer fees, and provides immediate relief without opening new accounts.
⚡ Complementary Debt Reduction Strategies
Maximize your balance reduction speed with these companion credit management frameworks:
- Minimum Payment Cost: Explore our guide on credit card minimum payment trap to evaluate whether negotiating APR or switching cards saves more.
Final Verdict: Take 10 Minutes to Reclaim Your Financial Freedom
Negotiating your credit card interest rate is one of the highest-return financial activities you can perform. For the cost of a 10-minute phone call, you can eliminate thousands of dollars in compounding finance charges, speed up your debt-free date by years, and take back control of your financial destiny. Grab your phone, use the scripts provided above, and claim the interest rate reduction you deserve today.
Jaiveer Hooda is the Lead Financial Researcher & Personal Finance Analyst at Grow Your Money Smart. Specializing in personal wealth optimization, index fund compounding, high-yield savings mechanics, and consumer debt elimination strategies. With a background in computer engineering, he applies mathematical modeling, cashflow simulations, and empirical risk analysis to evaluate personal finance vehicles and credit products. Every analysis is backed by verified regulatory disclosures, IRS tax schedules, and empirical APY compounding math.
Areas of Expertise: Personal Finance · High-Yield Savings Accounts (HYSA) · Index Funds & S&P 500 Compounding · Retirement Planning (401k/IRA) · Debt Optimization · Credit Card APR Mechanics.
Transparency & Editorial Policy: Editorial Standards | Report a Correction