
- The 0% APR Arbitrage: A 0% introductory APR balance transfer card acts as a total interest freeze for 15 to 21 months, directing 100% of your monthly payment toward reducing principal rather than bank interest.
- Massive Interest Savings: Transferring a $10,000 balance from an average 24.5% APR credit card to an 18-month 0% card saves over $2,640 to $3,200 in net interest, even after factoring in standard 3% to 5% upfront transfer fees.
- Top 2026 Market Leaders: The Wells Fargo Reflect® Card and Citi Simplicity® Card deliver the longest 0% APR windows (up to 21 months), while the BankAmericard® Credit Card provides a competitive low 3% intro fee window.
- The Same-Issuer Rule: You cannot transfer debt between cards issued by the same banking institution (e.g., Chase to Chase or Citi to Citi). Transfers must occur between different lending entities.
- Flawless Payoff Execution: Divide your total transferred balance by the promotional months (e.g., $9,000 / 18 months = $500/mo) and automate fixed monthly payments to hit a zero balance before the promo APR expires.
With total American consumer credit card balances surpassing $1.14 trillion and national average credit card interest rates climbing to a staggering 24.5% APR in 2026, carrying revolving card debt has never been more punishing. When you are stuck paying 24% to 29% interest, over 80% of your monthly payment is devoured by finance charges, barely chipping away at the actual debt you owe.
Opening one of the best 0% APR balance transfer cards is the single most powerful mathematical weapon available to pause compounding interest. By migrating your existing high-interest balances to a card offering 0.00% introductory APR for 12, 18, or up to 21 months, you execute a financial circuit breaker. Every single dollar you pay during the promotional window directly eliminates your principal debt balance.
However, balance transfers are not magic—they are precision financial instruments. If you do not understand the upfront transfer fees, promotional time limits, and issuer transfer restrictions, you risk falling right back into costly interest traps. In this comprehensive 2026 guide, we analyze the top balance transfer cards on the market, break down the exact payoff mathematics, evaluate pros and cons, and deliver an actionable 5-step blueprint to wipe out credit card debt for good.
The Wells Fargo Reflect® Card and Citi Simplicity® Card stand as the best overall 0% APR balance transfer credit cards of 2026, offering up to 21 months of 0% intro APR on qualifying balance transfers. For consumers seeking lower transfer costs, the BankAmericard® delivers an industry-low 3% intro transfer fee window.
Choose your debt payoff strategy below to skip lengthy bank terms and jump directly to full card breakdowns:
- Transfer Fee: 5% (min )
- Annual Fee: bash intro & ongoing
- Best For: High balances (,000+) needing the longest runway to hit debt freedom.
- Transfer Fee: 3% intro fee (first 60 days)
- Fee Savings: Saves 00+ on a 0k transfer vs 5% fee cards
- Best For: Borrowers prioritizing low upfront transfer costs with 1.5 years zero interest.
- Transfer Fee: 3% intro fee (first 60 days)
- Ongoing Value: 1.5% to 5% cash back + 00 bonus
- Best For: Moderate balances (.5k–k) that can be cleared in 15 months while earning daily cash.
How 0% APR Balance Transfers Work: The Financial Mechanics & Fine Print
A balance transfer is a transaction where a new credit card issuer pays off the existing debt on one or more of your external credit cards or personal loans. The new issuer then adds that total balance to your new card account, charging an introductory 0.00% APR for a predetermined promotional period.
To master this financial maneuver, you must understand the four structural pillars governing balance transfers:
1. The Upfront Balance Transfer Fee: Nearly all prime credit cards charge an upfront balance transfer fee of 3% to 5% of the total amount transferred (with a typical minimum of $5 to $10). For example, transferring $8,000 at a 3% fee adds an immediate $240 to your starting balance ($8,240 total). While nobody likes fees, paying a one-time $240 fee is infinitely cheaper than paying over $1,600 in annual compounding interest on a 24.5% APR card.
2. The Strict Transfer Request Window: Most issuers require you to initiate balance transfers within a specific window after opening the account—typically 45 to 120 days from approval. If you request a transfer after this deadline, the promotional 0% APR will no longer apply, and standard purchase rates will kick in immediately.
3. True 0% Intro APR vs. Predatory Deferred Interest: Major bank cards (like Wells Fargo, Citi, Bank of America, and Discover) offer true 0% intro APR. This means if you still have a $500 balance when the 21-month promo ends, you only pay ongoing interest on that remaining $500. This is fundamentally different from predatory retail store cards offering “deferred interest,” where failing to pay the entire balance by day 1 retroactively charges you interest on the full original balance back to day one!
4. Same-Bank Transfer Restrictions: Card issuers utilize balance transfers as customer acquisition tools to capture balances from rival banks. Consequently, you cannot transfer debt between cards issued by the exact same bank. You cannot transfer a Chase Sapphire balance to a Chase Freedom, nor a Citi Double Cash balance to a Citi Simplicity. You must transfer across unaffiliated banking institutions.
Which Credit Cards Offer 0% Interest for 21 Months in 2026?
The top credit card 0 interest 21 months options currently leading the market are the Wells Fargo Reflect® Card (up to 21 months 0% intro APR on qualifying balance transfers and purchases) and the Citi Simplicity® Card (21 months 0% intro APR on balance transfers, with no late fees and no penalty APR). Both cards provide the longest zero-interest runways in the industry to consolidate high-interest card debt.
To evaluate whether a credit card promo or a fixed installment loan is best for your balance, see our in-depth guide on debt consolidation vs balance transfer, and calculate your required monthly payoff target with our free debt payoff calculator.
Best 0% Balance Transfer Cards with Low or Zero Transfer Fees in 2026
While standard commercial balance transfer cards impose an upfront 3% to 5% transfer fee (e.g., $300 to $500 on a $10,000 balance), savvy borrowers can minimize or completely eliminate this cost by targeting specialized card structures:
- Introductory 3% Fee Cards: The BankAmericard® Credit Card provides a promotional 3% balance transfer fee (minimum $10) for transfers completed within the first 60 days, compared to the 5% fee charged by most competitors.
- Credit Union $0 Transfer Fee Options: Institution cards like the Navy Federal Credit Union Platinum Card and select federal credit union offerings provide 0% APR promotional periods with $0 balance transfer fees. Eligibility requires military affiliation or credit union membership.
- Cost-Benefit Rule: If you are transferring $15,000+, saving a 5% fee ($750) through a credit union card significantly outperforms a slightly longer 0% window on a 5% fee card.
The 6 Best 0% APR Balance Transfer Cards of 2026: Detailed Reviews
After evaluating promotional length, balance transfer fees, annual fees, post-promotional regular APRs, and cardholder terms across dozens of financial institutions, here are the top 6 balance transfer credit cards ranked for 2026:
1. Wells Fargo Reflect® Card – Longest Overall 0% APR Window
The Wells Fargo Reflect® Card stands as the reigning heavyweight champion for consumers who need the longest possible runway to extinguish substantial credit card balances.
- 0% Intro APR Period: Up to 21 months 0% intro APR from account opening on qualifying balance transfers and purchases.
- Balance Transfer Fee: 5% (minimum $5) on transfers made within 120 days of account opening.
- Annual Fee: $0.
- Regular APR: 17.49% to 29.49% Variable APR following the promotional window.
- Standout Perk: Up to $600 of cell phone protection against damage or theft when you pay your monthly wireless bill with the card (subject to a $25 deductible).
- Best For: Borrowers tackling large balances ($10k+) who prioritize maximum time over lower upfront transfer fees.
2. Citi Simplicity® Card – Ultimate No-Fee Safety Net
If you fear unexpected life disruptions or accidental slip-ups during your debt payoff journey, the Citi Simplicity® Card offers unmatched forgiving terms with zero late fees and no penalty APRs.
- 0% Intro APR Period: 21 months 0% intro APR on balance transfers (completed within 4 months of account opening) and 12 months on purchases.
- Balance Transfer Fee: Intro fee of 3% (min $5) on transfers completed within the first 4 months; after that, 5% (min $5).
- Annual Fee: $0.
- Late Payment Penalties: $0 late fees, $0 penalty APR, and zero annual fee—ever.
- Regular APR: 18.49% to 29.24% Variable APR.
- Best For: Anyone seeking extended 21-month debt relief with built-in protection against accidental late fees.
3. BankAmericard® Credit Card – Best Low 3% Intro Transfer Fee
Many 21-month cards charge a steep 5% balance transfer fee. The BankAmericard® Credit Card strikes the perfect balance by offering a generous 18 billing cycle window paired with a lower 3% transfer fee.
- 0% Intro APR Period: 18 billing cycles 0% intro APR on qualifying balance transfers and purchases.
- Balance Transfer Fee: 3% (minimum $10) for transfers completed within the first 60 days of account opening.
- Annual Fee: $0.
- Regular APR: 15.49% to 25.49% Variable APR (notably lower starting baseline than competitors).
- Best For: Borrowers who can comfortably clear their debt in 18 months and want to save 2% upfront on transfer fees ($200 saved per $10,000 transferred).
4. Citi® Diamond Preferred® Card – Consistent Extended Zero-Interest Period
The Citi® Diamond Preferred® Card provides an extended 21-month 0% intro APR window specifically designed for debt consolidation and major planned expenditures.
- 0% Intro APR Period: 21 months on balance transfers (completed within first 4 months) and 12 months on purchases.
- Balance Transfer Fee: 5% ($5 minimum).
- Annual Fee: $0.
- Regular APR: 17.49% to 28.24% Variable APR.
- Standout Perk: Access to Citi Entertainment® for exclusive presale ticket access to concerts and sporting events.
- Best For: Dedicated balance transfer consolidators seeking long-term interest relief.
5. Discover it® Balance Transfer – Generous Intro APR + Cash Back Rewards
Most dedicated balance transfer cards offer zero rewards. The Discover it® Balance Transfer card breaks the mold by pairing an 18-month 0% promo with an aggressive 5% cash back rotating rewards program.
- 0% Intro APR Period: 18 months 0% intro APR on balance transfers; 6 months on purchases.
- Balance Transfer Fee: 3% intro fee up to a specified date, then up to 5% on future transfers.
- Annual Fee: $0.
- Ongoing Rewards: 5% cash back on rotating quarterly categories (up to $1,500 quarterly spend upon enrollment) and 1% unlimited cash back on all other purchases.
- Cashback Match™: Discover automatically matches 100% of all cash back earned at the end of your first year.
- Best For: Consumers who want long-term card utility and cash back rewards after their debt balance is paid off.
6. Chase Freedom Unlimited® – Top Everyday Rewards + 15-Month 0% APR
If your balance is moderate and can be paid off within 15 months, the Chase Freedom Unlimited® is arguably the best long-term wallet keeper in the financial industry.
- 0% Intro APR Period: 15 months 0% intro APR on purchases and balance transfers.
- Balance Transfer Fee: Intro fee of 3% (minimum $5) for transfers made within the first 60 days; after that, 5% ($5 min).
- Annual Fee: $0.
- Ongoing Rewards: 5% on travel booked through Chase Travel, 3% on dining and drugstores, and 1.5% unlimited cash back on all general spending.
- Best For: Borrowers with under $6,000 in debt who want an industry-leading everyday rewards card once debt-free.
Head-to-Head Comparison Matrix: Top 0% Balance Transfer Cards of 2026
Compare the core terms, transfer windows, upfront fees, and standout features of the top balance transfer credit cards side by side in the matrix below:
| Credit Card Name | 0% Intro APR (Transfers) | Balance Transfer Fee | 0% Intro APR (Purchases) | Regular Post-Promo APR | Annual Fee | Primary Advantage |
|---|---|---|---|---|---|---|
| Wells Fargo Reflect® Card | Up to 21 Months | 5% (min $5) | Up to 21 Months | 17.49% – 29.49% | $0 | Maximum 21-month runway + Cell phone insurance |
| Citi Simplicity® Card | 21 Months | 3% intro (first 4 mos), then 5% | 12 Months | 18.49% – 29.24% | $0 | Zero late fees & no penalty APR safety guarantee |
| BankAmericard® Card | 18 Billing Cycles | 3% (min $10, first 60 days) | 18 Billing Cycles | 15.49% – 25.49% | $0 | Lowest upfront 3% fee across 18 billing cycles |
| Citi® Diamond Preferred® | 21 Months | 5% (min $5) | 12 Months | 17.49% – 28.24% | $0 | Extended 21 months + Citi Entertainment® perks |
| Discover it® Balance Transfer | 18 Months | 3% intro, then up to 5% | 6 Months | 16.49% – 27.49% | $0 | 5% rotating cash back + First-year Cashback Match™ |
| Chase Freedom Unlimited® | 15 Months | 3% intro (first 60 days), then 5% | 15 Months | 19.24% – 27.99% | $0 | 3%–5% ongoing cash back for long-term utility |
Mathematical Simulation: $10,000 Balance Transfer vs. Compounding 24.5% APR
To truly understand why a 0% APR balance transfer card is transformative, let’s examine the cold, hard numbers. In this scenario, Sarah carries $10,000 in revolving credit card debt across two cards with an aggregate interest rate of 24.5% APR.
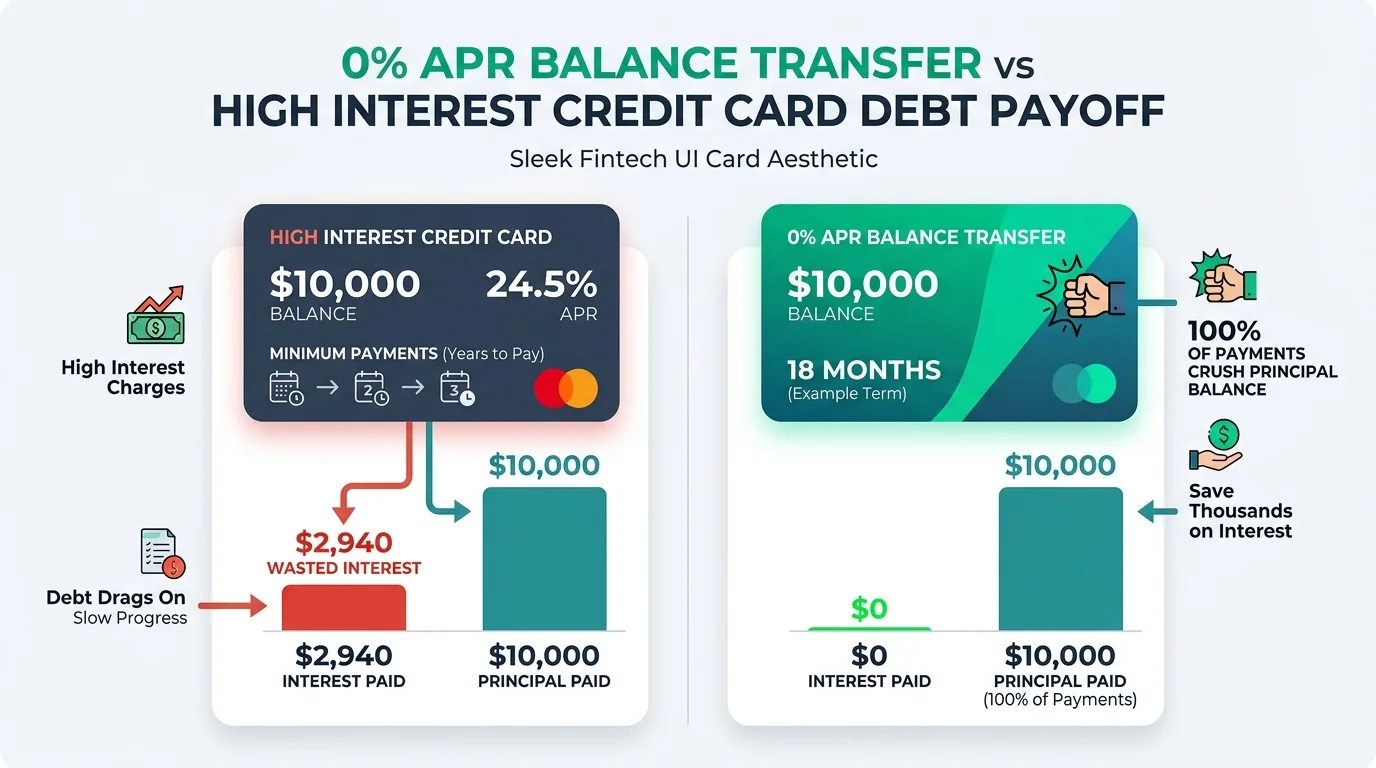
Review the exact financial breakdown comparing three different payoff strategies on her $10,000 debt:
| Payoff Strategy | Monthly Payment | Time to $0 Debt | Total Interest Paid | Upfront Fees | Total Out-of-Pocket Cost |
|---|---|---|---|---|---|
| Scenario A: Minimum Payments (24.5% APR) | ~$250 (declining) | 21.8 Years (262 mos) | $14,380 | $0 | $24,380 |
| Scenario B: Fixed $572/mo (24.5% APR) | $572.22 | 23 Months | $2,642 | $0 | $12,642 |
| Scenario C: 18-Month 0% APR Transfer (3% Fee) | $572.22 | 18 Months | $0.00 | $300 | $10,300 |
The Mathematical Verdict: By transferring her $10,000 balance to an 18-month 0% APR card with a 3% transfer fee ($300 upfront), Sarah commits $572.22 per month. In exactly 18 months, she is 100% debt-free, paying $0 in interest charges and saving $2,342 in pure cash compared to making the exact same monthly payment on her existing card! You can calculate your own customized scenario using our interactive debt payoff calculator.
The 5-Step Balance Transfer Blueprint: How to Execute with Zero Errors
Executing a balance transfer requires strict procedural discipline. Follow this proven 5-step blueprint to ensure seamless approval, zero missed deadlines, and total debt elimination:
Step 1: Audit Balances, Interest Rates & Check Your Credit Score
Gather your recent billing statements for all credit cards carrying balances. Note the exact balance, APR, and issuing bank for each. Before applying for a new card, try negotiating lower credit card interest rates directly with your bank using our phone script. Check your credit score (via free credit monitoring apps or your current banking app). You will generally need a FICO score of 670 or higher to qualify for top-tier 18- to 21-month balance transfer offers. For more broader recovery techniques, explore our master guide on debt management strategies.
Step 2: Choose an Unaffiliated Card Issuer & Apply
Ensure the target balance transfer card is issued by a different bank than your current debt. If you owe money on a Chase card, apply for a Wells Fargo, Citi, or Bank of America card. During the online application, you will often be given the option to input the account numbers and requested transfer amounts for your existing debts right away.
Step 3: Calculate Your Required Monthly Payoff Target
Once approved and your transfer limit is established, take your total transferred balance (including the 3%–5% transfer fee) and divide it by the number of promotional months minus one month as a safety buffer. For example, if you transfer $7,200 to an 18-month card, divide by 17 months:
Target Monthly Payoff: $7,200 / 17 months = $423.53 per month
This ensures your debt hits $0.00 a full 30 days before the promotional rate expires, completely shielding you from post-promo interest rates. Map out your exact debt-free date before your 0% promotional APR window expires with our interactive debt payoff calculator. Integrate this payment into your monthly spending plan using our free budgets calculator.
Step 4: Continue Paying Your Old Accounts Until the Transfer Clears
Balance transfers do not happen instantaneously—they typically take 5 to 14 business days to finalize. Do not stop making scheduled minimum payments on your old cards. Missing a payment while waiting for a balance transfer to process will incur late fees and damage your credit report. Only stop payments once you log into the old account and verify a confirmed $0.00 balance.
Step 5: Lock Away the New Card & Build an Emergency Buffer
Do not use your new balance transfer card for everyday spending or dining out. Mixing new purchases with transferred debt complicates payment allocation and risks inflating your debt burden. Simultaneously, channel a modest $1,000 into a liquid account to protect against unexpected repairs—you can test targets with our emergency fund calculator so you never have to swipe a credit card during emergencies again.
Expert Video Walkthrough: How Credit Card Balance Transfers Work
Watch this authoritative video breakdown from NerdWallet explaining the precise mechanics of balance transfers, how to avoid hidden fee traps, and how to maximize your credit score recovery during the payoff window:
Debt Consolidation Loan vs. 0% APR Balance Transfer: Which Saves More Money?
When evaluating debt consolidation loans vs. 0% APR balance transfer credit cards, the total cost depends entirely on your repayment velocity and total balance. Below is the direct mathematical cost comparison for paying off a $10,000 balance:
| Metric ($10,000 Debt) | 0% APR Balance Transfer Card | Debt Consolidation Personal Loan |
|---|---|---|
| Interest Rate | 0.00% Intro APR (18-21 Mos) | Fixed 9.99% – 14.99% APR |
| Upfront Fees | $300 (3% Transfer Fee) | $0 – $300 (0-3% Origination Fee) |
| Total Interest Paid | $0 (if cleared in promo) | $1,616 (at 10% APR over 36 mos) |
| Total Cost of Payoff | $10,300 total | $11,616 total |
| Net Financial Savings | 0% Card Saves $1,316 over a 3-Year Loan | |
When seeking relief from mounting credit card bills, consumers frequently debate between applying for a 0% APR balance transfer card or securing a fixed-rate debt consolidation personal loan. If you are unsure whether a card promotion or a fixed installment loan fits your situation better, review our balance transfer vs debt consolidation loan comparison. Review the side-by-side comparison below to choose the right financial path:
| Evaluation Criteria | 0% APR Balance Transfer Card | Fixed-Rate Personal Loan |
|---|---|---|
| Interest Rate (APR) | 0.00% APR for 12–21 months | Fixed 7.99% – 15.99% APR |
| Upfront Costs / Fees | 3% to 5% Balance Transfer Fee | 0% to 6% Origination Fee |
| Repayment Term Structure | Flexible monthly payments (must clear within promo) | Fixed monthly installment over 24 to 60 months |
| Ideal Debt Amount | $2,000 to $15,000 | $15,000 to $50,000+ |
| Credit Score Requirement | 670+ (Good to Excellent FICO) | 600+ (Fair to Excellent) |
| Best Strategic Fit | Aggressive payoff sprints within 18 months | Longer, lower-stress structured multi-year payoffs |
If you have substantial high-interest debt exceeding $20,000, read our in-depth tactical guide on how to pay off $20k credit card debt fast, or compare strategies in our analysis of debt-free living vs leverage strategies. If you are struggling with severe unmanageable balances, you may also review our guide on how to settle credit card debt yourself or consult a certified professional via DIY finance vs hiring a financial advisor.
Frequently Asked Questions (FAQs)
Opening a balance transfer card causes a minor, temporary 3 to 5 point dip due to the hard credit inquiry. However, within 1 to 3 billing cycles, your overall credit score typically surges higher because your aggregate credit limit expands, significantly reducing your total credit utilization ratio—one of the largest factors in your FICO score.
No. Credit card issuers strictly prohibit balance transfers between their own internal accounts (for example, transferring debt from one Chase card to another Chase card, or Citi to Citi). You must transfer debt to a card issued by an unaffiliated lending institution (such as moving a Capital One balance to a Wells Fargo or Citi card).
Unlike retail store cards with predatory ‘deferred interest’, major bank 0% APR balance transfer cards only charge ongoing interest on the remaining unpaid principal balance once the promo window expires. However, the regular post-promotional variable APR (typically 19% to 29.99%) will apply immediately to whatever balance remains.
Yes. Your total balance transfer cannot exceed the credit limit assigned to your new card, minus the required balance transfer fee (typically 3% to 5%). For example, if approved for an $8,000 credit limit with a 3% transfer fee, the maximum debt you can transfer is approximately $7,766.
Unless the card specifically offers a matching 0% introductory APR on new purchases for the exact same timeframe, you should strictly avoid making new purchases. New purchases may immediately accrue interest at the regular variable APR and complicate how monthly payments are allocated across promotional vs non-promotional balances.
Most prime balance transfer cards offering 18 to 21 months of 0% APR require a Good to Excellent FICO credit score (670 to 740+). Applicants with scores in the fair range (580 to 669) may still qualify for balance transfer cards from certain credit unions, but promotional windows are generally shorter (6 to 12 months).
A 0% balance transfer card is vastly superior if you have good credit (670+) and can aggressively pay off the entire balance within 12 to 21 months, yielding a true 0.00% interest cost (aside from the 3%–5% upfront fee). A personal loan is better suited if you owe a massive balance ($25,000+) requiring a longer 36 to 60 month structured payoff runway at a fixed 8% to 14% APR.
Balance transfers typically take between 5 to 14 business days to process and disburse funds to your old creditor. You must continue making on-time minimum payments on your old accounts until you verify that the previous balance reflects exactly $0.00 to avoid late fees and penalty APRs.
Under the CARD Act of 2009, promotional 0% APR windows must remain in effect for at least 6 months, and fee structures must be clearly disclosed. Consult the official Consumer Financial Protection Bureau (CFPB) Credit Cards Guidance for statutory guidelines and consumer protections.
⚡ Next-Step Debt Elimination & Relief Blueprints
If a 0% balance transfer card is not sufficient to clear your balance, explore these alternative relief strategies:
- Credit Card Math Trap: credit card minimum payment calculator and true interest cost discovering how 2% minimum payments double your total payoff cost.
- Hardship Rate Reductions: credit card hardship programs to slash APR to 0% negotiating internal workout plans directly with your card issuers.
- Direct Settlement: how to settle credit card debt yourself without debt agencies securing 40% to 60% balance forgiveness.
- Consolidation Alternative: debt consolidation loan vs balance transfer cards comparing fixed installments against promotional 0% windows.
How to negotiate a lower credit card interest rate before transferring a balance?
Call your credit card issuer’s customer retention department and request an APR reduction based on your on-time payment history and competing 0% APR balance transfer offers. Many major card issuers will reduce APRs by 3% to 8% or offer temporary hardship rates without requiring an upfront transfer fee.
Are there 0% APR balance transfer credit cards with zero transfer fees in 2026?
While national commercial banks (Wells Fargo, Citi, Discover) charge standard 3% to 5% balance transfer fees, select credit unions such as Navy Federal Credit Union (Platinum Card) and Wings Financial Credit Union offer true 0% balance transfer cards with $0 balance transfer fees for eligible members.
Can I defer credit card payments without paying interest?
Yes. Transferring your high-interest credit card balance to a 0% introductory APR balance transfer card legally freezes all interest charges for 15 to 21 months. You must still make the monthly minimum payment (typically 1% to 2% of the balance), but 100% of that payment goes directly toward reducing your principal.
What is the difference between debt settlement and a 0% balance transfer card?
Debt settlement negotiates a lump-sum payoff for 40% to 60% of your balance, which requires defaulting on accounts and causes severe, multi-year damage to your credit score. A 0% balance transfer card preserves your credit health, eliminates interest charges for up to 21 months, and improves your credit score as you pay down principal.
Jaiveer Hooda is the Lead Financial Researcher & Personal Finance Analyst at Grow Your Money Smart. Specializing in personal wealth optimization, index fund compounding, high-yield savings mechanics, and consumer debt elimination strategies. With a background in computer engineering, he applies mathematical modeling, cashflow simulations, and empirical risk analysis to evaluate personal finance vehicles and credit products. Every analysis is backed by verified regulatory disclosures, IRS tax schedules, and empirical APY compounding math.
Areas of Expertise: Personal Finance · High-Yield Savings Accounts (HYSA) · Index Funds & S&P 500 Compounding · Retirement Planning (401k/IRA) · Debt Optimization · Credit Card APR Mechanics.
Transparency & Editorial Policy: Editorial Standards | Report a Correction