
- Definition: An investment time horizon is the total length of time you plan to hold an investment portfolio before needing to liquidate funds.
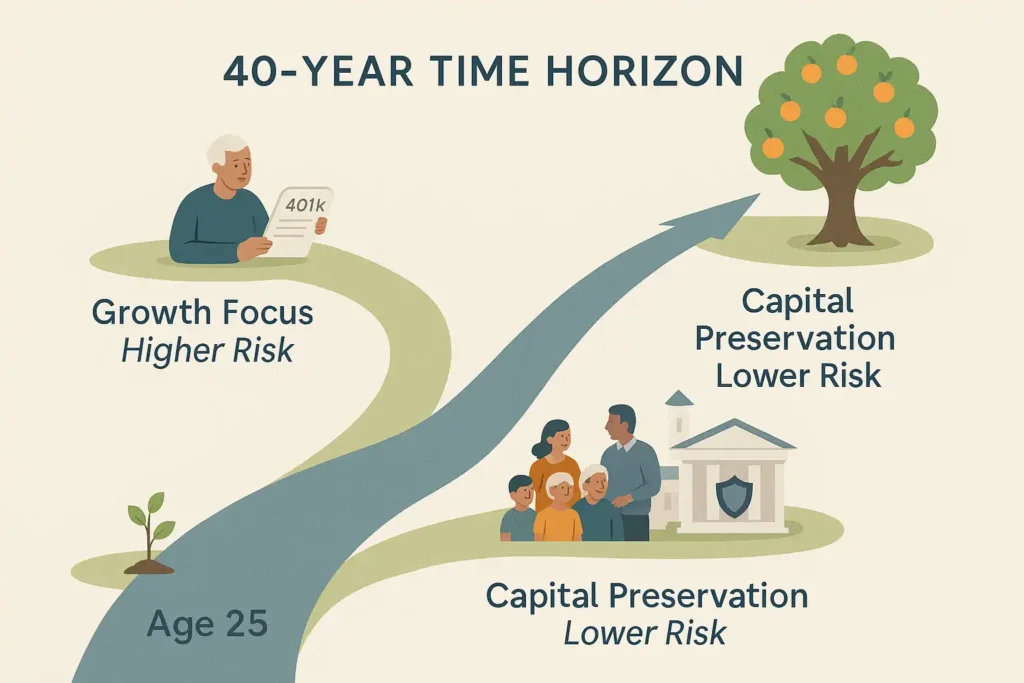
- Short-Term (0–3 Years): Prioritize Capital Preservation. Optimal vehicles: High-Yield Savings Accounts (HYSA), Treasury Bills (T-Bills), and Liquid Debt Funds. 0% direct equity exposure.
- Medium-Term (3–7 Years): Focus on Balanced Growth. Typical allocation: 40–60% fixed income/debt and 40–60% large-cap/index equities.
- Long-Term (7+ to 10+ Years): Maximize Compound Growth. Target allocation: 70–90% diversified equities (broad market index funds, global ETFs) with 10–30% debt/hedges.
- Golden Rule: The longer your time horizon, the more short-term market volatility your portfolio can absorb to capture historical equity risk premiums.
| Time Horizon | Duration | Primary Goal | Recommended Assets |
|---|---|---|---|
| Short-Term | 0 to 3 Years | Capital preservation, zero risk of loss | HYSAs, Money Market, CDs, T-Bills |
| Medium-Term | 3 to 10 Years | Moderate growth beating inflation | Short-duration bond funds, balanced ETFs |
| Long-Term | 10+ Years | Aggressive wealth accumulation | Total stock market index ETFs, broad equities |
Audio Podcast on Investment Time Horizon: A Simple Guide
When you begin your financial journey, you’ll encounter one concept that is more profoundly important than any hot stock tip or economic headline: the investment time horizon.
More than almost any other factor, your time horizon dictates your investment strategy, how much risk you can take, and the total growth potential of your money. In this guide, we’ll explore why time is your greatest superpower and how to optimize it for 2026 and beyond.
What is a Time Horizon?
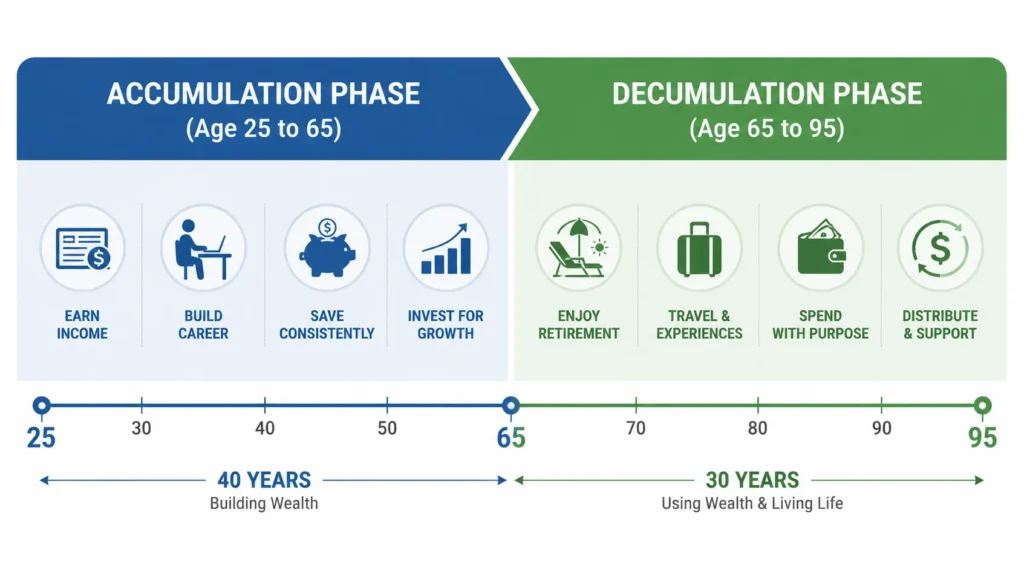
In investing, a time horizon is simply the total length of time you expect to hold an investment before you need to withdraw the money. For long-term planning, professionals break this into two critical phases:
- The Accumulation Time Horizon: The period when you are working and saving. For a 25-year-old, this is roughly 40 years. For a 50-year-old, it might be 15 years.
- The Decumulation Time Horizon: The period during retirement when you are withdrawing money to live on. Crucial Tip: Your time horizon doesn’t end the day you retire. A 65-year-old still has a decumulation horizon that could span 30 years or more.
Why Your Time Horizon is a “Superpower”
A long time horizon (10+ years) is your greatest financial asset. Here is how it fundamentally changes the rules of the game:
A. It Increases Your Risk Capacity
Market volatility is a short-term phenomenon. While the stock market can have a “bad year” where it drops 20%, those drops are historically smoothed out over long periods. With a 30-year horizon, you have the risk capacity to weather these storms and capture the higher returns offered by growth assets like stocks.
B. It Maximizes Compound Interest
Compound interest needs time to work its “magic.” Every extra year you give your portfolio allows your returns to generate their own returns, leading to exponential growth. In 2026, where market returns may be more moderate, the duration of your investment becomes the primary driver of wealth.
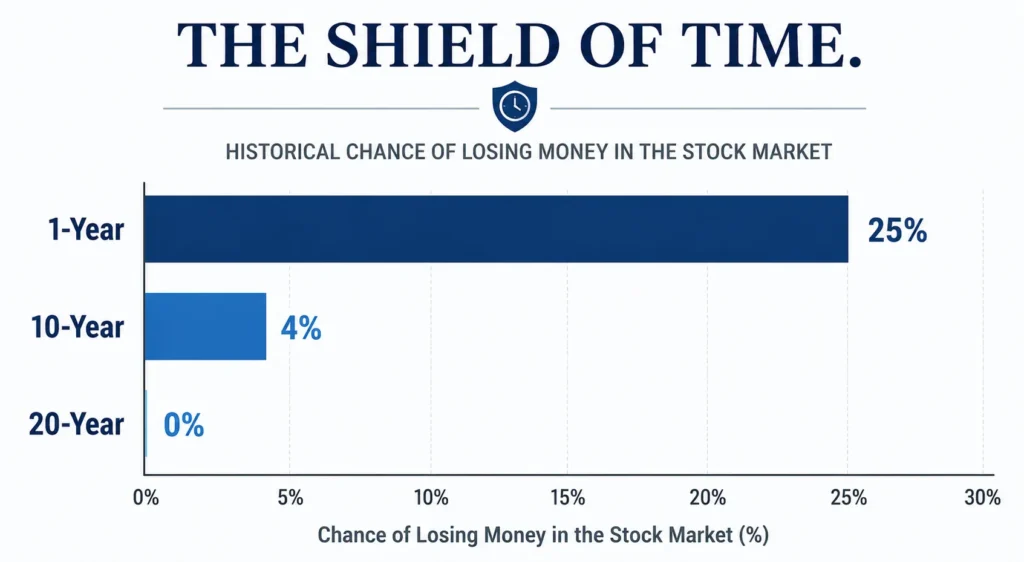
C. The Shield of Rolling Returns
Historical data proves that time heals all market wounds. * 1-Year Horizon: The odds of the S&P 500 being down are roughly 1 in 4.
- 10-Year Horizon: The odds of loss drop significantly.
- 20-Year Horizon: Historically, there has never been a 20-year period where the total return of the S&P 500 was negative.
Investment Time Horizon Decision Tree & Portfolio Allocation Matrix
Use the strategic decision framework and allocation matrix below to immediately identify where your money should be parked based on your timeline:
│
├── < 3 Years (Down payment, Emergency Fund, Upcoming Wedding)
│ └── RISK PROFILE: Zero Market Risk Tolerated
│ └── ACTION: 100% Cash Equivalents / Ultra-Short Debt (HYSA, T-Bills, FDs, Arbitrage Funds)
│
├── 3 to 7 Years (Buying a car, Higher education fund, Home renovation)
│ └── RISK PROFILE: Moderate Volatility Tolerated
│ └── ACTION: Balanced Advantage / Multi-Asset Hybrid (50% Equities / 40% Debt / 10% Gold)
│
└── 7+ to 20+ Years (Retirement, Child’s college corpus, Financial Independence)
└── RISK PROFILE: High Long-Term Volatility Absorption
└── ACTION: 70–90% Broad Equities (Nifty 50 / S&P 500 / Total Stock Index) + 10–30% Fixed Income
| Time Horizon | Typical Financial Goals | Risk Profile | Target Equity (%) | Target Fixed Income (%) | Top Recommended Vehicles |
|---|---|---|---|---|---|
| Short-Term (< 3 Years) |
Emergency fund, wedding, vacation, home downpayment | Zero / Low | 0% – 10% | 90% – 100% | High-Yield Savings, CDs, Treasury Bills, Liquid Funds |
| Medium-Term (3–7 Years) |
Car purchase, starting a business, home remodel | Moderate | 35% – 50% | 50% – 65% | Conservative/Balanced Hybrid Funds, Short-Duration Bonds |
| Long-Term (7–15 Years) |
Child’s college, early retirement, wealth building | Moderate-High | 70% – 80% | 20% – 30% | Broad Market Index Funds (S&P 500 / Nifty 50), Flexi-Cap Funds |
| Ultra Long-Term (15+ Years) |
Generational wealth, complete FIRE retirement | Aggressive | 80% – 95% | 5% – 20% | Total Stock Market Index Funds, Global ETFs, REITs |
How Time Horizon Shapes Your Strategy
To keep things simple, investors generally fall into one of three buckets. As your horizon changes, your strategy must evolve through what planners call a glide path.
Short-Term Horizon (0–3 Years)
- Goals: Wedding, house down payment, or an emergency fund.
- Strategy: Preservation of capital. In a “higher-for-longer” interest rate environment, your best friends are High-Yield Savings Accounts (HYSAs), Short-Term CDs, and Money Market Funds.
- Risk: Very Low. You don’t have time to wait for the stock market to recover if it crashes tomorrow.
Plan Your Short-Term Bucket: Not sure how much cash you need to keep safe from market drops? Use our Free Emergency Fund Calculator to find your exact target.
Medium-Term Horizon (3–10 Years)
- Goals: Starting a business, buying a second home, or college tuition for a teenager.
- Strategy: Balanced growth. A conservative mix of broad market Index Funds and Investment-grade bonds.
- Risk: Moderate. You can handle some fluctuations, but you should begin shifting toward “safer” assets as you get closer to the 3-year mark.
Long-Term Horizon (10+ Years)
- Goals: Retirement, building generational wealth.
- Strategy: Aggressive growth. This is where you harness the “superpower” of Total Stock Market Index Funds and let compound interest do the heavy lifting.
- Risk: High (Volatility). Because you have a decade or more, “paper losses” during a market dip don’t matter—only the final value at the end of the horizon.
Special Case: The Retiree (In Decumulation)
- Expert Insight: Retirees often make the mistake of becoming too conservative. Because you may spend 30 years in retirement, you still need growth to stay ahead of inflation.
- The Fix: Use a “Bucket Strategy.” Keep 2 years of cash for short-term needs, 5 years of bonds for the medium term, and the rest in stocks to fund your later years.
Sequence of Returns Risk: The Hidden Danger
To protect your nest egg against catastrophic early market drawdowns, study our tactical playbook on Sequence of Returns Risk in Retirement and test your sustainable spending limits with The 4% Safe Withdrawal Rule Guide.
In 2026, investors must be aware of Sequence of Returns Risk. This is the risk that a market crash occurs just as you enter the decumulation phase.
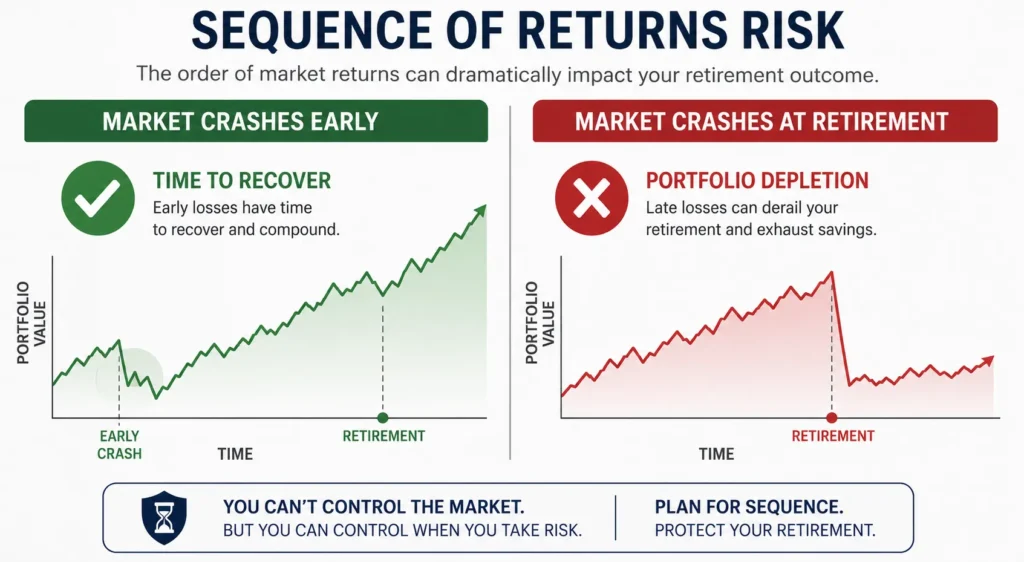
- Scenario A: You have a crash 10 years before you retire. You recover.
- Scenario B: You have a crash in Year 1 of retirement. Since you are withdrawing money while the market is down, your portfolio is depleted at an accelerated rate.
Your Defense: As your horizon shortens, your need for liquidity (cash/short-term bonds) increases to ensure you never have to sell stocks at a loss.
Conclusion: Aligning Your Goals
Understanding your time horizon is the essential first step in crafting a successful strategy.
- If you’re young: Embrace volatility as a tool for growth.
- If you’re mid-career: Audit your glide path to ensure you aren’t taking too much (or too little) risk.
- If you’re retired: Remember that your horizon is still decades long, and your portfolio needs to keep pace with inflation.
By aligning your investment choices with your time horizon, you move from “guessing” the market to “owning” your financial future.
Disclaimer: This guide is for educational purposes. Consult with a Certified Financial Planner (CFP) to tailor a strategy to your specific needs.
If you are planning long-term growth for retirement and wonder whether to hire a manager, read our comparison on DIY investing vs hiring a financial advisor.
⚡ Time Horizon Strategy & Wealth Preservation Resources
Align your investment timelines with effective inflation defense and compounding vehicles:
- Purchasing Power Defense: Explore our guide on how inflation erodes purchasing power over time and why cash drag guarantees real wealth loss over multi-decade horizons.
- Strategic Decision-Making: Explore our guide on how investment horizons shape retirement decisions to select appropriate equity/bond asset allocation splits.
- Small-Dollar Compounding: Explore our guide on starting to invest with $100 a month to build long-term momentum without large initial capital.
Frequently Asked Questions About Investment Time Horizons
Below are expert answers to the most common search queries regarding time horizons and portfolio management:
An investment time horizon is the expected duration between investing your money and needing to withdraw it. It is the single most critical factor in asset allocation because it dictates how much market volatility and downside risk your portfolio can safely absorb before liquidation.
A longer time horizon significantly enhances your ability to endure risk because your investments have multiple years to recover from cyclical market crashes. A short time horizon demands lower risk to prevent forced liquidation at a loss.
For a 3-year horizon, capital preservation is priority. The best options are High-Yield Savings Accounts (HYSAs), Treasury Bills (T-Bills), short-term Certificates of Deposit (CDs), and ultra-short duration fixed-income funds.
No. Investing in individual stocks or equity index funds for a 2-year horizon is unsafe. Equity markets can experience steep corrections that take 2 to 5+ years to recover, risking severe capital loss when you need the cash.
Review your portfolio annually and implement a glide path (shifting equities to debt/cash equivalents) 3 to 5 years prior to your planned target withdrawal date.
Matching asset allocation to your personal investment time horizon reduces capital risk and protects against forced liquidations during downturns. Consult the official U.S. Securities and Exchange Commission (SEC) Asset Allocation Guidance for statutory guidelines and consumer protections.
Jaiveer Hooda is the Lead Financial Researcher & Personal Finance Analyst at Grow Your Money Smart. Specializing in personal wealth optimization, index fund compounding, high-yield savings mechanics, and consumer debt elimination strategies. With a background in computer engineering, he applies mathematical modeling, cashflow simulations, and empirical risk analysis to evaluate personal finance vehicles and credit products. Every analysis is backed by verified regulatory disclosures, IRS tax schedules, and empirical APY compounding math.
Areas of Expertise: Personal Finance · High-Yield Savings Accounts (HYSA) · Index Funds & S&P 500 Compounding · Retirement Planning (401k/IRA) · Debt Optimization · Credit Card APR Mechanics.
Transparency & Editorial Policy: Editorial Standards | Report a Correction