
To save for a house down payment fast in 2026, set a realistic target: 3.5% to 5% ($14,000–$20,000 on a $400k home) rather than waiting for 20%. Store funds in an FDIC-insured 4.0%+ HYSA, automate payday transfers, channel 100% of tax refunds and bonuses, and utilize state first-time buyer grants.
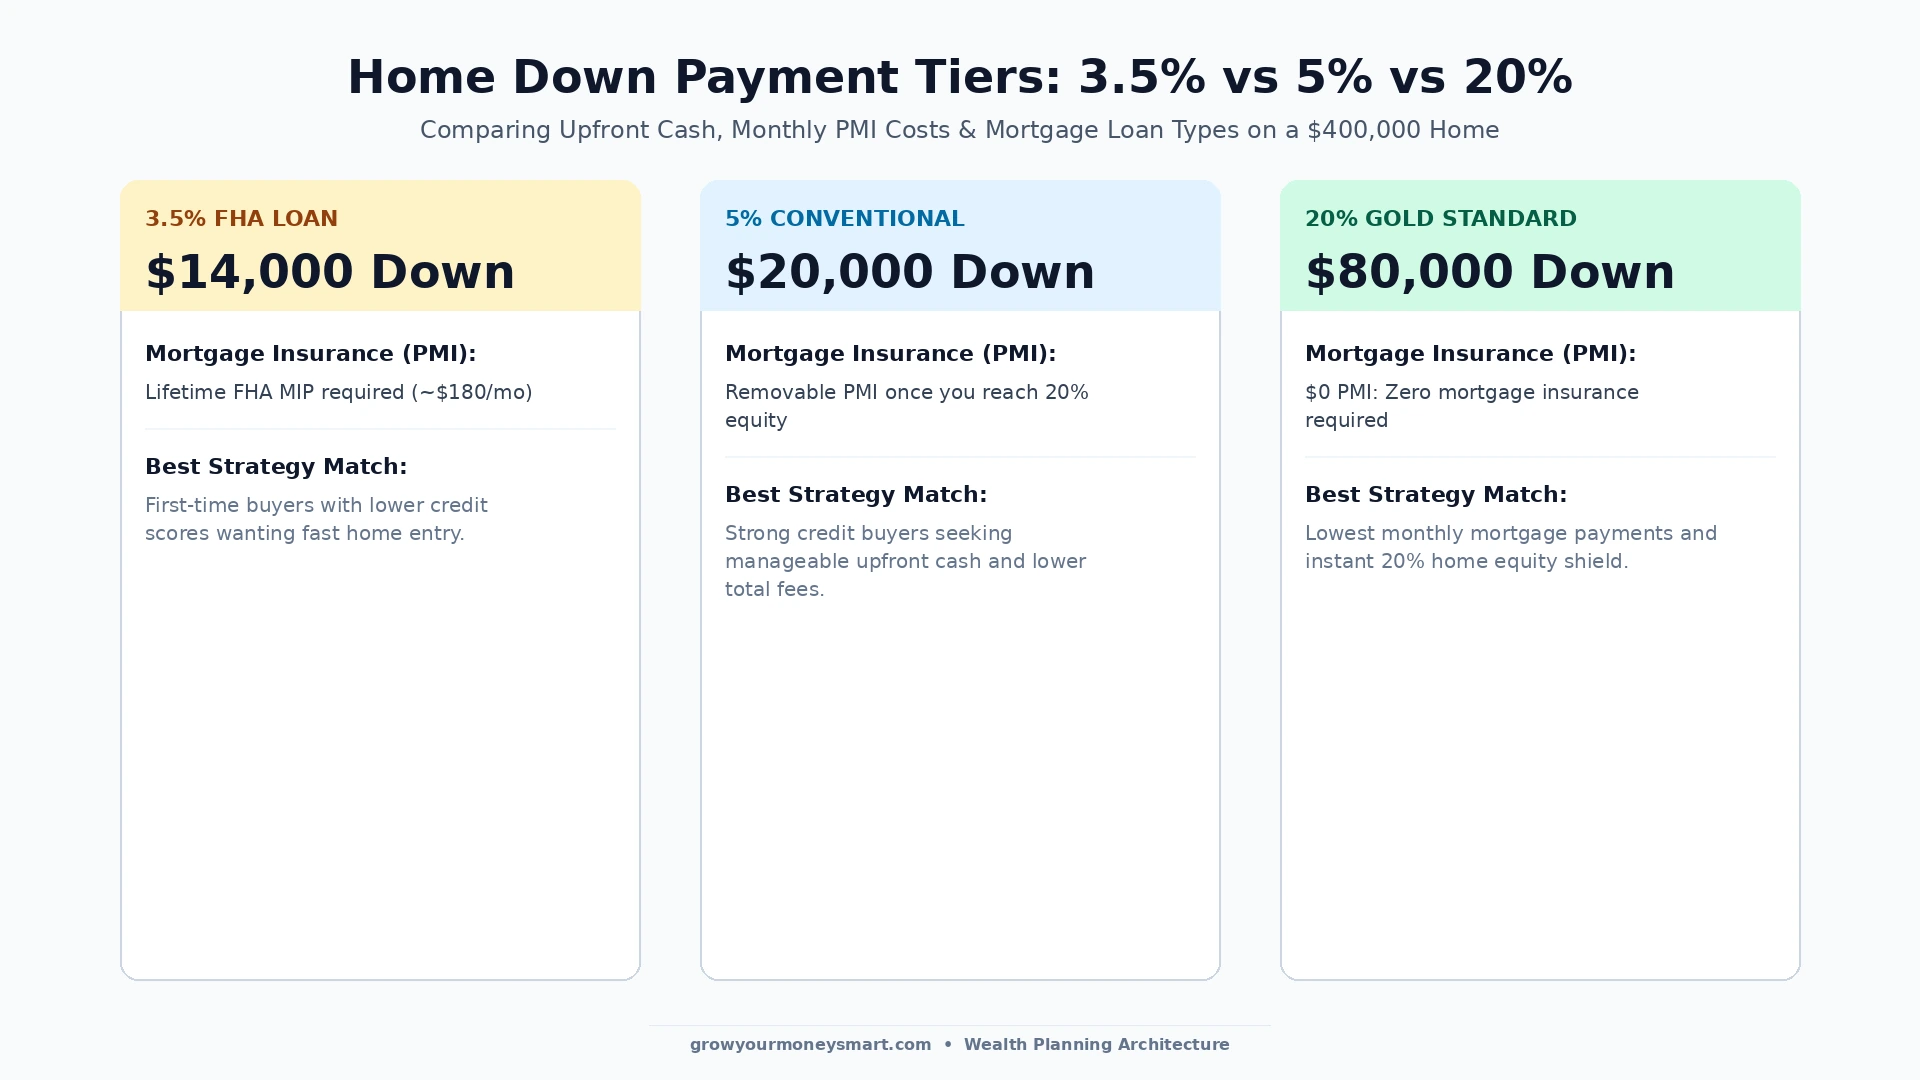
- The 20% Myth Debunked: You do NOT need $80,000 (20%) to buy a home. First-time buyers can enter with 3.5% (FHA) or 5% (Conventional) down payments.
- Budget for Closing Costs: Always save an extra 2% to 4% of the purchase price ($8,000–$15,000) for lender fees, title insurance, and property tax prepaids.
- The HYSA Vault: Never invest down payment money in the stock market if buying within 3 years. Keep funds in a 3.00% to 4.40% HYSA with zero capital risk.
- Tackle Toxic Debt First: Paying down high-interest credit cards improves your Debt-to-Income (DTI) ratio, unlocking thousands in lower mortgage interest rates.
- First-Time Buyer Grants: Check state and local housing finance agencies for grants providing $5,000 to $15,000 in forgivable down payment assistance.
For millions of aspiring homeowners, the single greatest hurdle between renting and owning a home is the intimidating mountain of the down payment. With national median home prices hovering around $400,000, traditional financial advice insists that you need a staggering $80,000 (20%) in cash before you even look at a listing.
Here is the reality: the 20% down payment is a myth. According to the Consumer Financial Protection Bureau (CFPB), millions of Americans buy homes every year with conventional loans requiring just 3% to 5% down, or FHA loans requiring only 3.5% down.
If you are deciding between saving for a home versus retirement, read our strategic comparison on House Deposit vs. Retirement Fund Strategy. And if you are budgeting toward a home on a fixed salary, follow our $5,000 monthly salary blueprint or our $6,000 income roadmap.
Down Payment Math: How Much Cash Do You Really Need?
Let’s look at the real-world numbers on a $400,000 median home purchase across different mortgage tiers:
5 Proven Tactics to Accelerate Your Down Payment Savings
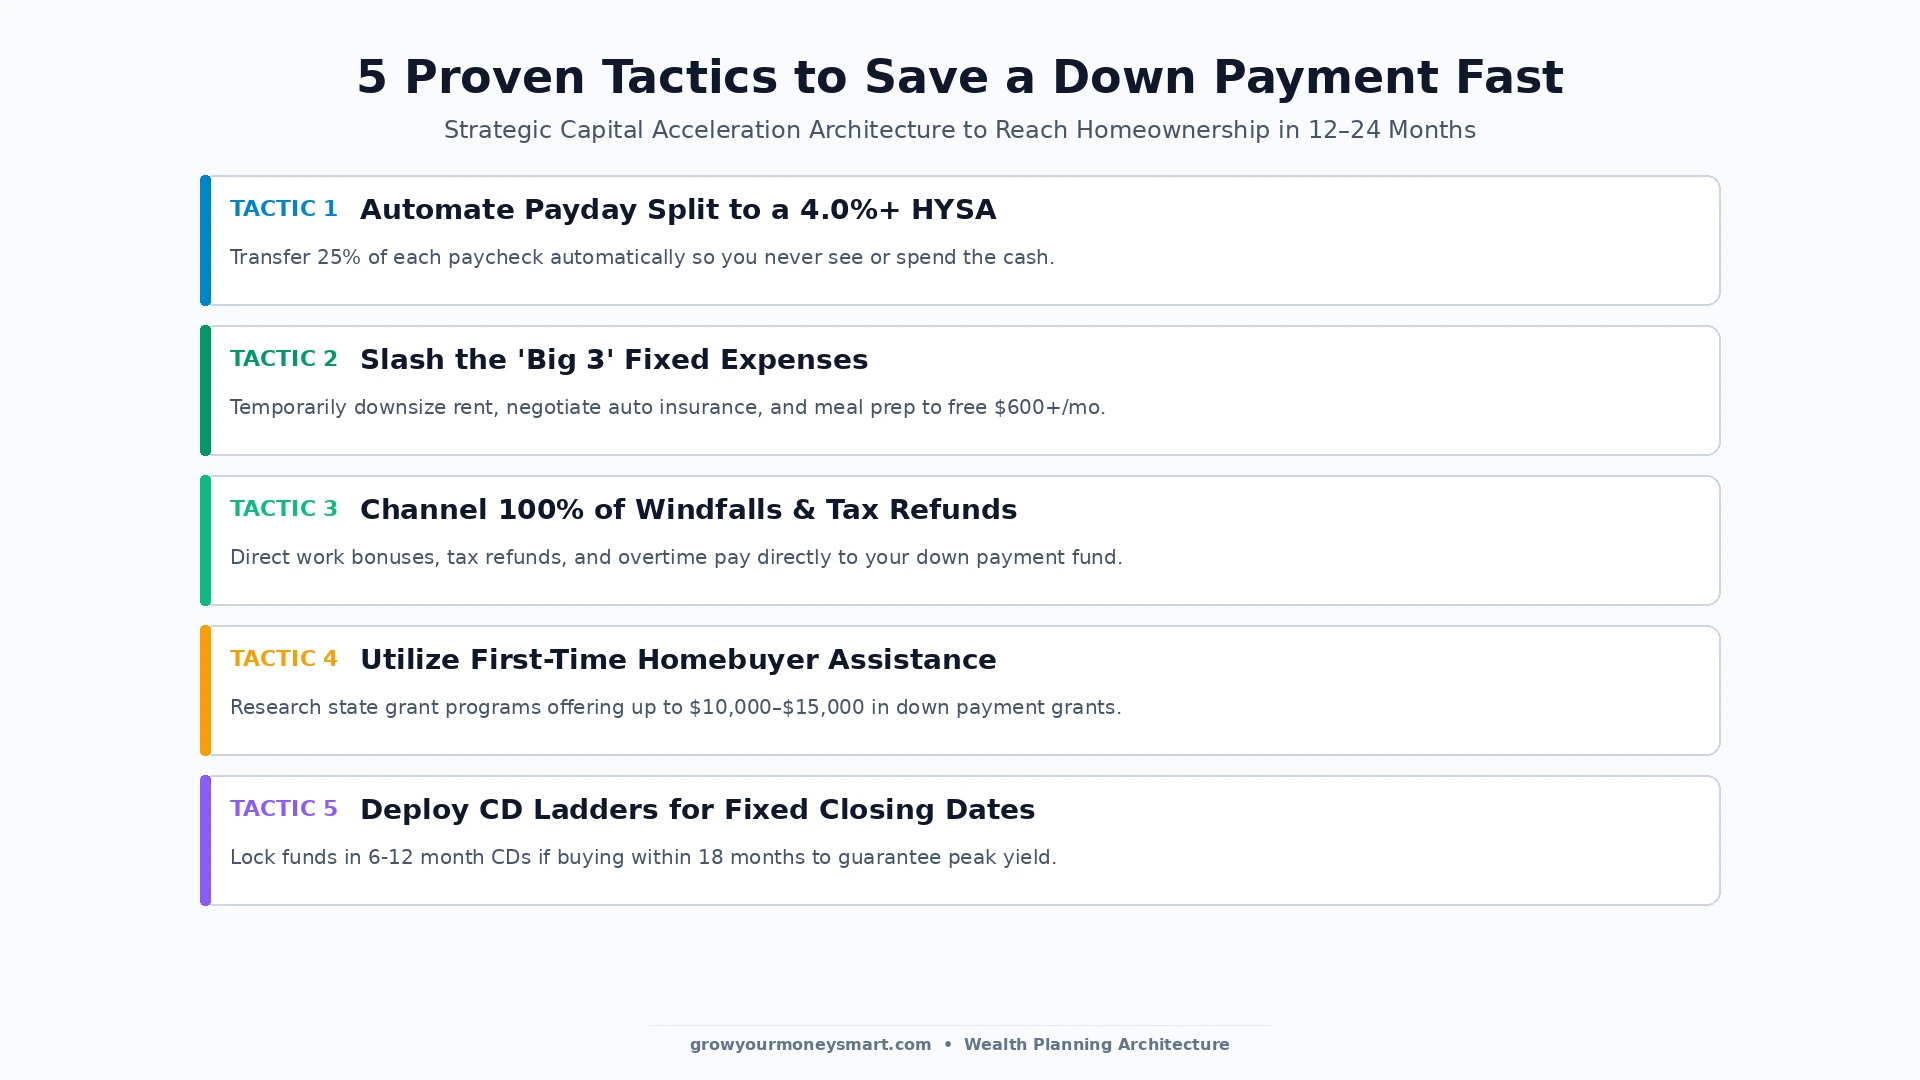
- 1. Open a Separate 4.0%+ HYSA: Never let down payment savings mix with your daily checking account. Open an account with our top picks in the Best High-Yield Savings Accounts Guide and let compounding interest generate free cash flow.
- 2. Slash the “Big 3” Fixed Expenses: Trimming lattes saves $50/month; negotiating rent, moving into a modest apartment for one year, or selling an expensive car note frees up $500 to $1,000 every single month.
- 3. Direct 100% of Windfalls & Bonuses: Treat work bonuses, annual tax refunds, and overtime pay as “invisible money” that routes directly into your home fund.
- 4. Investigate State Down Payment Assistance (DPA) Programs: Every U.S. state offers housing finance programs providing forgivable second mortgages or grants of $5,000 to $15,000 for qualifying first-time buyers.
- 5. Eliminate High-Interest Debt: High credit card balances degrade your mortgage rate. Use our debt payoff calculator to eliminate balances before applying for pre-approval.
Expert Video Breakdown: Saving For A House Down Payment Quickly
To see the complete tactical roadmap for accumulating a real estate down payment while minimizing closing costs, watch Graham Stephan’s comprehensive blueprint:
Frequently Asked Questions (FAQs)
No. While putting 20% down eliminates private mortgage insurance (PMI), the average first-time homebuyer puts down between 6% and 8%. Conventional loans require as little as 3% to 5% down, and FHA loans require just 3.5%.
Keep your down payment in an FDIC-insured High-Yield Savings Account (HYSA) or a Certificate of Deposit (CD) ladder if your purchase timeline is 1 to 3 years away. Never risk down payment money in volatile stock market investments.
Closing costs typically range between 2% and 5% of the total loan amount. On a $400,000 purchase, budget an additional $8,000 to $15,000 for loan origination, title fees, appraisal, and prepaid property taxes.
Saving $1,000 per month in a 4.0% HYSA yields approximately $24,500 in 24 months—enough for a 5% down payment and closing costs on a $350,000 home.
Yes. IRS rules allow first-time homebuyers to withdraw up to $10,000 from a traditional IRA penalty-free (income taxes apply) or withdraw your Roth IRA principal contributions tax- and penalty-free at any time.
PMI is an insurance policy that protects the mortgage lender if you default on payments when putting down less than 20%. PMI costs roughly 0.5% to 1.5% of the loan amount annually and is added to your monthly mortgage bill.
Pay off all high-interest toxic debt (such as credit cards with >8% APR) first, as carrying revolving balances harms your credit score and Debt-to-Income (DTI) ratio, resulting in higher mortgage interest rates.
FHA loans accept credit scores as low as 580 with a 3.5% down payment. Conventional mortgages typically require a minimum credit score of 620, with prime interest rates reserved for scores of 740 and higher.
🏡 Down Payment Strategy vs Retirement Compounding
Balance accumulating a property deposit with lifelong retirement security and mortgage hacks:
- The Core Tradeoff: house deposit vs retirement fund savings strategy — resolving the opportunity cost dilemma between real estate equity and 401(k) compounding.
- Post-Purchase Optimization: mortgage recast vs refinance which saves more money — lowering monthly mortgage payments once you make a large lump-sum principal reduction.
- Early Mortgage Payoff: pay off mortgage early in 2026 — evaluating return on capital for aggressive principal payoffs.
- Smart Budgeting: smart budgeting strategies for 2026 — proven frameworks to maintain a 30%+ savings rate for down payment accumulation.
Jaiveer Hooda is the Lead Financial Researcher & Personal Finance Analyst at Grow Your Money Smart. Specializing in personal wealth optimization, index fund compounding, high-yield savings mechanics, and consumer debt elimination strategies. With a background in computer engineering, he applies mathematical modeling, cashflow simulations, and empirical risk analysis to evaluate personal finance vehicles and credit products. Every analysis is backed by verified regulatory disclosures, IRS tax schedules, and empirical APY compounding math.
Areas of Expertise: Personal Finance · High-Yield Savings Accounts (HYSA) · Index Funds & S&P 500 Compounding · Retirement Planning (401k/IRA) · Debt Optimization · Credit Card APR Mechanics.
Transparency & Editorial Policy: Editorial Standards | Report a Correction