
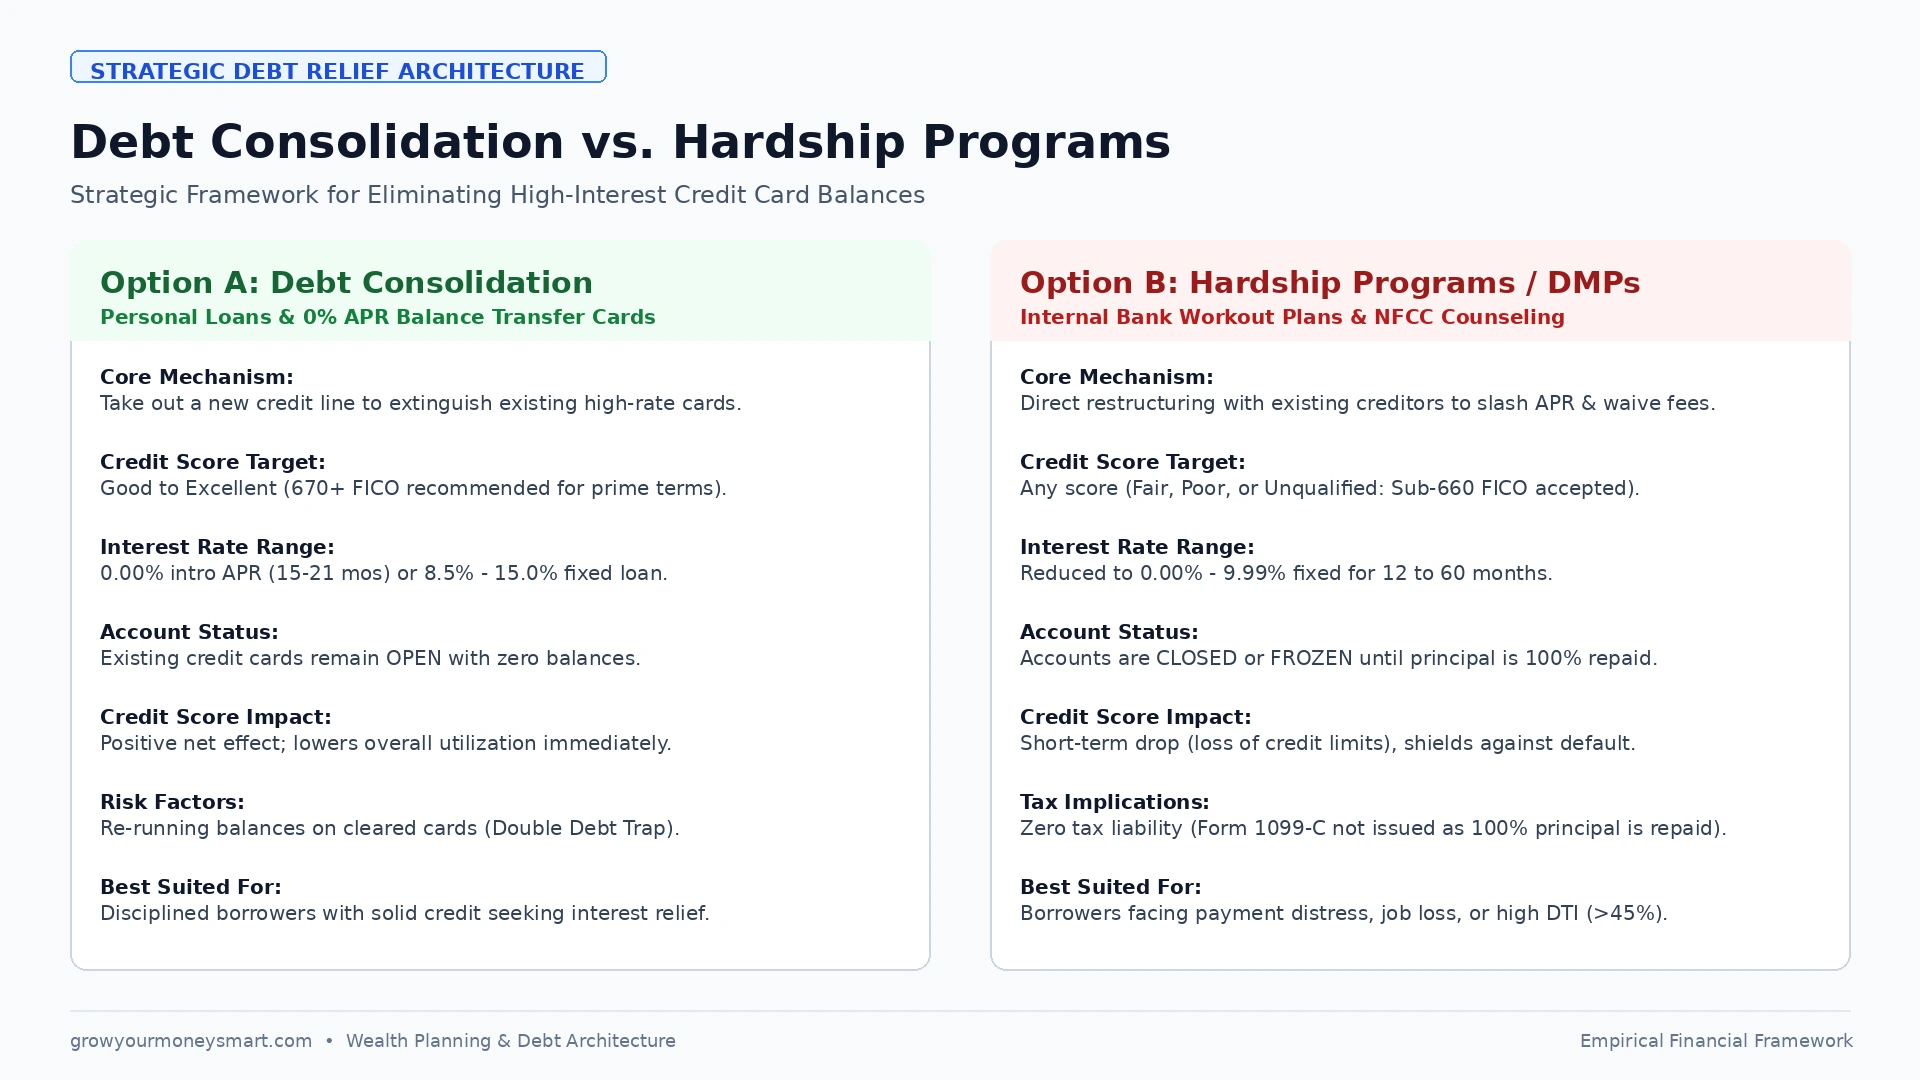
In the debate of debt consolidation vs hardship programs, debt consolidation combines multiple balances into a single new loan or 0% balance transfer credit card (requiring a 670+ FICO score), whereas a hardship program negotiates directly with existing lenders to slash APR to 0%–9.9% when facing distress. Choose consolidation if your credit is intact; choose hardship programs if your debt-to-income ratio exceeds 45% or minimum payments are unmanageable.
- Credit Profile Bifurcation: Debt consolidation requires qualifying for new credit (FICO 670+ for prime rates). Hardship programs require zero new credit approval and are negotiated directly with your existing creditors.
- Account Status: Consolidation leaves your original credit cards open (risk of re-charging balances). Hardship programs and Debt Management Plans (DMPs) almost universally close or freeze the accounts until repaid.
- Credit Score Dynamics: Consolidation boosts credit over time by slashing utilization. Hardship programs cause a temporary 15–40 point dip due to closed credit limits, but shield you from devastating 120+ point delinquency hits.
- Zero Tax Surprises: Unlike debt settlement (which triggers taxable cancellation of debt income on IRS Form 1099-C), both consolidation and hardship programs repay 100% of principal, generating zero tax liabilities.
When evaluating debt consolidation vs hardship programs, borrowers must navigate a landscape where average credit card interest rates exceed 24% APR (according to the Federal Reserve G.19 Consumer Credit Report). Carrying revolving balances at these usurious rates is an acute financial emergency. If you are struggling under $10,000, $20,000, or more in revolving card balances, continuing to make standard 2% to 3% minimum payments is mathematical suicide—a $15,000 balance can consume over $18,400 in pure interest and take 21 years to extinguish.
To eliminate this debt, two primary relief mechanisms dominate the landscape: Debt Consolidation and Credit Card Hardship Programs. Understanding the strategic nuances of debt consolidation vs hardship programs is essential because financial marketing frequently blurs the lines between them. Choosing the wrong mechanism can trap you in a high-fee consolidation loan you cannot afford or unnecessarily damage your credit profile when simpler alternatives exist.
In this comprehensive master playbook on debt consolidation vs hardship programs, we deconstruct the exact mechanics, mathematical cost models, credit score trajectories, and qualification criteria for both pathways—giving you the empirical clarity needed to choose the right strategy for your household balance sheet.
The Core Mechanism Dilemma: How Each Strategy Works
To understand which pathway fits your financial reality, you must first examine how each solution approaches your underlying debt obligations. In the broader scope of debt consolidation vs hardship programs, each method tackles interest rates and account management differently.
Debt Consolidation: Taking New Credit to Extinguish Old Debt
Debt consolidation is a proactive, voluntary restructuring mechanism. You apply for a brand-new financial product—most commonly an unsecured fixed-rate personal loan or a 0% APR balance transfer credit card. If approved, the new lender disburses funds directly to pay off your multiple existing credit card balances, rolling them into a single monthly payment.
The Core Objective: Lower your effective interest rate (e.g., swapping a 25.99% variable card APR for an 11.5% fixed loan APR or a 0% introductory promotional rate) and establish a concrete, amortized payoff timeline of 15 to 60 months. Your original credit card accounts remain open with zero balances unless you elect to close them. For a deeper breakdown of consolidation variants, consult our debt consolidation vs balance transfer comparison.
Credit Card Hardship Programs: Renegotiating Existing Debt Contracts
A credit card hardship program is a concessionary agreement negotiated directly with your current card issuers (or coordinated through a non-profit credit counseling agency via a Debt Management Plan). You do not take out a new loan, and there is no credit check involved.
Instead, you contact the card issuer’s internal loss mitigation department, present documentation of genuine financial distress (such as job reduction, medical crisis, or divorce), and request temporary or permanent relief. If you are exploring whether you can negotiate credit card interest rates directly before applying for formal hardship, many banks will accommodate proactive borrowers. If approved, the issuer agrees to drastically reduce your interest rate (frequently down to 0% to 9.99%), waive late fees, and lower your required monthly payment for 6 to 60 months. In exchange, the bank almost always freezes or permanently closes your card account to stop further charging. Learn more about bank-specific policies in our guide on credit card hardship programs.
Debt Consolidation vs Hardship Programs: Head-to-Head Comparison Matrix
When analyzing debt consolidation vs hardship programs side-by-side, the divergence across credit score requirements, interest terms, and account status becomes starkly clear. The matrix below outlines the critical differences across all major parameters:
| Comparison Dimension | 0% Balance Transfer Card | Personal Consolidation Loan | Internal Bank Hardship Program | Non-Profit DMP (NFCC) |
|---|---|---|---|---|
| Primary Goal | 0% interest window for fast payoff | Fixed rate & predictable monthly term | Emergency temporary payment relief | Comprehensive multi-card payoff plan |
| Credit Score Minimum | 670–720+ (Good to Excellent) | 640–680+ (Fair to Good) | No minimum (Any score) | No minimum (Any score) |
| Interest Rate (APR) | 0.00% for 15–21 months | 8.5% – 16.0% fixed | 0.0% – 9.9% concessionary | 6.0% – 9.0% negotiated |
| Typical Repayment Term | 15 to 21 months | 24 to 60 months | 6 to 12 months (short-term) | 36 to 60 months (long-term) |
| Impact on Credit Card Lines | Cards remain OPEN | Cards remain OPEN | Cards FROZEN or CLOSED | Enrolled cards CLOSED |
| Credit Score Effect (Short-Term) | Small inquiry dip (-5 pts), then surge | Surges +20 to +40 pts (utilization drops) | Drops -15 to -40 pts (limits closed) | Drops -15 to -40 pts initially |
| Upfront / Ongoing Fees | 3% – 5% balance transfer fee | 0% – 6% origination fee | $0 fee (bank workout) | $25–$50 setup + $25/mo agency fee |
| IRS Form 1099-C Tax Risk? | NO ($0 Tax) | NO ($0 Tax) | NO ($0 Tax) | NO ($0 Tax) |
| Biggest Operational Risk | Unpaid balance reverts to 25%+ APR | Re-running balances on empty cards | Program expires before debt paid | Strict budget discipline for 4–5 years |
The $15,000 Debt Payoff Reality: Empirical Cost Simulation
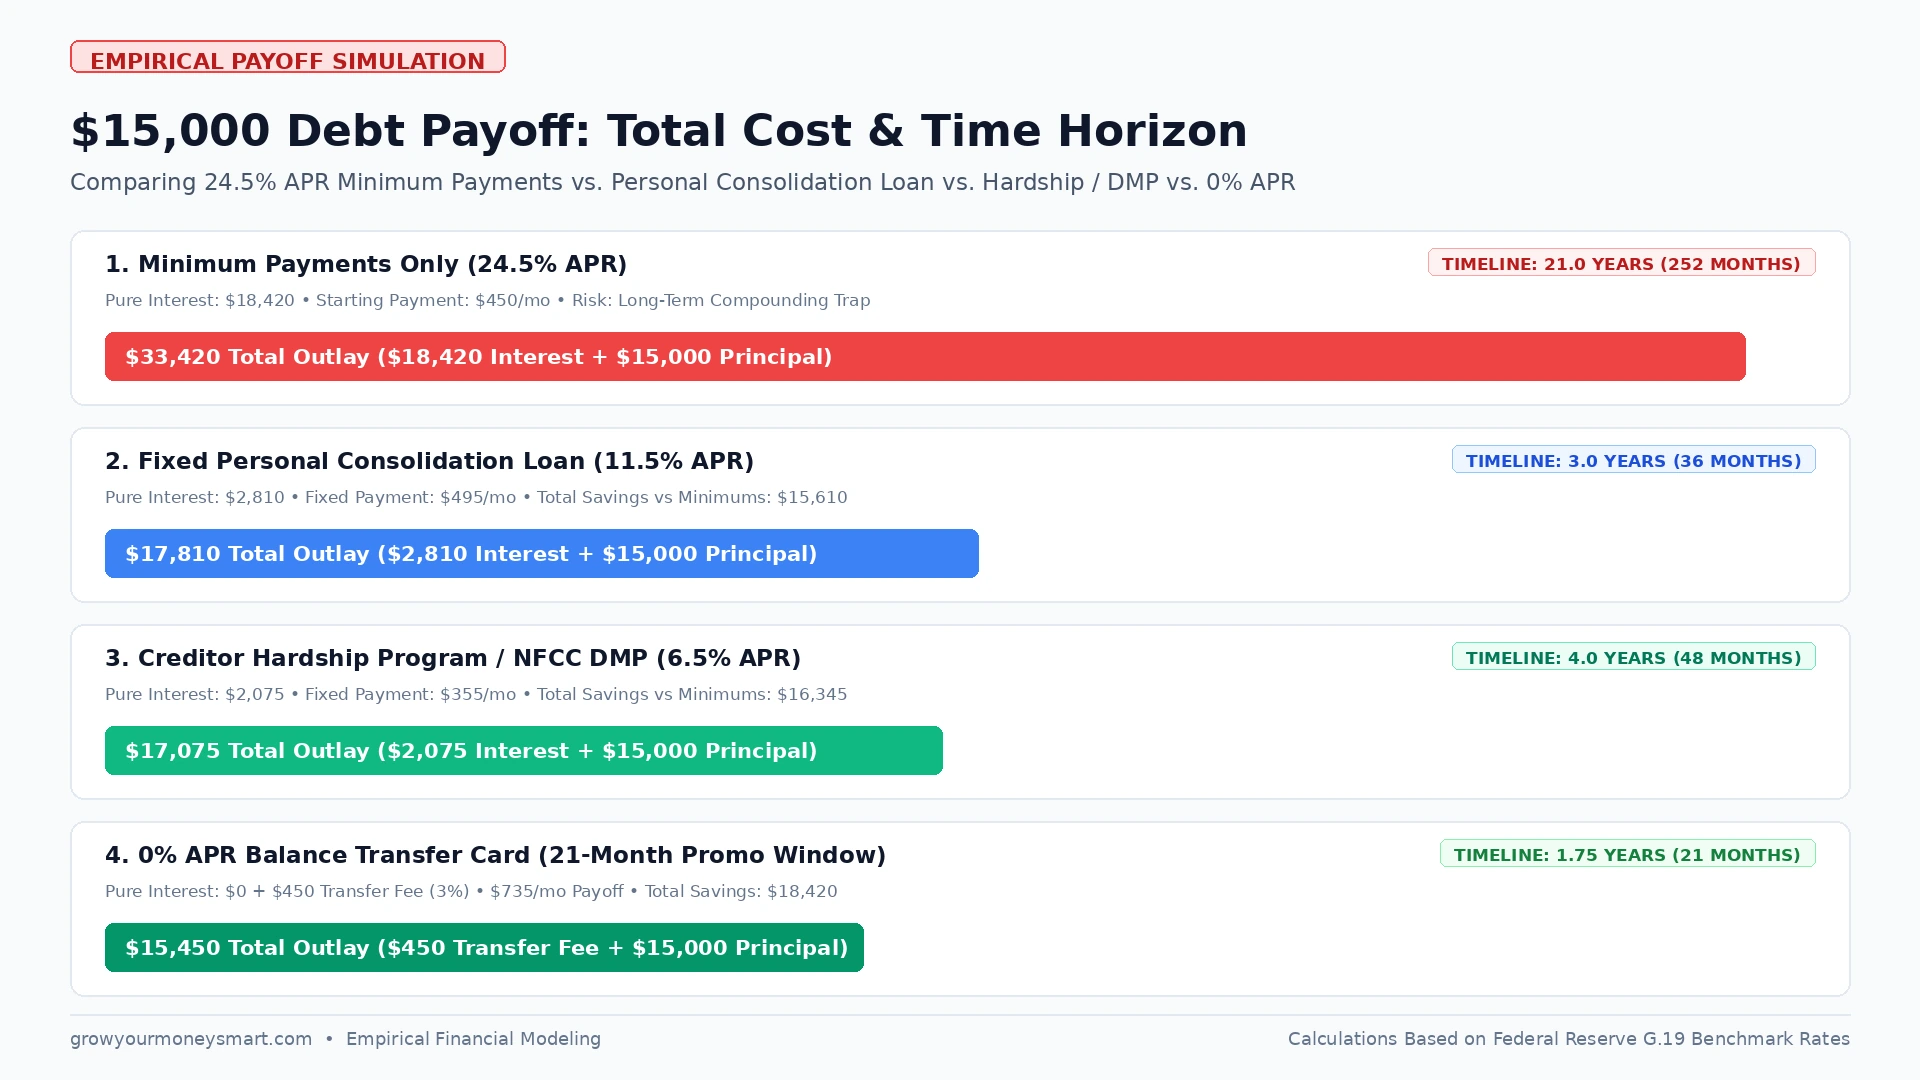
To demonstrate the concrete financial difference in debt consolidation vs hardship programs, let us evaluate an empirical case study: an individual carrying $15,000 in credit card debt across three accounts with an average annual percentage rate of 24.5%.
Empirical Payoff Comparison: $15,000 Total Credit Card Debt
Starting payment: $450/month (declining). Total time to debt freedom: 21.0 years (252 months). Total interest paid: $18,420. Total cash outlay: $33,420. You pay more than 122% in pure interest overhead! Model your exact numbers with our credit card minimum payment calculator.
Fixed monthly payment: $495/month. Total time to debt freedom: 3.0 years (36 months). Total interest paid: $2,810. Total cash outlay: $17,810. Pure interest savings compared to minimum payments: $15,610 saved.
Fixed monthly payment: $355/month. Total time to debt freedom: 4.0 years (48 months). Total interest paid: $2,075 (plus modest counselor maintenance fees). Total cash outlay: $17,075. Pure interest savings: $16,345 saved without requiring good credit.
Aggressive monthly payment: $735/month ($15,450 / 21). Total time to debt freedom: 1.75 years (21 months). Total interest paid: $0 (Balance transfer fee: $450). Total cash outlay: $15,450. Pure interest savings: $18,420 saved. Run the math on your household balance sheet with our interactive debt payoff calculator or download our customized free debt payoff Excel and Google Sheets template to track your amortization schedules.
The Credit Score Trajectory: Short-Term Pain vs. Long-Term Health
One of the most persistent misconceptions in the debt consolidation vs hardship programs conversation is that debt consolidation is always “good” for your credit score and hardship programs are “ruinous.” In reality, credit scoring algorithms (FICO 8, FICO 9, and VantageScore 4.0) react in nuanced ways depending on credit utilization, account ages, and delinquency reporting.
Credit Impact of Debt Consolidation
When you take out a personal consolidation loan to pay off revolving credit cards, your credit score typically experiences an immediate and dramatic boost within 30 to 60 days. Why? Because credit utilization (which accounts for 30% of your FICO score) measures revolving debt. By transferring $15,000 from credit cards to an installment loan, your revolving credit utilization plummets from 85%+ down to 0%.
Installment debt is weighted far more favorably than revolving debt in FICO models. Borrowers frequently witness a 25 to 55 point increase in their credit score after the payoff reports to Experian, Equifax, and TransUnion. The only minor negative is a temporary 3 to 5 point reduction from the initial hard credit inquiry.
Credit Impact of Hardship Programs and DMPs
Entering an internal hardship program or a Debt Management Plan does not trigger a derogatory mark like bankruptcy or debt settlement. However, it affects your credit profile through two distinct mechanisms:
- Closed Account Limits (Utilization Surge): When your card issuer closes or freezes an account with a $5,000 balance and a $6,000 credit limit, your available credit on that card drops to $0. Suddenly, the card appears at 100% utilization ($5,000 balance on $0 or $5,000 limit). Across your entire credit report, this reduction in available credit can cause your overall score to decline by 15 to 40 points in months 1 through 6.
- Account Notation Codes: Some card issuers place an informational notation on your credit file such as “Account closed at grantor’s request” or “Paying under a partial payment agreement / managed by credit counseling.” FICO algorithms explicitly state that counseling notations do not mathematically lower FICO scores; however, individual manual underwriters for mortgages or auto loans may review them during underwriting.
The Strategic Perspective: While a 30-point temporary decline may feel uncomfortable, consider the alternative. When comparing debt consolidation vs hardship programs under severe distress, missing payments without a hardship plan will trigger 30-day, 60-day, and 90-day delinquencies. A single 90-day late payment obliterates 90 to 130 points from your credit score and remains on your report for 7 long years under the Fair Credit Reporting Act (CFPB Credit Counseling Guidance). An orderly hardship plan acts as a bulletproof shield against catastrophic delinquency.
The Qualification & Triage Matrix: Choosing Your Path
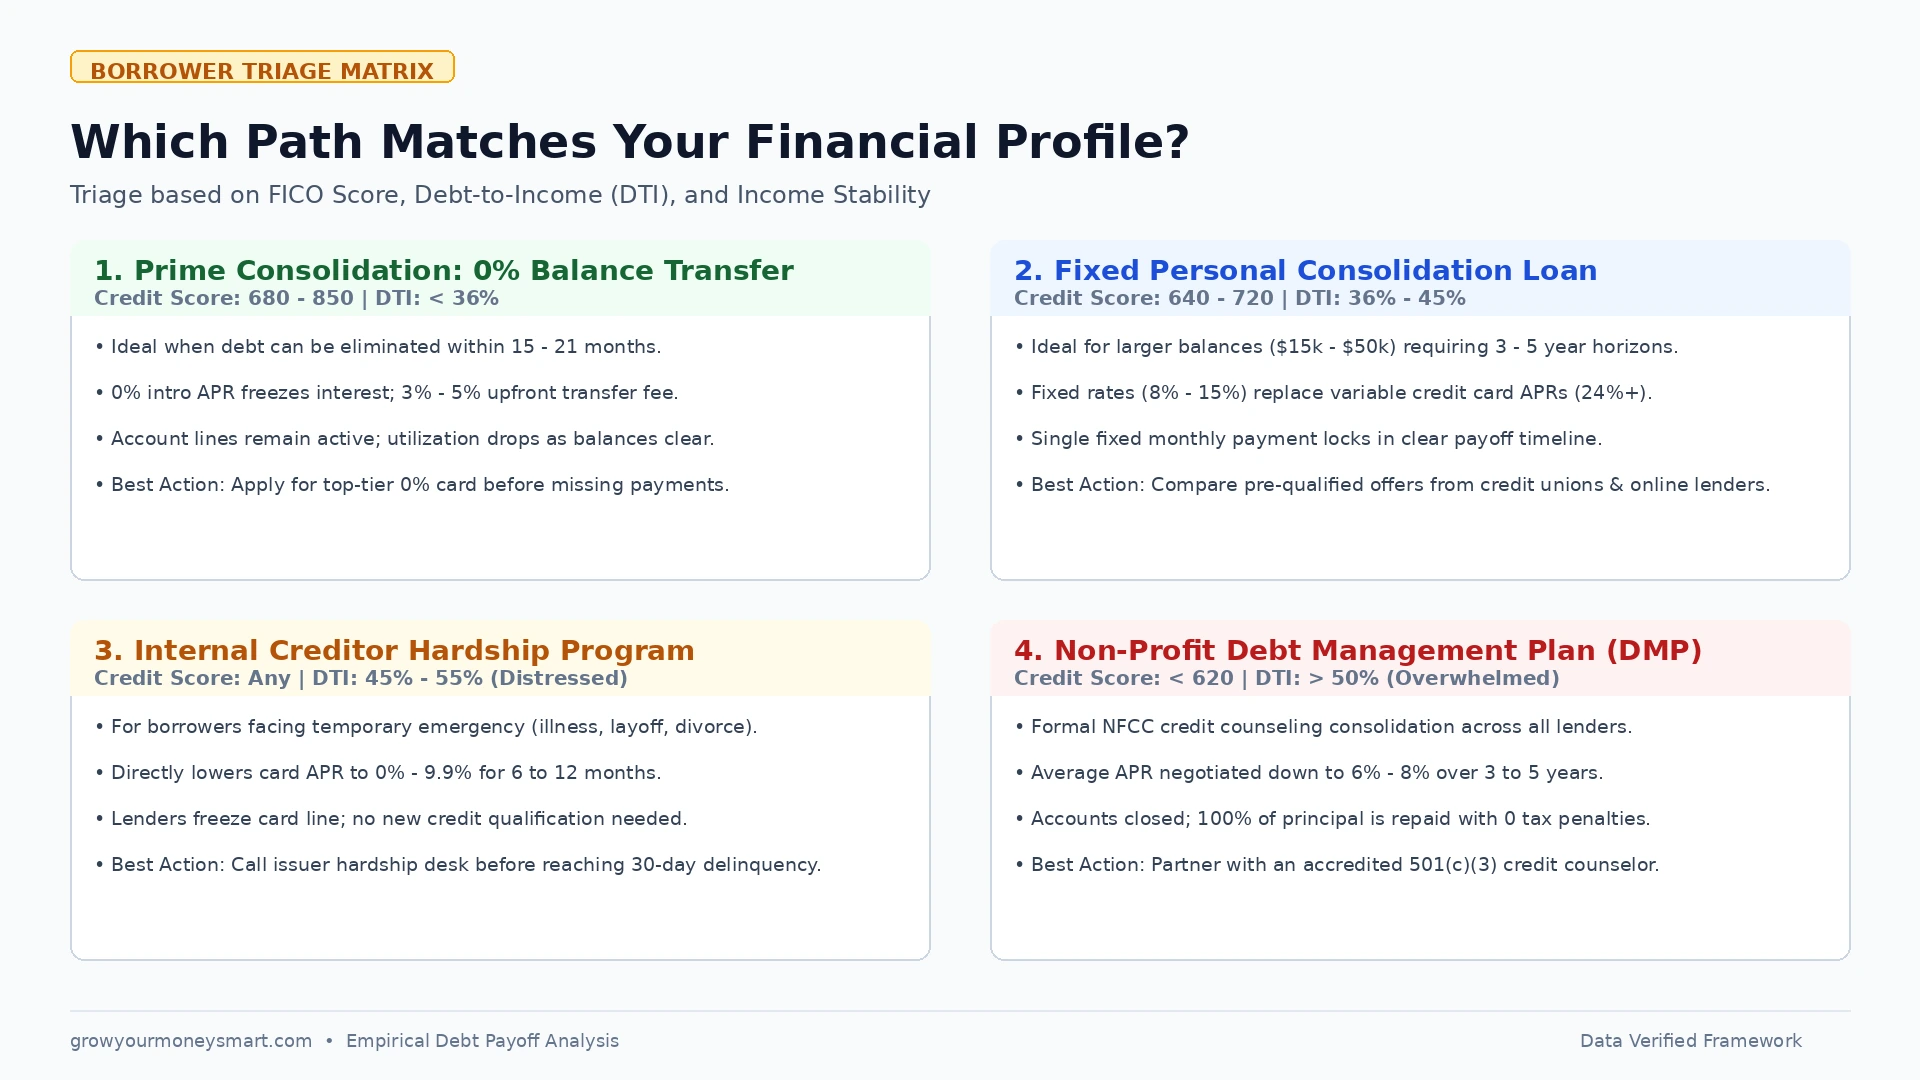
To determine with absolute certainty where you land on the spectrum of debt consolidation vs hardship programs, examine the 4-quadrant triage framework below:
Profile: FICO 680–850 | DTI < 36% | High Discipline
You have strong credit and stable cash flow. You can comfortably pay off the entire balance within 15 to 21 months ($500–$800/mo). Pay the 3% transfer fee and eliminate 100% of interest.
Profile: FICO 640–720 | DTI 36%–45% | Multi-Year Horizon
Your debt is too large for an 18-month payoff (if your balance is smaller, review our roadmap on how to pay off $10k debt in 1 year, or if higher, our guide to paying off $20k credit card debt fast). A fixed personal loan locks in an 8%–14% APR over 3 to 5 years, cutting your payment and preventing interest escalation.
Profile: Any FICO | DTI 45%–55% | Temporary Crisis
You cannot qualify for a low-rate loan, but your setback (layoff, illness) is temporary. Contact your card issuer to slash APR to 0%–9.9% for 6 to 12 months to regain stability.
Profile: FICO < 620 | DTI > 50% | Structural Deficit
Your debt exceeds your capacity to refinance. An NFCC-accredited credit counselor rolls all cards into one payment at ~7% APR over 48–60 months, protecting you from litigation.
The 1099-C Tax Trap: Why Hardship & Consolidation Beat Debt Settlement
When consumers research debt relief on the internet, for-profit “debt settlement” or “debt negotiation” companies aggressively advertise that they can “settle your debt for 50%.” In any thorough assessment of debt consolidation vs hardship programs, it is vital to understand why debt settlement is fundamentally dangerous from a tax perspective (for a deeper comparison of distressed options, see our guide on debt settlement vs bankruptcy: when to file).
Under Section 61(a)(11) of the Internal Revenue Code, forgiven or cancelled debt is legally classified as taxable gross income. If a debt settlement firm negotiates a $15,000 credit card balance down to $7,000, your lender writes off the remaining $8,000 and issues an IRS Form 1099-C (Cancellation of Debt). In a 22% federal tax bracket, you will owe the IRS approximately $1,760 in cash taxes on that phantom income, not including state taxes! Furthermore, debt settlement requires defaulting on your debt for months, causing catastrophic credit damage. Learn how to navigate settlement risks in our guide on how to settle credit card debt yourself.
In contrast, both Debt Consolidation and Creditor Hardship Programs / DMPs require you to repay 100% of your principal balance. Because zero principal is forgiven (only future interest charges and fees are reduced or waived), no IRS Form 1099-C is issued, and your tax liability is exactly $0. You achieve debt elimination cleanly with zero tax repercussions.
Step-by-Step Action Blueprints: How to Execute Each Option
How to Execute a Debt Consolidation Strategy
If your profile aligns with debt consolidation, execute these four sequential steps to ensure maximum interest savings:
- Audit Your Total Balances & Weighted APR: List every card, current balance, and APR. Determine your total debt. If you carry debt across multiple cards and are strategizing repayment sequence, consult our roadmaps on how to prioritize multiple debts and determining which debt should I pay off first. If your balances exceed $15,000, a personal loan is generally safer than a balance transfer card.
- Use Soft-Pull Pre-Qualification Tools: Check pre-qualified loan offers through local credit unions and reputable online lenders. Pre-qualification soft pulls do not impact your credit score. Ensure the loan APR is at least 6% lower than your current credit card APR.
- Direct Disbursal Setup: Whenever possible, select lenders that offer direct creditor payoff. The lender sends the loan proceeds directly to your credit card companies, eliminating any temptation to spend the funds.
- Freeze the Cleared Cards (Avoid the Double-Debt Trap): The number one failure mode of consolidation is running new balances on cleared credit cards while paying the loan. Put your physical credit cards in a lockbox, remove saved card details from online shopping portals, and accelerate repayment using structured strategies like the debt avalanche vs snowball method.
How to Negotiate an Internal Credit Card Hardship Program
If you determine that a hardship program is your optimal pathway, contact your credit card issuer directly using this proven step-by-step phone protocol:
Call the customer service number on the back of your card. When the automated menu asks for your reason, say “Financial Hardship” or ask to be transferred to the Account Assistance / Loss Mitigation Department.
Crucial Tips: Call before your account becomes 30 days delinquent. Be prepared to state your monthly net income, essential living expenses, and the exact dollar payment you can afford each month.
Expert Video Guide: Debt Management vs. Debt Consolidation in 2026
To visualize the critical decision trade-offs between structured debt management programs and consolidation loans on a mathematical balance sheet, watch this comprehensive breakdown by Ascend Finance:
Integrating Debt Relief into Your Broader Financial Plan
Whether you choose debt consolidation or enter a credit card hardship program, eliminating high-interest consumer debt is foundational to your long-term wealth building plan. Once your pathway is selected, coordinate your debt repayment with these key financial strategies:
- The Emergency Fund Rule: Never direct 100% of your free cash toward debt while leaving zero emergency savings. If your cash flow is currently constrained, see our actionable playbook on how to pay off debt living paycheck to paycheck. Always secure a starter buffer in a high-yield account (detailed in our emergency fund HYSA master guide) so an unexpected expense does not force you back into credit card borrowing. Maintain a micro-emergency fund of $1,000 to $1,500 in a dedicated account. Learn the strategic balance in our guide on paying off debt vs saving an emergency fund.
- Systematic Repayment Strategy: If consolidating multiple loans, adopt a proven mathematical structure. Compare the pros and cons in our comprehensive debt management strategies guide.
- Budgeting Architecture: Structure your cash flow using a zero-based or percentage budgeting system so every dollar is assigned before the month begins.
Frequently Asked Questions (FAQ)
Enrolling in a hardship program does not create a derogatory delinquency record. However, your score may dip 15 to 40 points temporarily because creditors typically freeze or close your credit line, which lowers your total available credit and temporarily spikes your credit utilization ratio. As you pay down principal, your score recovers.
To secure a favorable interest rate (8.5% to 14% fixed), you generally need a FICO score of 670 or higher and a debt-to-income ratio below 40%. Borrowers with credit scores between 580 and 660 can still qualify, but lenders often charge APRs of 22% to 32%, which eliminates the cost savings of consolidating.
Yes. All major credit card issuers (Chase, American Express, Citi, Discover, Capital One, Bank of America) maintain internal hardship departments. You do not need to pay a third-party service. Call the number on the back of your card, request the hardship desk, explain your circumstances, and ask for a temporary APR reduction.
An internal hardship program is negotiated one-on-one with an individual bank and typically lasts 6 to 12 months. A Debt Management Plan (DMP) is a formal, multi-lender program administered by an accredited non-profit credit counseling agency (such as NFCC) that consolidates all your unsecured debts into one payment over 3 to 5 years.
No. Taxes on cancelled debt (IRS Form 1099-C) only occur when a creditor forgives a portion of your principal balance (as in debt settlement). Because both debt consolidation and hardship programs involve repaying 100% of your principal, there is zero forgiven debt and zero tax liability.
Almost universally, no. As a condition of slashing your interest rate and waiving fees, the credit card issuer will freeze your charging privileges or close the account entirely to prevent your balance from increasing while in the workout program.
If you miss a scheduled payment under a hardship agreement, the lender will immediately cancel the concessionary terms. Your interest rate will instantly revert to the standard penalty APR (often 29.99%), late fees will resume, and the account may be escalated to internal collections or sold to a third-party collection agency.
For balances over $25,000, 0% balance transfer cards rarely provide large enough credit limits. If your credit score is 680+ and income is strong, a 5-year fixed personal consolidation loan provides stability. However, if your debt-to-income ratio exceeds 45%, a non-profit Debt Management Plan (DMP) is mathematically superior, reducing your APR without taking on new debt liabilities.
Jaiveer Hooda is the Lead Financial Researcher & Personal Finance Analyst at Grow Your Money Smart. Specializing in personal wealth optimization, index fund compounding, high-yield savings mechanics, and consumer debt elimination strategies. With a background in computer engineering, he applies mathematical modeling, cashflow simulations, and empirical risk analysis to evaluate personal finance vehicles and credit products. Every analysis is backed by verified regulatory disclosures, IRS tax schedules, and empirical APY compounding math.
Areas of Expertise: Personal Finance · High-Yield Savings Accounts (HYSA) · Index Funds & S&P 500 Compounding · Retirement Planning (401k/IRA) · Debt Optimization · Credit Card APR Mechanics.
Transparency & Editorial Policy: Editorial Standards | Report a Correction